

- Market Size (2026)
- USD 5.0 Bn
- Forecast (2036)
- USD 19.6 Bn
- CAGR (2026 to 2036)
- 14.7%
How big is Zero Sugar Beverages Market in 2026?
Sales in the zero sugar beverages market are projected to grow at 14.7% CAGR, with the market size rising from USD 4.4 billion in 2025 to USD 5.0 billion in 2026 and reaching USD 19.6 billion by 2036.
Rising consumer preference for calorie-controlled hydration and the phased elimination of added sugars from commercial beverage baskets led to the widespread development of zero sugar beverages. Market valuation rises from USD 4.4 billion in 2025 to USD 5.0 billion in 2026 and is projected to reach USD 19.6 billion by 2036, expanding at an accelerating 14.7% CAGR. This rapid adoption is underpinned by core retail volume shifts where carbonated zero sugar drinks account for 62.7% of product type demand in 2026, as mainstream cola drinkers transition toward sugar-free variants without altering their daily refreshment occasions. In January 2026, the World Health Organization published its updated global review of sugar-sweetened beverage taxes, documenting that structured fiscal levies are actively compelling industrial reformulation across non-alcoholic commercial lines [1]. Sports and functional drinks account for the remaining 37.3% share in 2026, supported by electrolyte and energy additions that provide active consumers functional utility beyond basic sugar avoidance. However, persistent sweetener aftertaste and consumer skepticism regarding synthetic additives continue to limit repeat purchasing across sensitive demographic cohorts.
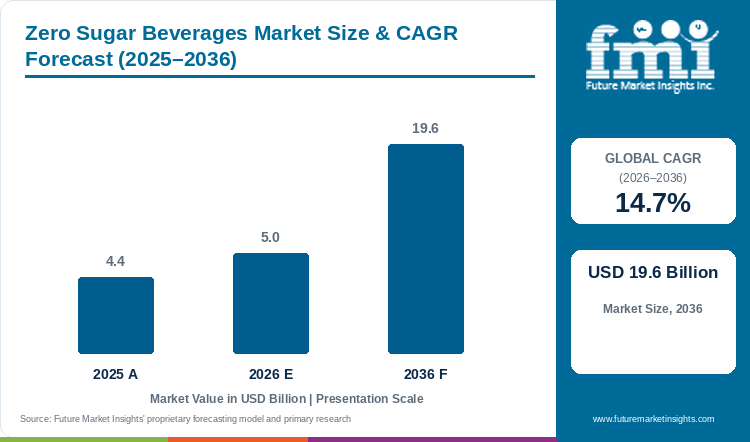
Key Market Trends & Insights
- By product type: Carbonated zero sugar drinks are projected to account for 62.7% in 2026, supported by familiar cola and sparkling beverage occasions.
- By product type: Sports and functional drinks represent 37.3% in 2026, driven by calorie-controlled hydration and energy positioning.
- By sales channel: Retail sales remain the wider route to market through supermarkets, convenience stores, e-commerce, pharmacies, and franchise outlets.
Regional Highlights
- Fastest-growing eligible evaluated country: USA, at 16.3% CAGR from 2026 to 2036.
- By country: Germany follows at 15.8%, while Japan records 10.2% CAGR across the eligible country data published by the source report.
Market Size & Forecast
Table 1: Market Size and Forecast for the Zero Sugar Beverages Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 4.4 billion |
| Estimated Market Size in 2026 | USD 5.0 billion |
| Projected Market Size by 2036 | USD 19.6 billion |
| CAGR, 2026 to 2036 | 14.7% |
| Added Revenue, 2026 to 2036 | USD 14.6 billion |
Country demand conditions differ across evaluated markets as regional beverage rules and tax treatment require localized recipe adjustments [2]. According to FMI analysis, sensory parity remains decisive on the retail shelf because buyers return to a reformulated beverage only when artificial sweetener notes and lingering aftertastes are successfully eliminated. Disparities in national sugar levies compel bottlers to validate distinct high-intensity sweetener blends across domestic packaging hubs. Established bottling networks maintaining robust cold-chain distribution and clear front-of-pack claims are positioned to sustain recurring household penetration ahead of niche diet brands.
Consumption and Revenue Intensity Sizing
Zero sugar formats now move across soft drinks packaging, energy drinks, hydration, and functional occasions. This widens revenue not by asking one consumer to drink more cola, but by giving the same sugar-conscious buyer more occasions during a day. The commercial opportunity strengthens where a brand extends into a second usage occasion without weakening taste or compromising clean-label ingredient transparency.
Table 2: Consumption and Revenue Intensity Sizing for the Zero Sugar Beverages Market (USD and indexed units), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 4.4 | 5.0 | 19.6 |
| Revenue per 1,000 global residents (USD) | 535 | 602 | 2,190 |
| Indexed category revenue (2026=100) | 88 | 100 | 392 |
| Added revenue versus 2026 (USD billion) | - | - | 14.6 |
Portfolio and Channel Sizing
The category is moving from conventional sodas into diet soft drinks and ready-to-drink formulations because sugar avoidance influences refreshment as well as performance-led purchases. A broader portfolio spreads formulation and distribution costs, although excessive extension risks shelf cannibalization.
Table 3: Product Portfolio Revenue Indicators for the Zero Sugar Beverages Market (USD billion and percentages), 2026
| Metric | Value | Basis |
|---|---|---|
| Total market size | USD 5.0 billion | Report value |
| Carbonated zero sugar drinks | USD 3.1 billion | 62.7% share |
| Sports and functional drinks | USD 1.9 billion | 37.3% share |
| Other product share | 0.0% | Source shares reconcile to 100.0% |
Table 4: Market Expansion Indicators for the Zero Sugar Beverages Market (USD billion and index), 2026 to 2036
| Metric | 2026 | 2036 | Change |
|---|---|---|---|
| Market value | 5.0 | 19.6 | 14.6 |
| Revenue index | 100 | 392 | +292 points |
| Ten-year multiple | 1.0x | 3.92x | 2.92x |
Analyst Perspective
“Zero sugar beverages are moving from diet-led niches into core beverage portfolios. Brands that sustain taste parity and credible labeling will secure wider retail distribution.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Zero Sugar Beverages Market segmented?
The zero sugar beverages market is segmented by product type and sales channel. In 2026, carbonated zero sugar drinks lead with 62.7%, while sports and functional drinks account for 37.3% of product type demand.
By product type: Carbonated Zero Sugar Drinks; Sports Drinks; Energy & Functional Drinks.
By sales channel: Retail Sales; B2B / HoReCa.
Why do Carbonated Zero Sugar Drinks lead the product type category?
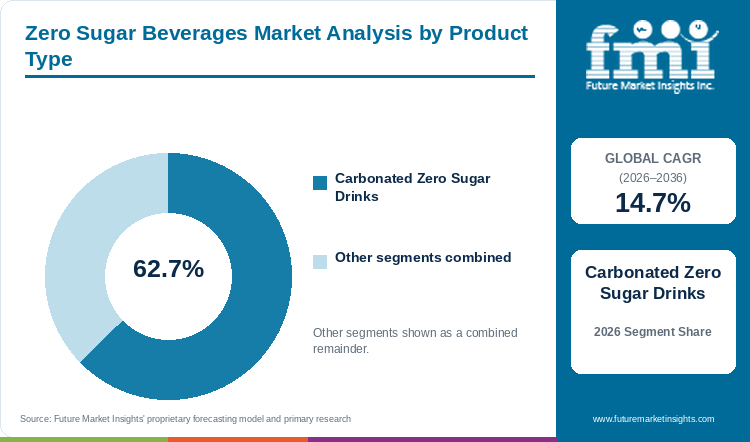
Carbonated zero sugar drinks represent 62.7% of product type in 2026, linking familiar taste rituals with calorie-free positioning.
Table 5: Product Type Share for the Zero Sugar Beverages Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Carbonated Zero Sugar Drinks | 62.7% |
| Other Segments Combined | 37.3%* |
| Total | 100.0% |
Table 6: Product Type Leadership and Market Growth for the Zero Sugar Beverages Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 14.7% |
| Leading Segment | Carbonated Zero Sugar Drinks |
Carbonated formats retain the widest household reach because consumers possess established purchase habits around meal pairings. The 62.7% share connects with frictionless substitution from regular carbonated lines, while ongoing research into natural sweeteners mitigates lingering chemical bitterness that obstructs repeat purchasing.
- Based on product type, carbonated zero sugar drinks are projected to account for 62.7% in 2026, supported by familiar brand architecture.
- In December 2025, PepsiCo reported 30.8% year-to-date sales growth for Pepsi Zero Sugar after a national taste campaign [3].
What keeps Sports and Functional Drinks relevant by product type?
Sports and functional drinks account for 37.3% of product type demand in 2026, pairing hydration utility with sugar avoidance.
Sports and functional drinks do not need to replicate cola purchase occasions. Added electrolytes, branched-chain amino acids, and botanical stimulants cater to workout and workplace routines, explaining why the category secures 37.3% share. Commercial momentum accelerates as functional beverages deliver transparent, performance-led utility without artificial aftertastes.
- By product type, sports and functional drinks are forecast to represent 37.3% in 2026, driven by active hydration occasions.
- Red Bull lists Red Bull Zero with zero sugar and 80 mg caffeine per 8.4 fluid ounce can [4].
Why do Retail Sales define the main sales channel?
Retail sales lead channel access in 2026 as shoppers compare zero sugar labels across high-frequency beverage purchase points.
Retail sales dominate commercial distribution as consumers compare ingredient panels across front-of-store coolers and supermarket aisles. Supermarkets facilitate pack-size price evaluation, convenience stores drive single-serve trial, and digital grocers foster subscription volume. This route places zero sugar lines directly alongside ready to drink beverages and premium sparkling water, where shelf prominence dictates velocity.
- Retail sales hold the primary channel position in 2026, underpinned by routine purchases and broad shelf visibility.
- In February 2026, Keurig Dr Pepper announced more than 35 new beverage varieties with additional zero sugar options [5].
What are the drivers, restraints, and opportunities in the Zero Sugar Beverages Market?
Sugar reduction policies elevate reformulation demand, whereas taste and sweetener skepticism limit repeat purchase, and functional zero sugar formats create premium value.
- Driver: Sugar-related fiscal policies and calorie awareness strengthen demand for beverages without added sugar.
- Restraint: Sweetener aftertaste and ingredient concerns can weaken repeat purchasing despite successful first-time trial.
- Opportunity: Functional hydration, energy, and natural-sweetener formulations extend zero sugar demand beyond carbonated colas.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Mandatory sugar levies and public health warnings provide manufacturers commercial incentives to reformulate, yet policy pressure alone does not guarantee brand loyalty. Cross-market tax structures vary significantly, meaning commercial returns on sugar-free lines differ across regulatory jurisdictions. In-store trial translates into sustained revenue only when sensory delivery mirrors conventional soda. Pepsi Zero Sugar distributed more than one million samples across 34 target regions, achieving 30.8% year-to-date sales growth in 2025 as taste parity eliminated consumer switching friction [3]. Furthermore, expanding convergence with sports nutrition establishes stable everyday purchasing routines.
Risk Assessment of the Zero Sugar Beverages Market: Formulation and Acceptance Friction
Sensory mismatch represents the primary operational bottleneck where initial trial fails to generate repeat procurement. Synthetic high-intensity sweeteners frequently produce metallic linger, while unbalanced acidulant systems disrupt familiar mouthfeel. Furthermore, consumer scrutiny over non-nutritive additives pushes brands toward flavored water alternatives. Because labeling directives and statutory excise definitions diverge across border markets [2], multinational bottlers must validate regional sweetener combinations, escalating qualification expenses.
Commercial Opportunity Analysis: Functional Differentiation and Value-Add Formats
Commercial upside extends beyond conventional carbonated colas into energy boosters, functional tonics, and premium botanical refreshments. Formulations integrating natural sweetener extracts with adaptogens or caffeine provide differentiated purchasing rationales. For example, Red Bull Zero pairs monk fruit extract with essential B-vitamins and 80 mg caffeine [4], while Keurig Dr Pepper expanded its refreshment catalog with 35 new zero sugar varieties [5]. Aligning clean-label sweeteners with plant-based beverages unlocks premium price realizations across health-conscious demographics.
Zero Sugar Beverages Market by Country (2026 to 2036)
Among the evaluated countries, the USA is expected to expand at 16.3% CAGR between 2026 and 2036, ahead of Germany at 15.8% and Japan at 10.2%. The gap does not mean that awareness is weak in Japan. It reflects a different starting point and a stronger presence of unsweetened beverages, while growth in the USA can be pushed by large cola systems, national sampling and wide cold-channel reach. Germany sits between these markets, where demand can gain from rising light-drink production but ingredient scrutiny can make repeat purchase slower.
Table 7: Country CAGR and Primary Growth Levers for the Zero Sugar Beverages Market (CAGR percentage and operational drivers), 2026 to 2036
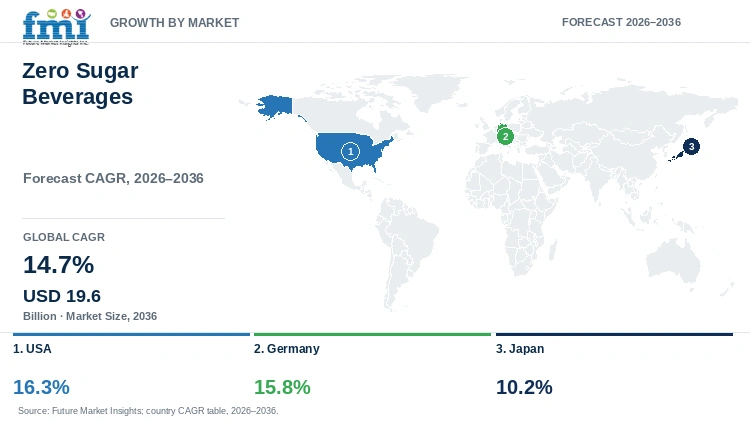
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 16.3% | Scaled zero sugar cola portfolios and national retail distribution |
| Germany | 15.8% | Health-led purchasing and reformulation across major beverage brands |
| Japan | 10.2% | Unsweetened beverage habits and strong convenience retail access |
USA Zero Sugar Beverages Market Outlook (2026 to 2036)
The USA zero sugar beverages market is projected to expand at 16.3% CAGR from 2026 to 2036, driven by scaled cold-vault retail distribution and aggressive brand sampling. Pepsi Zero Sugar expanded its household reach by more than one million consumers in 2025, validating that taste parity accelerates conversion [3]. The saturated shelf space and steep promotional allowances present continuous operational friction. Long-term volume stability requires brands to defend retail facings through consistent flavor innovation.
Key takeaway: In USA, national sampling and household penetration make taste parity central to zero sugar growth.
Key takeaway: In USA, national sampling and household penetration make taste parity central to zero sugar growth.
Germany Zero Sugar Beverages Market Outlook (2026 to 2036)
Germany is anticipated to advance at 15.8% CAGR over the forecast period, underpinned by rigorous clean-label scrutiny and statutory packaging mandates. Destatis reported that domestic production of reduced-calorie soft drinks reached 1.5 billion liters in 2024, demonstrating established consumer acceptance [6]. The consumer resistance to artificial additives forces beverage formulators to invest heavily in stevia and erythritol blending to secure retail listings.
Key takeaway: In Germany, ingredient transparency and trial-sized packs influence retail acceptance of reformulated drinks.
Key takeaway: In Germany, ingredient transparency and trial-sized packs influence retail acceptance of reformulated drinks.
Japan Zero Sugar Beverages Market Outlook (2026 to 2036)
Japan is forecast to register 10.2% CAGR through 2036, reflecting entrenched consumer habits around naturally unsweetened green teas and canned coffees. The 2025 Family Income and Expenditure Survey confirmed a 0.9% increase in real household consumption spending [7], supporting premium RTD beverage purchases. Western brands encounter commercial resistance unless formulations offer delicate sweetness and compact packaging suitable for dense convenience retail networks.
Key takeaway: In Japan, convenience-led beverage habits reward compact formats and subtle flavor differentiation.
Key takeaway: In Japan, convenience-led beverage habits reward compact formats and subtle flavor differentiation.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Zero Sugar Beverages Market?
The Coca-Cola Company, PepsiCo, Keurig Dr Pepper, Red Bull, Carlsberg Britvic, and Reliance Consumer Products are significant market players in this market.
Competition is led by beverage systems that can reformulate a known brand and place it across retail without building an occasion from the beginning. Coca-Cola, PepsiCo and Keurig Dr Pepper hold this advantage in carbonated drinks, while Red Bull uses the energy function to make zero sugar part of a performance purchase. Regional companies can move faster around local price and flavor, but a narrower distribution base can limit how quickly a successful product travels.
- Global Carbonated Beverage Platforms: The Coca-Cola Company, PepsiCo, and Keurig Dr Pepper.
- Energy and Functional Beverage Platforms: Red Bull and selected functional beverage portfolios within diversified groups.
- Regional and Multi-Category Players: Carlsberg Britvic and Reliance Consumer Products.
Competitive Benchmarking: Zero Sugar Beverages Market
Table 8: Competitive Benchmarking for the Zero Sugar Beverages Market (qualitative capability ratings), 2026
| Company | Zero Sugar Portfolio Breadth | Functional Range | Retail Access | Geographic Reach |
|---|---|---|---|---|
| The Coca-Cola Company | High | High | High | High |
| PepsiCo | High | High | High | High |
| Keurig Dr Pepper | High | High | High | Medium |
| Red Bull | Medium | High | High | High |
| Carlsberg Britvic | Medium | Medium | High | Medium |
| Reliance Consumer Products | Medium | Low | Medium | Low |
Scoring basis: High indicates broad evidence across the named capability. Medium indicates a narrower but established position. Low indicates limited public evidence within the exact market scope.
Key Developments in the Zero Sugar Beverages Market
- In February 2026, Keurig Dr Pepper announced more than 35 new beverage varieties, including additional zero sugar options.
- In December 2025, PepsiCo said Pepsi Zero Sugar achieved more than 30.8% year-to-date sales growth and reached over one million additional households. [3]
- In January 2025, Red Bull introduced a reformulated Red Bull Zero in the United States with monk fruit extract and zero sugar. [4]
Key Players in the Zero Sugar Beverages Market
Global Carbonated Beverage Platforms
- The Coca-Cola Company
- PepsiCo
- Keurig Dr Pepper
Energy and Functional Beverage Platforms
- Red Bull
- Carlsberg Britvic
Regional Beverage Platforms
- Reliance Consumer Products
Zero Sugar Beverages Market - Report Scope
Table 9: Report Scope for the Zero Sugar Beverages Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Type; Sales Channel |
| Quantitative Units | USD Billion |
| Market Definition | Includes supplier revenue from beverages formulated and marketed with zero grams of sugar across the listed product categories. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, Germany, Japan, and additional countries in the full report |
| Key Companies Covered | The Coca-Cola Company; PepsiCo; Keurig Dr Pepper; Red Bull; Carlsberg Britvic; Reliance Consumer Products |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Zero Sugar Beverages Market - Research Methodology
Table 10: Research Methodology for the Zero Sugar Beverages Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with manufacturers, suppliers, distributors, retailers, beverage professionals, industry experts, and key opinion leaders across the value chain. |
| Secondary Research | Secondary research included annual reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and public sources. |
| Market Sizing and Forecasting | Market sizing and forecasting for 2026 to 2036 used top-down and bottom-up approaches to assess revenue, category mix, price points, and channel adoption. |
| Data Triangulation and Validation | Data was validated against macro-economic indicators, relevant demand drivers, regulatory conditions, company disclosures, and historical trend analysis. |
Zero Sugar Beverages Market by Segments
Zero Sugar Beverages Market segmented by Product Type:
- Carbonated Zero Sugar Drinks
- Sports Drinks
- Energy & Functional Drinks
Zero Sugar Beverages Market segmented by Sales Channel:
- Retail Sales
- B2B / HoReCa
Zero Sugar Beverages Market by Region
- North America
- United States
- Canada
- Mexico
- Latin America
- Brazil
- Chile
- Western Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Hungary
- Balkan and Baltic Countries
- East Asia
- Japan
- South Korea
- South Asia and Pacific
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Turkiye
Research Sources and Bibliography
- [1] World Health Organization. (2026, January 13). Global report on the use of sugar-sweetened beverage taxes, 2025.
- [2] PepsiCo. (2025, December 3). Pepsi Zero Sugar expands the Pepsi Challenge after 2025 market gains. Commercial Press Release.
- [3] Red Bull North America. (2025, January 6). New year, new taste: Red Bull Zero launches nationwide. PRNewswire.
- [4] Keurig Dr Pepper. (2026, February 18). Keurig Dr Pepper announces flavorful new innovation across its refreshment portfolio.
- [5] Federal Statistical Office of Germany (Destatis). (2026, February 12). 93 litres of sugar-sweetened soft drinks produced per capita in 2024.
- [6] Statistics Bureau of Japan. (2026, February 6). 2025 yearly average: Family Income and Expenditure Survey.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the zero sugar beverages market in 2026 and what is forecast for 2036?
- Which policy and consumer pressures support demand for zero sugar beverages?
- Why do carbonated zero sugar drinks lead product type demand?
- How do sports and functional drinks widen category use?
- How do growth rates differ across the USA, Germany, and Japan?
- Which companies maintain broad zero sugar beverage portfolios?
- What limits adoption or repeat purchasing in the market?
- What should retail buyers evaluate before listing a zero sugar beverage?
Frequently Asked Questions
How big is the Zero Sugar Beverages Market in 2026, and what is forecast for 2036?
Future Market Insights estimates that the global market will reach USD 5.0 billion in 2026 and USD 19.6 billion by 2036.
What is the CAGR from 2026 to 2036?
As per FMI, the market is projected to expand at 14.7% CAGR over the assessment period.
Which product type leads the market?
Carbonated zero sugar drinks are projected to hold 62.7% of product type demand in 2026. The segment benefits from familiar brand architecture and established cold-channel availability.
What share is represented by sports and functional drinks?
Sports and functional drinks account for 37.3% of product type demand in 2026.
Which eligible country has the fastest published growth outlook?
The USA is projected to register 16.3% CAGR from 2026 to 2036 among the eligible published country rates.
Who are the key players?
Key participants include The Coca-Cola Company, PepsiCo, Keurig Dr Pepper, Red Bull, Carlsberg Britvic, and Reliance Consumer Products.
What limits adoption or repeat purchasing in the Zero Sugar Beverages Market?
Lingering sweetener aftertaste and consumer skepticism regarding artificial ingredients limit repeat purchase, requiring continuous recipe refinement.
What should retail buyers evaluate before listing a Zero Sugar Beverages Market?
Retailers evaluate taste parity with regular equivalents, transparent ingredient labeling, dependable cold-chain supply, and promotional support.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Carbonated Zero Sugar Drinks
- Sports Drinks
- Energy & Functional Drinks
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Retail Sales
- B2B / HoReCa
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Product Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- By Product Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Hungary
- Balkan and Baltic Countries
- By Product Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- By Product Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- ASEAN
- Australia and New Zealand
- By Product Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sales Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Turkiye
- By Product Type
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Sales Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- The Coca-Cola Company
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- PepsiCo
- Keurig Dr Pepper
- Red Bull
- Carlsberg Britvic
- Reliance Consumer Products
- The Coca-Cola Company
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


