
- Market Size (2026)
- USD 9.9 Bn
- Forecast (2036)
- USD 20.6 Bn
- CAGR (2026 to 2036)
- 7.6%
How big is Ultrapure Water Market in 2026?
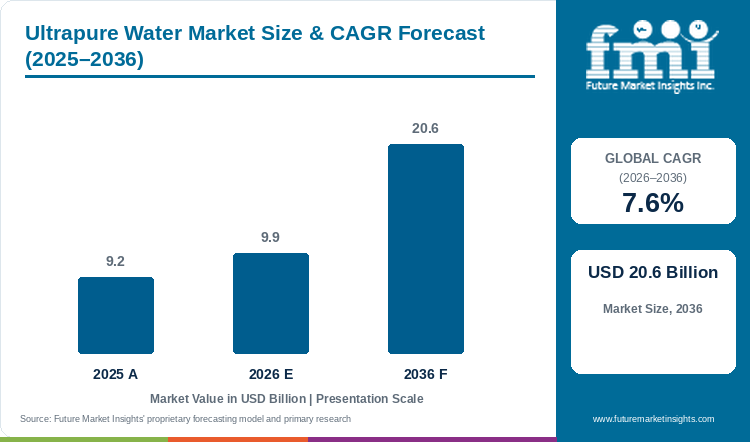
The ultrapure water market demonstrated steady progress from USD 9.2 billion in 2025 to USD 9.9 billion in 2026, building toward a targeted valuation of USD 20.6 billion by 2036 at a CAGR of 7.6%.
The global ultrapure water market was valued at USD 9.2 billion in 2025 and is estimated to reach USD 9.9 billion in 2026. Overall market valuation is projected to reach USD 20.6 billion by 2036, expanding at a compound annual growth rate (CAGR) of 7.6% between 2026 and 2036. Reverse Osmosis RO Filtration holds an estimated 44.0% share of 2026 equipment demand, given that multi-pass spiral-wound membranes anchor primary demineralization in every sub-nanometer purification train. Buyer adoption tracking at FMI shows that ultrapure water system orders are accelerating as logic and DRAM foundries transition to gate-all-around nanosheet architectures that require more than 1,500 gallons of 18.2 megohm-centimeter water per 300-millimeter silicon wafer.
That cleanroom water intensity separates ultrapure water systems from the broader membrane filtration systems sector at 6.4% CAGR, since fab operators must strip total organic carbon below 1 part per billion and dissolved silica below 0.3 parts per billion on continuous recirculation loops. Industry equipment records from SEMI confirm this downstream pull, reporting in July 2026 that global 300-millimeter memory fab equipment investment is projected to climb 29% to USD 52 billion in 2026 [1]. Water technology providers are consolidating electronics purification assets to capture these turnkey fab contracts, evidenced when Ecolab completed its USD 1.8 billion acquisition of Ovivo's semiconductor water business in December 2025 [2]. Foundries award long-term ultrapure water build-own-operate and membrane replacement contracts to suppliers that guarantee sub-ppb organic purity and 80% wastewater reclamation through 2036.
Key Market Trends & Insights
- By equipment and process: Reverse Osmosis RO Filtration holds an estimated 44.0% share in 2026 since two-pass polyamide membrane trains remove bulk conductivity and total organic carbon prior to electrodeionization.
- By end-use industry: Semiconductor and Microelectronics Wafer Fabs represent 58.0% in 2026 given that 300-mm wafer fabs consume 4.8 million to 10 million gallons of purified water daily.
- By application: Semiconductor Silicon Wafer Washing and Wet Chemical Rinsing account for 62.0% in 2026 as chemical mechanical planarization and post-etch cleaning run between every photolithography layer.
- By system delivery mode: Aftermarket Consumables and Membrane Replacement secure 46.0% in 2026 owing to scheduled change-outs of reverse osmosis elements, nuclear-grade mixed-bed resins, and 185-nm UV lamps.
- By purity grade: Type E-1 Sub-2 nm Semiconductor Grade UPW commands 56.0% in 2026 through strict SEMI F63 and ASTM D5127 trace-metal and nanoparticle thresholds.
Regional Highlights
- Top national expansion: Mexico leads national growth projections at an 8.8% CAGR through 2036 under electronics assembly nearshoring and industrial effluent reuse investments.
- Broader country progression: South Korea tracks at an 8.7% CAGR ahead of the USA at 8.1% and China at 7.9%, while Germany advances at a 7.0% CAGR.
Market Size & Forecast
Table 1: Market Size and Forecast for the Ultrapure Water Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 9.2 billion |
| Estimated Market Size in 2026 | USD 9.9 billion |
| Projected Market Size by 2036 | USD 20.6 billion |
| CAGR, 2026 to 2036 | 7.6% |
| Added Revenue, 2026 to 2036 | USD 10.7 billion |
Advanced semiconductor fabs fabricating 2-nanometer logic and high-bandwidth memory stacks execute more than 1,000 individual processing steps per wafer, over half of which require ultra-clean wet chemical rinsing and planarization. Even trace parts-per-trillion metallic ions or organic oligomers left in rinse water bridge nanoscale transistor gates and ruin wafer die yields. Empirical findings published in Environmental Science & Technology Letters in August 2025 substantiate this consumption intensity, demonstrating that a single semiconductor fab consumes over 10,000 cubic meters of ultrapure water daily with chemical mechanical planarization accounting for roughly one-third of total demand [3]. Consequently, fab facility directors integrate multi-barrier semiconductor water purification trains with real-time laser particle counters to protect cleanroom yield.
Fab Water Consumption and Purification Sizing
Table 2: Fab Water Consumption and Purification Sizing for the Ultrapure Water Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 9.2 | 9.9 | 20.6 |
| Global semiconductor & industrial UPW output (million m3/day) | 9.4 to 10.2 | 10.1 to 11.0 | 19.8 to 21.6 |
| Average UPW consumption per 300-mm silicon wafer (gallons) | 1,450 to 1,550 | 1,500 to 1,620 | 1,650 to 1,800 |
| Fab UPW recycling & reclamation rate across leading hubs (%) | 62.0% to 68.0% | 65.0% to 72.0% | 80.0% to 88.0% |
Municipal drought restrictions across the American Southwest, Taiwan, and European river basins are forcing semiconductor and power plant operators to pair primary ultrapure water make-up trains with closed-loop wastewater reclamation. In September 2025, the SEMI Environmental Risk Mitigation Working Group evaluated 140 global semiconductor facilities across 89 watersheds, documenting that single fabs withdraw up to 10 million gallons daily and over 40% of new fabs announced since 2021 sit in high-water-stress basins [4]. Facility engineers therefore couple deionized water systems with segregated hydrofluoric acid and chemical mechanical planarization recycling skids to reuse up to 85% of process water internally.
Cleanroom Loop & Channel Spending Indicators
Table 3: Wafer Fab and Industrial Spending Indicators for the Ultrapure Water Market (USD and operational metrics), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Global 300-mm memory fab equipment spending (USD billion, SEMI) | 40.3 | 52.0 | 85.0 to 92.0 |
| Daily UPW demand per 40,000-WSPM 300-mm logic/DRAM fab (million gallons) | 4.5 to 5.2 | 4.8 to 5.5 | 5.8 to 6.8 |
| Type E-1 semiconductor UPW TOC specification ceiling (ppb) | < 1.0 ppb | < 1.0 ppb | < 0.5 ppb |
| Two-pass RO + CEDI share of new UPW demineralization trains (%) | 74.0% | 76.5% | 88.0% |
Table 4: Semiconductor & Channel Allocation Indicators for the Ultrapure Water Market (USD billion and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 9.9 billion | 2026 global ultrapure water valuation baseline |
| Semiconductor Wafer Fabs end-use revenue, 2026 | USD 5.7 billion | 58.0% end-use share across logic, memory, and power fabs (SEMI / SIA basis) |
| CMP share of total semiconductor fab UPW consumption | 33.0% to 35.0% | ACS ES&T Letters August 2025 semiconductor fab water balance study |
| Required EU semiconductor UPW capex by 2030 | EUR 2.24 billion | European Commission / Water Europe March 2025 Water Resilience Strategy docket |
High-pressure reverse osmosis skids operating in 24-hour ultrapure water plants consume substantial electrical pumping energy while generating concentrated reject brines that require secondary recovery. Updated technical guidelines from the U.S. Department of Energy Federal Energy Management Program in February 2026 confirm that standard reverse osmosis purification systems recover 50% to 75% of feedwater while rejecting 25% to 50% as concentrate unless staged brine recovery is installed [5]. System integrators consequently pair low-energy polyamide membranes with ultrapure fittings and high-recovery electrodeionization stacks to cut plant power and water waste.
Analyst Perspective
"Semiconductor foundries and biopharmaceutical plants do not buy ultrapure water equipment as standalone tanks; they buy guaranteed sub-part-per-billion organic purity, zero unplanned fab downtime, and closed-loop water recycling. System integrators that combine proprietary low-leaching membranes and mixed-bed resins with multi-year on-site operating contracts will capture the lion's share of new megafab utility awards."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Ultrapure Water Market segmented?
The ultrapure water market is segmented by equipment and process, end-use industry, application, system delivery mode, and purity grade. In 2026, Reverse Osmosis RO Filtration is projected at 44.0%, Semiconductor and Microelectronics Wafer Fabs at 58.0%, Semiconductor Silicon Wafer Washing and Wet Chemical Rinsing at 62.0%, Aftermarket Consumables and Membrane Replacement at 46.0%, and Type E-1 Sub-2 nm Semiconductor Grade UPW at 56.0%.
By equipment and process: Reverse Osmosis RO Filtration; Electrodeionization EDI Modules; Ion Exchange Resins Polishing Beds; Ultrafiltration UF and Microfiltration; and Ultraviolet UV TOC Reduction Lamps.
By end-use industry: Semiconductor and Microelectronics Wafer Fabs; Pharmaceutical and Biomanufacturing WFI Injectables; Power Generation Supercritical Boilers; and Flat Panel Display and Photovoltaic Solar Cell Fabs.
By application: Semiconductor Silicon Wafer Washing and Wet Chemical Rinsing; Pharmaceutical Formulation and Biotechnology Fermentation Media; Steam Boiler Turbine Feedwater; and Precision Optics and Photolithography Immersion Cleaning.
By system delivery mode: Aftermarket Consumables and Membrane Replacement; Turnkey Design-Build-Operate Plants; Modular Skids and Package Units; and Build-Own-Operate On-Site Water Services.
By purity grade: Type E-1 Sub-2 nm Semiconductor Grade UPW; Pharmacopeia Water for Injection WFI Grade UPW; High-Pressure Supercritical Boiler Grade UPW; and Analytical and Laboratory Reagent Grade UPW.
Why does Reverse Osmosis RO Filtration lead the equipment and process category?
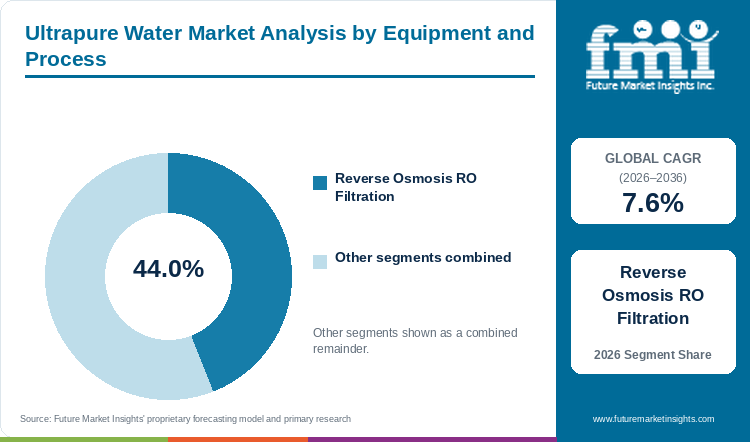
Reverse Osmosis RO Filtration holds an estimated 44.0% of equipment and process demand in 2026, anchored by two-pass demineralization and organic rejection.
Table 5: Equipment and Process Share for the Ultrapure Water Market (percentage share), 2026
| Equipment and Process | Share (2026) |
|---|---|
| Reverse Osmosis RO Filtration | 44.0% |
| Other Segments Combined | 56.0%* |
| Total | 100.0% |
*Note: Remaining equipment and process categories account for the balance of 2026 global ultrapure water demand.
Table 6: Equipment and Process Leadership and Market Growth for the Ultrapure Water Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.6% |
| Leading Segment | Reverse Osmosis RO Filtration |
Reverse Osmosis RO Filtration acts as the primary demineralization workhorse in every ultrapure water facility since two-pass thin-film composite polyamide membranes strip 98% to 99.9% of dissolved salts, silica, and organic precursors before downstream polishing. Plant designers configuring membrane separation technology trains rely on two-pass reverse osmosis to protect sensitive electrodeionization modules and nuclear-grade mixed-bed resins from premature ionic exhaustion. Experimental evaluations published in Separations in March 2026 confirm this design logic, demonstrating that pairing a high-permeability first-pass RO membrane with a high-selectivity second-pass RO membrane cuts permeate total organic carbon to 10.2 micrograms per liter [6]. Membrane biofouling and chlorine oxidation remain the primary operational hurdles requiring dechlorination and ultrafiltration pretreatment.
- Within the equipment and process segment, Reverse Osmosis RO Filtration is projected to account for a leading 44.0% share in 2026, anchored by primary make-up and wastewater reclamation skids.
- Electrodeionization modules and 185-nanometer ultraviolet TOC reduction lamps are forecast to post rapid co-adoption through 2036 as fabs eliminate bulk acid and caustic chemical regeneration.
What sustains Semiconductor and Microelectronics Wafer Fabs leadership in the end-use industry segment?
Semiconductor and Microelectronics Wafer Fabs represent 58.0% of the end-use industry category in 2026, supported by 300-mm logic and HBM memory fab buildouts.
Semiconductor and Microelectronics Wafer Fabs dominate global ultrapure water expenditure on account of the massive volumetric flow rates and extreme sub-part-per-trillion ionic purity required across 300-millimeter cleanrooms. While pharmaceutical injectable plants consume smaller batch volumes of water for injection and supercritical power boilers tolerate parts-per-billion silica, semiconductor foundries circulate thousands of cubic meters per hour through ultrafiltration membranes and point-of-use polishers. Long qualification cycles of 18 to 24 months for new fab water vendors act as a major entry barrier for uncertified equipment fabricators.
- In 2026, Semiconductor and Microelectronics Wafer Fabs are anticipated to capture 58.0% of global end-use industry demand, reflecting surging investments in artificial intelligence logic and HBM memory fabs.
- Industry investment records published by the Semiconductor Industry Association in July 2025 confirm over 100 announced private-sector U.S. semiconductor supply chain projects across 28 states that are projected to triple domestic chipmaking capacity by 2032 [7].
How does Semiconductor Silicon Wafer Washing and Wet Chemical Rinsing lead the application category?
Semiconductor Silicon Wafer Washing and Wet Chemical Rinsing account for 62.0% of application demand in 2026, driven by CMP and post-etch cleaning steps.
Semiconductor Silicon Wafer Washing and Wet Chemical Rinsing command the largest application segment since every wet etching, photoresist stripping, and chemical mechanical planarization step must be followed immediately by ultraclean deionized water rinsing. Fabs installing membrane microfiltration and hollow-fiber final filters at the wet bench prevent sub-10-nanometer silica and polymer particles from redepositing onto exposed silicon wafers. Process engineering research published in Water in August 2026 demonstrated how 18.25 megohm-centimeter ultrapure water washing enables 79.6% fluoride recovery as pure cryolite from acidic semiconductor oxide-etching waste liquors [8].
- By application, demand from Semiconductor Silicon Wafer Washing and Wet Chemical Rinsing is estimated to reach 62.0% of total category share in 2026 as 3D NAND and gate-all-around layer counts multiply.
- Pharmaceutical formulation and biotechnology fermentation media are projected to expand steadily through 2036 as biologics manufacturers adopt ambient membrane-based water-for-injection generation.
Why do Aftermarket Consumables and Membrane Replacement lead the system delivery mode category?
Aftermarket Consumables and Membrane Replacement secure 46.0% of system delivery mode demand in 2026, supported by continuous 24/7 membrane and resin change-outs.
Aftermarket Consumables and Membrane Replacement command the largest share of supplier revenue given that continuous 24/7 ultrapure water recirculation subjects reverse osmosis elements and mixed-bed polishing resins to steady fouling and degradation. Foundries cannot risk trace boron or total organic carbon breakthrough during production runs, prompting facility managers to execute strict preventive replacement schedules every 12 to 36 months. Disposal of spent ion-exchange resins and fluoropolymer filter cartridges represents an ongoing environmental compliance cost for plant operators.
- Scheduled replacement cycles across installed fab and pharma water plants place Aftermarket Consumables and Membrane Replacement on course to hold an estimated 46.0% share of the system delivery mode category in 2026.
- Component manufacturers are innovating to capture this replacement demand, as seen when Toray Industries announced in June 2026 the commercial launch of its TSW-series next-generation reverse osmosis membranes delivering 99.92% salt rejection and 96% boron rejection [9].
What gives Type E-1 Sub-2 nm Semiconductor Grade UPW the leading position in purity grade?
Type E-1 Sub-2 nm Semiconductor Grade UPW commands 56.0% of purity grade share in 2026, anchored by 18.2 megohm-centimeter and sub-1-ppb TOC cleanroom specs.
Type E-1 Sub-2 nm Semiconductor Grade UPW leads purity grade demand since advanced logic and DRAM fabs require water at theoretical ionic purity limits of 18.24 megohm-centimeter resistivity and less than 1 part per billion total organic carbon. Preservation of Type E-1 purity from the central utility building to cleanroom wet benches requires virgin polyvinylidene fluoride or non-fluorinated ultra-clean loop piping that will not leach organic carbon. Computational fluid dynamics and pipe autopsy studies published in Water in February 2026 verified that ISO Class 5 cleanroom PVDF piping maintained low organic extractables of 0.4 to 2.3 milligrams per liter after eight months of continuous UPW operation compared with 16 to 18 milligrams per liter in standard CPVC elbows [10].
- Type E-1 Sub-2 nm Semiconductor Grade UPW is predicted to secure 56.0% of purity grade demand in 2026, anchored by leading-edge 300-mm wafer fabrication plants.
- Pharmacopeia Water for Injection WFI Grade UPW is anticipated to record solid growth through 2036 as sterile injectable and cell-therapy facilities expand membrane WFI loops.
What are the drivers, restraints, and opportunities in the Ultrapure Water Market?
In the ultrapure water market, 300-mm semiconductor megafab capex and rising GAA layer counts are projected to drive adoption whereas watershed scarcity and PFAS effluent limits restrain permits and modular skids and closed-loop recycling create high-margin opportunities.
- Driver: Multi-billion-dollar 300-mm semiconductor megafab construction and rising wet-cleaning layer counts in 2-nm and 3D NAND chips drive large-scale ultrapure water system and consumable orders.
- Restraint: High municipal water withdrawal footprints and strict PFAS and fluoride effluent discharge limits delay environmental permitting and raise capital costs for new fab water plants.
- Opportunity: Prefabricated off-the-line modular UPW skids, PFAS-free cleanroom piping, and closed-loop zero-liquid-discharge recycling open rapid fab commissioning and recurring service revenues.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Sovereign semiconductor incentives across North America, East Asia, and Europe are triggering an unprecedented wave of greenfield 300-millimeter wafer fab construction that directly pulls utility-scale ultrapure water plants into backlog. Each new logic or DRAM megafab requires a dedicated multi-train purification facility capable of producing 20,000 to 50,000 cubic meters per day of sub-part-per-billion rinse water paired with integrated zero liquid discharge systems for wastewater reuse. Federal environmental records published by NIST in January 2026 illustrate this scale, confirming approval for Micron's USD 100 billion four-fab DRAM megaproject in Clay, New York encompassing 2.4 million square feet of cleanroom space and dedicated Lake Ontario water infrastructure [11]. These multi-year megaprojects lock in a decade of initial EPC buildouts followed by high-margin membrane and resin replacement streams.
Risk Assessment of the Ultrapure Water Market: Operational and Formulation Friction
Heightened watershed stress and tightening environmental regulations on per- and polyfluoroalkyl substances and concentrated brine discharges represent the primary operational hurdles restraining new ultrapure water plant approvals. Because producing 1,000 gallons of ultrapure water requires approximately 1,600 gallons of municipal feedwater and semiconductor wet-etching effluents contain elevated fluorides and fluorinated surfactants, environmental agencies are enforcing strict discharge ceilings. Peer-reviewed research published in iScience in September 2025 documented PFAS concentrations reaching 78,000 parts per trillion in untreated semiconductor fab effluents while noting that European fabs recycle only 10% to 14% of water compared with 80% in Taiwan [12]. Wafer fabs must therefore integrate PFAS foam fractionation systems and selective ion-exchange scrubbers into their water treatment trains before securing operating permits.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Water engineering firms are capturing high-margin contracts by replacing slow stick-built on-site construction with prefabricated, cloud-monitored modular ultrapure water supply skids and non-fluorinated distribution piping. Conventional custom-engineered fab water plants require 18 to 24 months of on-site welding and commissioning, which bottlenecks rapid semiconductor and electronics capacity expansions. To accelerate this modular shift, Kurita Water Industries announced in October 2025 that its spin-off InQuuater Inc. began taking orders for the e-WT prefabricated ultrapure water supply system that cuts delivery and installation schedules by 30% [13]. Suppliers across the industrial water treatment landscape that pair modular skids with automated digital-twin TOC monitoring are winning fast-track electronics and biopharma expansions.
Ultrapure Water Market by Country (2026 to 2036)
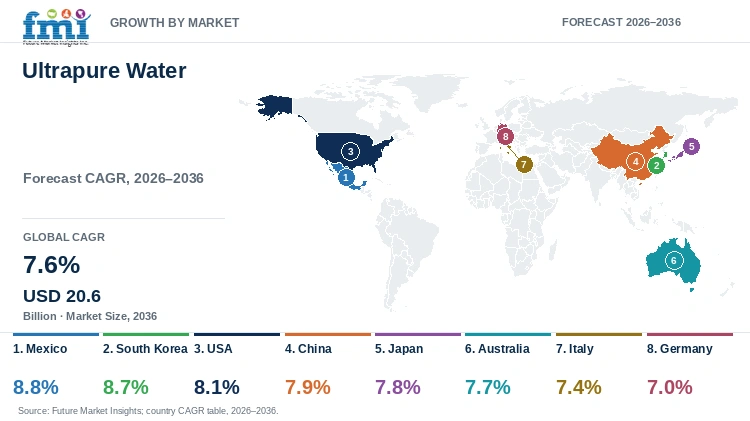
FMI country modeling indicates that Mexico leads ultrapure water expansion at an 8.8% CAGR through 2036, while Germany advances at a 7.0% CAGR. National growth rates reflect greenfield semiconductor megafab construction, electronics assembly nearshoring, and mandatory industrial water recycling investments.
Table 7: Country CAGR and Primary Growth Levers for the Ultrapure Water Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Mexico | 8.8% | Electronics OSAT nearshoring and industrial saline effluent RO-IEX water reuse |
| South Korea | 8.7% | Yongin Semiconductor Mega-Cluster water pipeline pact and KRW 14T chip financing |
| USA | 8.1% | TSMC 12-facility Arizona expansion and Micron USD 100B New York DRAM megaproject |
| China | 7.9% | 300-mm foundry expansion and mandatory 80%+ fab water reclamation quotas |
| Japan | 7.8% | METI-backed JASM Kumamoto 3-nm Fab 2 upgrade and Rapidus 2-nm cleanroom buildout |
| Australia | 7.7% | 351 GL self-extracted manufacturing water base, green hydrogen, and biopharma WFI |
| Italy | 7.4% | Catania silicon carbide power wafer fab expansion and pharmaceutical WFI loops |
| Germany | 7.0% | Dresden European Chips Act fabs and EUR 2.24B EU semiconductor UPW investment |
Source: Future Market Insights analysis
Mexico Ultrapure Water Market Outlook (2026 to 2036)
Demand for ultrapure water systems in Mexico is projected to expand at a leading 8.8% CAGR between 2026 and 2036 as outsourced semiconductor assembly and pharmaceutical sterile fill-finish lines scale across northern industrial corridors. What sets Mexico apart from traditional wafer-foundry hubs is the acute scarcity of municipal freshwater in northern industrial corridors, which forces electronics and biopharma plants to generate ultrapure water directly from treated brackish and saline industrial effluents. Membrane process trials published in Membranes in April 2025 by Mexican researchers demonstrated that an integrated reverse osmosis and two-stage mixed-bed ion-exchange resin train achieved 99.9% deionization efficiency from saline industrial effluent [14]. Industrial park developers across Mexico are consequently specifying modular RO-EDI reclamation skids to guarantee uninterrupted high-purity water supply.
Key takeaway: In Mexico, electronics and pharmaceutical nearshoring paired with industrial effluent reclamation are projected to drive leading demand for modular RO-EDI ultrapure water skids.
South Korea Ultrapure Water Market Outlook (2026 to 2036)
In South Korea, ultrapure water market growth is forecast to reach an 8.7% CAGR through 2036, anchored by the world's largest concentration of 300-millimeter DRAM and foundry megafabs in Gyeonggi Province. South Korea diverges from Western markets through its state-backed utility infrastructure model that coordinates bulk industrial water pipelines directly with domestic memory and foundry expansions, while pushing localization of ultra-pure membranes and degassing modules. Official policy disclosures from the Ministry of Economy and Finance of the Republic of Korea confirm a binding infrastructure pact to deliver dedicated industrial water supply by 2031 and 3 gigawatts of power by 2030 to the Yongin Semiconductor Mega-Cluster supported by KRW 14 trillion in chip policy financing [15]. Japanese and Korean UPW engineering leaders compete intensely on sub-nanometer particle removal and high-rate CMP wastewater recycling across Yongin, Pyeongtaek, and Icheon.
Key takeaway: In South Korea, the Yongin Semiconductor Mega-Cluster buildout and KRW 14 trillion chip financing program are forecast to sustain massive turnkey UPW plant and consumable demand.
USA Ultrapure Water Market Outlook (2026 to 2036)
Commercial ultrapure water demand in the USA is anticipated to advance at an 8.1% CAGR from 2026 to 2036 as multi-fab semiconductor campuses in Arizona, New York, and Texas transition from structural shell construction to continuous wafer production. Compared with Asian foundry hubs located near coastal desalination plants, U.S. fabs in arid Arizona and inland corridors must engineer high-recovery zero-liquid-discharge and brine-minimization loops to satisfy federal and state environmental records of decision. Federal announcements from NIST in July 2026 verified that TSMC expanded its U.S. semiconductor manufacturing commitment to 12 fabrication and advanced packaging facilities in Phoenix, Arizona [16]. These 12 Arizona facilities coupled with domestic memory and logic megafabs create a multi-decade baseline for turnkey UPW plants and recurring mixed-bed resin regeneration.
Key takeaway: In the USA, 12 planned Arizona fabs and domestic DRAM megaprojects are anticipated to anchor multi-year turnkey UPW engineering and aftermarket membrane contracts.
China Ultrapure Water Market Outlook (2026 to 2036)
Ultrapure water system sales in China are estimated to progress at a 7.9% CAGR over the 2026 to 2036 window across domestic 300-millimeter silicon wafer foundries and biopharmaceutical manufacturing bases. China's domestic market is characterized by strict national industrial water-efficiency quotas that mandate 80% to 85% process water reclamation inside electronics and flat-panel display parks coupled with rapid adoption of domestically assembled RO and CEDI skids. Corporate strategic disclosures from Veolia in June 2026 confirm how multinational water leaders are expanding Asia-Pacific semiconductor UPW laboratory and innovation capabilities under its EUR 1 billion GreenUp program to serve regional chipmakers [17]. High-purity fluoride crystallization and organic solvent stripping remain top investment priorities across Yangtze River Delta and Greater Bay Area wafer fabs.
Key takeaway: In China, domestic 300-mm wafer fab expansion and mandatory 80%-plus water recycling quotas are estimated to drive steady procurement of high-recovery UPW and reclamation trains.
Japan Ultrapure Water Market Outlook (2026 to 2036)
Japanese ultrapure water procurement is slated to expand at a 7.8% CAGR across the 2026 to 2036 timeframe, revitalized by state-subsidized 2-nanometer and 3-nanometer logic semiconductor fabs in Kyushu and Hokkaido. What distinguishes Japan is its vertically integrated domestic supply base of UPW engineering leaders led by Kurita Water Industries and Organo Corporation paired with proprietary Japanese hollow-fiber ultrafiltration and low-boron reverse osmosis membranes. Official press conference records from Japan's Ministry of Economy, Trade and Industry in April 2026 confirmed regulatory approval and up to JPY 732 billion in government support to upgrade TSMC's second Kumamoto JASM plant to manufacture 3-nanometer semiconductors [18]. Domestic fabs also lead early commercial testing of PFAS-free olefin resin ultrapure water piping and automated off-site resin regeneration.
Key takeaway: In Japan, 3-nm Kumamoto and 2-nm Hokkaido fab investments supported by METI subsidies are slated to accelerate domestic turnkey UPW and ultra-clean piping installations.
Australia Ultrapure Water Market Outlook (2026 to 2036)
In Australia, demand for ultrapure water systems is expected to grow at a 7.7% CAGR through 2036, driven by biopharmaceutical sterile injectable manufacturing and green hydrogen proton-exchange-membrane electrolyzer projects. Australian industrial operators face recurrent drought cycles that require pairing seawater desalination and industrial effluent reverse osmosis with electrodeionization polishing to produce demineralized electrolyzer and boiler feedwater. National environmental accounts published by the Australian Bureau of Statistics in December 2025 confirm rising industrial water intensity, reporting that self-extracted manufacturing water intake rose 18.7% year-over-year to 351 gigaliters while desalinated water supply reached 170 gigaliters [19]. Modular containerized RO-EDI units are widely specified across Australian hydrogen hubs and biomedical precincts in Melbourne, Sydney, and Brisbane.
Key takeaway: In Australia, rising manufacturing water intake and green hydrogen and biopharma expansion are expected to sustain strong demand for containerized RO-EDI systems.
Italy Ultrapure Water Market Outlook (2026 to 2036)
Italian ultrapure water expenditure is likely to increase at a 7.4% CAGR from 2026 through 2036 across silicon carbide power semiconductor wafer fabs in Sicily, sterile pharmaceutical injectable plants in Lombardy, and high-pressure industrial cogeneration boilers. Italy differs from northern European markets due to acute summer water stress in southern industrial zones such as Catania, where semiconductor fabs must integrate municipal wastewater reclamation directly ahead of ultrapure water make-up trains. Material innovation from suppliers such as Kurita Water Industries, which achieved a development milestone in July 2025 for PFAS-free special olefin resin UPW piping matching PVDF purity, supports European fabs seeking compliant fluoropolymer alternatives [20]. Italian pharmaceutical contract development and manufacturing organizations also drive steady upgrades to cold-loop membrane water-for-injection skids.
Key takeaway: In Italy, silicon carbide power wafer fab expansions in Catania and pharmaceutical WFI loop upgrades are likely to support sustained UPW equipment and membrane sales.
Germany Ultrapure Water Market Outlook (2026 to 2036)
German ultrapure water sales are predicted to move ahead at a 7.0% CAGR during the 2026 to 2036 period, anchored by Silicon Saxony semiconductor fab expansions in Dresden and industrial hydrogen and biomanufacturing plants. German engineering standards enforce Europe's strictest industrial effluent trace-contaminant limits and REACH fluoropolymer restrictions, compelling fab owners to invest heavily in closed-loop UPW recycling and non-PFAS filtration components. Policy impact filings submitted to the European Commission in March 2025 estimate that European semiconductor capacity expansion will increase annual freshwater demand by 216 million cubic meters and require EUR 2.24 billion in dedicated capital investment for ultrapure water systems by 2030 [21]. Suppliers operating localized resin regeneration and pilot membrane centers in Germany are best positioned to capture these European Chips Act utility packages.
Key takeaway: In Germany, Dresden semiconductor fab investments and EUR 2.24 billion in projected European UPW capital requirements are predicted to anchor high-recovery purification contracts.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the Ultrapure Water Market?
Kurita Water Industries Ltd., Organo Corporation, Veolia Water Technologies, Xylem Inc., Ecolab Inc.,Nomura Micro Science Co. Ltd., DuPont de Nemours Inc., Danaher Corporation, and Pentair plc are the notable companies in the ultrapure water market.
Competitive positioning in the ultrapure water industry separates full-scope turnkey semiconductor UPW plant engineering leaders, diversified global water technology platforms, and specialized filtration manufacturers. Kurita Water Industries Ltd. and Organo Corporation as well as Nomura Micro Science Co. Ltd. The design and operate ultra-high-purity electronics and power water plants. Veolia Water Technologies and Xylem Inc. as well as Ecolab Inc. provide global turnkey systems and Ionpure CEDI modules, while DuPont de Nemours Inc. and Danaher Corporation through Pall Corporation plus Pentair plc supply critical RO, UF, and ion-exchange consumables.
- Turnkey Semiconductor and Industrial UPW Engineering Leaders: Kurita Water Industries Ltd., Organo Corporation, Nomura Micro Science Co. Ltd., design, build, and operate sub-2-nm wafer fab and supercritical boiler UPW systems.
- Global Integrated Water Technology and Service Platforms: Veolia Water Technologies, Xylem Inc., and Ecolab Inc. combine global engineering, Evoqua Ionpure CEDI modules, and Ovivo Ultrapure Water+ electronics systems with Purolite nuclear-grade resins.
- Specialized Membrane and Point-of-Use Filtration Producers: DuPont de Nemours Inc., Danaher Corporation, and Pentair plc manufacture FilmTec Prime RO membranes and Pall Microza hollow-fiber UF modules as well as X-Flow pretreatment membranes.
Competitive Benchmarking: Ultrapure Water Market
Table 8: Competitive Benchmarking for the Ultrapure Water Market (qualitative capability ratings), 2026
| Company | Sub-2nm Semiconductor UPW Track Record | Proprietary Membrane & Resin IP | Build-Own-Operate & Service Reach | Geographic Reach |
|---|---|---|---|---|
| Kurita Water Industries Ltd. | High | High | High | Japan, Taiwan, Korea, US, Europe, and new Kurita Membrane India JV in June 2026 |
| Organo Corporation | High | High | High | Japan, Taiwan, US Arizona, and Germany; primary UPW EPC partner for leading foundries |
| Veolia Water Technologies | High | High | High | Global GreenUp network; opened Singapore semiconductor UPW laboratory in mid-2026 |
| Xylem Inc. | High | High | High | Global footprint; integrated Evoqua Ionpure CEDI and Vantage UPW with USD 3.09B Q2 2026 orders |
| Ecolab Inc. | High | High | High | Global network; closed USD 1.8B acquisition of Ovivo Electronics UPW in Dec 2025 plus Purolite resins |
| Nomura Micro Science Co. Ltd. | High | Medium | High | Japan, South Korea, Taiwan, US, and China turnkey UPW engineering for memory and foundry fabs |
| DuPont de Nemours Inc. | High | High | Medium | Global FilmTec Prime RO membranes, AmberTec UPW mixed-bed resins, and IntegraTec UF modules |
| Danaher Corporation | High | High | Medium | Global Pall Microelectronics Microza hollow-fiber UF and sub-10nm point-of-use UPW filters |
| Pentair plc | Medium | High | Medium | Global X-Flow capillary UF pretreatment membranes maintaining <0.3 ppb colloidal silica |
Key Developments in the Ultrapure Water Market
- In December 2025, Ecolab Inc. completed its acquisition of Ovivo’s electronics business, a global provider of ultrapure water technologies for semiconductor manufacturing, for total cash consideration of USD 1.596 billion. The acquired business became part of Ecolab’s Global Water segment and continues to operate under the brand Ovivo, Ultrapure Water+ by Ecolab, expanding Ecolab’s end-to-end ultrapure water and water circularity capabilities for advanced chip fabrication customers [25].
- In June 2026, Kurita Water Industries Ltd. established Kurita Membrane India Private Limited, a joint venture with Membrane Group India Private Limited, to design, manufacture, install, and maintain ultrapure water production and wastewater recycling systems for India’s growing semiconductor and electronics sector. Kurita Water Industries Ltd. holds a 51.0% stake in the venture, with Membrane Group India Private Limited holding the remaining 49.0% [26].
Key Players in the Ultrapure Water Market
Turnkey Semiconductor and Industrial UPW Engineering Leaders
- Kurita Water Industries Ltd.
- Organo Corporation
- Nomura Micro Science Co. Ltd.
Global Integrated Water Technology and Service Platforms
- Veolia Water Technologies
- Xylem Inc.
- Ecolab Inc.
- Specialized Membrane, Resin, and Point-of-Use Filtration Producers
DuPont de Nemours Inc.
- Danaher Corporation
- Pentair plc
Ultrapure Water Market - Report Scope
Table 9: Report Scope for the Ultrapure Water Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Equipment and Process; End-Use Industry; Application; System Delivery Mode; Purity Grade |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial supplier revenue from turnkey ultrapure water generation and polishing plants, modular RO/EDI/UF/UV skids, build-own-operate UPW utility contracts, and aftermarket replacement membranes, nuclear-grade ion-exchange resins, and point-of-use filters achieving >=18.0 MOhm-cm resistivity or Pharmacopeia WFI purity. Category Scope Note: Excludes municipal potable water treatment, general industrial cooling water chemicals, and unpolished bulk wastewater clarifiers. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Mexico, South Korea, USA, China, Japan, Australia, Italy, Germany, and additional countries in the full report |
| Key Companies Covered | Kurita Water Industries Ltd., Organo Corporation, Veolia Water Technologies, Xylem Inc., Ecolab Inc., Nomura Micro Science Co. Ltd., DuPont de Nemours Inc., Danaher Corporation, Pentair plc |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Ultrapure Water Market - Research Methodology
Table 10: Research Methodology for the Ultrapure Water Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with 300-mm semiconductor fab utility directors, UPW process design engineers, membrane polymer scientists, and pharmaceutical WFI quality managers to validate cubic-meter-per-day capex and consumable replacement rates. |
| Secondary Research | Analysis of NIST CHIPS for America Environmental Impact Statements, SEMI 300-mm fab equipment filings, SIA industry reports, European Commission Water Resilience Strategy dockets, METI Japan and ABS Australia statistics, and corporate filings. |
| Market Sizing and Forecasting | Top-down global industrial and semiconductor water treatment baselines reconciled against bottom-up installed and greenfield UPW production capacity (10.1M to 11.0M m3/day in 2026) and recurring consumable spend from 2026 to 2036. |
| Country Forecasting Model | Econometric national models weight announced 300-mm wafer fab capex, electronics OSAT nearshoring, biopharmaceutical WFI loop installations, and mandatory fab water reclamation rates across eight countries. |
| Operational Benchmark Traceability | Fab water consumption and purification indicators in Tables 2, 3, and 4 trace to SEMI ERMR basin studies, ACS ES&T Letters CMP water balances, U.S. DOE FEMP reverse osmosis benchmarks, and European Commission dockets. |
| Data Triangulation and Validation | Revenue estimates isolate high-purity demineralization, TOC oxidation, sub-micron polishing, and direct UPW loop reclamation while strictly excluding raw municipal intake piping and general sewage treatment. |
Ultrapure Water Market by Segments
Ultrapure Water Market segmented by Equipment and Process:
- Reverse Osmosis RO Filtration
- Electrodeionization EDI Modules
- Ion Exchange Resins Polishing Beds
- Ultrafiltration UF and Microfiltration
- Ultraviolet UV TOC Reduction Lamps
Ultrapure Water Market segmented by End-Use Industry:
- Semiconductor and Microelectronics Wafer Fabs
- Pharmaceutical and Biomanufacturing WFI Injectables
- Power Generation Supercritical Boilers
- Flat Panel Display and Photovoltaic Solar Cell Fabs
Ultrapure Water Market segmented by Application:
- Semiconductor Silicon Wafer Washing and Wet Chemical Rinsing
- Pharmaceutical Formulation and Biotechnology Fermentation Media
- Steam Boiler Turbine Feedwater
- Precision Optics and Photolithography Immersion Cleaning
Ultrapure Water Market segmented by System Delivery Mode:
- Aftermarket Consumables and Membrane Replacement
- Turnkey Design-Build-Operate Plants
- Modular Skids and Package Units
- Build-Own-Operate On-Site Water Services
Ultrapure Water Market segmented by Purity Grade:
- Type E-1 Sub-2 nm Semiconductor Grade UPW
- Pharmacopeia Water for Injection WFI Grade UPW
- High-Pressure Supercritical Boiler Grade UPW
- Analytical and Laboratory Reagent Grade UPW
Ultrapure Water Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Semiconductor Equipment and Materials International. (2026, July 1). SEMI Letter on Demand-Driven Memory Chip Supply and 300mm Fab Equipment Spending. SEMI Public Policy Dockets.
- [2] Ecolab Inc. (2025, December 16). Ecolab Closes Acquisition of Ovivo's Electronics Ultrapure Water Business. Ecolab Investor Relations.
- [3] Venkataswamy, R., Ramu, M., & Seo, J. (2025, August 7). Toward Eco-Friendly CMP Process: Emerging Trends and Strategies for Reducing Environmental Footprint. Environmental Science & Technology Letters, 12(9), 1139-1153.
- [4] SEMI Environmental Risk Mitigation Working Group. (2025, September 18). Ripple Effects: Water Risk and Resilience Across the Semiconductor Value Chain. Semiconductor Equipment and Materials International.
- [5] U.S. Department of Energy. (2026, February 14). Best Management Practice #14: Alternative Water Sources and Reverse Osmosis Efficiency. Federal Energy Management Program.
- [6] Oh, C., Kim, D., & Kim, S. (2026, March 12). Differential Behavior of Salt and Organic Matter Passage in 2-Pass RO Systems for Ultrapure Water Production. Separations, 13(3), 93.
- [7] Semiconductor Industry Association. (2025, July 7). 2025 State of the U.S. Semiconductor Industry Report. Semiconductor Industry Association Publications.
- [8] Wu, Y., Cui, K., Xie, X., Wang, J., & Zhang, Y. (2026, August 11). Recovery of Fluoride as Cryolite from Acidic Semiconductor Waste Liquor: Crystallization Behavior and Continuous-Flow Evaluation. Water, 18(16), 1960.
- [9] Toray Industries, Inc. (2026, June 3). Toray to Launch Next-Generation Reverse Osmosis Membranes Offering Industry-Leading Salt Rejection for Desalination and Ultrapure Water Production. Toray Corporate Newsroom.
- [10] Lee, J. A., Park, J., Lee, S., Son, K., & Lee, S. (2026, February 6). Analysis of Contaminant Behavior in Loop Pipe System for Ultrapure Water Distribution Using Computational Fluid Dynamics and Autopsy. Water, 18(3), 429.
- [11] U.S. National Institute of Standards and Technology. (2026, January 15). Record of Decision: Final Environmental Impact Statement for the Micron Semiconductor Manufacturing Project, Clay, New York. U.S. Department of Commerce CHIPS Program Office.
- [12] Sandhu, S., Zumeit, A., Tian, Z., Vinciguerra, V., & Dahiya, R. (2025, September 15). Semiconductor manufacturing wastewater challenges and the potential solutions via printed electronics. iScience, 28(10), 113576 (PMC12510042).
- [13] Kurita Water Industries Ltd. (2025, October 30). Orders for e-WT, an Off-the-line Ultrapure Water Supply System to Begin for the Electronics Industry with an Ultra-short Delivery Time. Kurita Corporate Newsroom.
- [14] Hernández Miraflores, A., & Morales, R. (2025, April 7). Ultrapure Water Production by a Saline Industrial Effluent Treatment. Membranes, 15(4), 116.
- [15] Ministry of Economy and Finance, Republic of Korea. (2024, November 28). KRW 14 Trillion Policy Financing and Yongin Semiconductor Mega-Cluster Water and Power Infrastructure Agreement. Government of the Republic of Korea Policy Portal.
- [16] U.S. National Institute of Standards and Technology. (2026, July 16). Trump Administration Secures an Additional $100 Billion U.S. Semiconductor Manufacturing Investment for a Total of $265 Billion from TSMC. U.S. Department of Commerce.
- [17] Veolia Environnement S.A. (2026, June 18). Strategic Program 2027 GreenUp: Semiconductor Ultrapure Water Laboratory and Innovation for Environmental Security. Veolia Group Strategy Publications.
- [18] Ministry of Economy, Trade and Industry, Japan. (2026, April 3). Press Conference by Minister Akazawa on Manufacture of Advanced 3-Nanometer Semiconductors at TSMC Second Plant in Kumamoto. METI Official Releases.
- [19] Australian Bureau of Statistics. (2025, December 11). Water Account, Australia, 2023-24 Financial Year. Commonwealth of Australia Statistical Releases.
- [20] Kurita Water Industries Ltd. (2025, July 8). Achieved a Development Milestone to PFAS-free Ultrapure Water Piping for Cutting-edge Semiconductor Manufacturing. Kurita Corporate Newsroom.
- [21] European Commission & Water Europe. (2025, March 18). EU Water Resilience Strategy Position Paper: Ultrapure Water Investment Requirements in European Semiconductor Manufacturing. European Commission Better Regulation Portal.
- [22] Xylem Inc. (2026, July 28). Xylem Reports Second Quarter 2026 Results with Record Water Solutions and Services Orders. Xylem Corporate Newsroom.
- [23] Kurita Water Industries Ltd. (2026, June 30). Kurita and Membrane Group India Establish Kurita Membrane India Pvt. Ltd. to Cater to the Semiconductor Industry. Kurita Corporate Newsroom.
- [24] U.S. National Institute of Standards and Technology. (2025, November 15). CHIPS for America: TSMC Arizona Project Statistics and Advanced Node Fabrication. U.S. Department of Commerce.
- [25] Ecolab Inc. (2026). Annual Report on Form 10-K for fiscal year ended December 31, 2025. U.S. Securities and Exchange Commission. https://www.sec.gov/Archives/edgar/data/31462/000110465926018357/ecl-20251231x10k.htm
- [26] Kurita Water Industries Ltd. (2026, June 30). Kurita and Membrane Group India Establish Kurita Membrane India Pvt. Ltd. for Semiconductor Industry in India. https://www.kurita-water.com/en/news/20260630-01/
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the ultrapure water market in 2026 and what is forecast for 2036?
- Which 300-mm semiconductor wafer fab and sub-2-nm purity pressures support demand for ultrapure water?
- Why does Reverse Osmosis RO Filtration lead the equipment and process category?
- Why do Semiconductor and Microelectronics Wafer Fabs lead the end-use industry category?
- How do growth rates differ across Mexico, South Korea, and the USA?
- Which leading companies engineer turnkey UPW plants versus manufacturing membranes and polishing resins?
- What watershed scarcity and PFAS effluent compliance hurdles restrain new fab water permits?
- What should fab utility directors evaluate when selecting modular UPW skids and PVDF vs olefin piping?
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Equipment and Process, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Equipment and Process, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Equipment and Process, 2026 to 2036
- Reverse Osmosis RO Filtration
- Electrodeionization EDI Modules
- Ion Exchange Resins Polishing Beds
- Ultrafiltration UF and Microfiltration
- Ultraviolet UV TOC Reduction Lamps
- Y-o-Y Growth Trend Analysis By Equipment and Process, 2021 to 2025
- Absolute $ Opportunity Analysis By Equipment and Process, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use Industry, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use Industry, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use Industry, 2026 to 2036
- Semiconductor and Microelectronics Wafer Fabs
- Pharmaceutical and Biomanufacturing WFI Injectables
- Power Generation Supercritical Boilers
- Flat Panel Display and Photovoltaic Solar Cell Fabs
- Y-o-Y Growth Trend Analysis By End-Use Industry, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use Industry, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Semiconductor Silicon Wafer Washing and Wet Chemical Rinsing
- Pharmaceutical Formulation and Biotechnology Fermentation Media
- Steam Boiler Turbine Feedwater
- Precision Optics and Photolithography Immersion Cleaning
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By System Delivery Mode, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By System Delivery Mode, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By System Delivery Mode, 2026 to 2036
- Aftermarket Consumables and Membrane Replacement
- Turnkey Design-Build-Operate Plants
- Modular Skids and Package Units
- Build-Own-Operate On-Site Water Services
- Y-o-Y Growth Trend Analysis By System Delivery Mode, 2021 to 2025
- Absolute $ Opportunity Analysis By System Delivery Mode, 2026 to 2036
- Global Market Analysis and Forecast, By Purity Grade, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Purity Grade, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Purity Grade, 2026 to 2036
- Type E-1 Sub-2 nm Semiconductor Grade UPW
- Pharmacopeia Water for Injection WFI Grade UPW
- High-Pressure Supercritical Boiler Grade UPW
- Analytical and Laboratory Reagent Grade UPW
- Y-o-Y Growth Trend Analysis By Purity Grade, 2021 to 2025
- Absolute $ Opportunity Analysis By Purity Grade, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- By Country
- Market Attractiveness Analysis
- By Country
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- By Country
- Market Attractiveness Analysis
- By Country
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- By Country
- Market Attractiveness Analysis
- By Country
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- By Country
- Market Attractiveness Analysis
- By Country
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- By Country
- Market Attractiveness Analysis
- By Country
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- By Country
- Market Attractiveness Analysis
- By Country
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- By Country
- Market Attractiveness Analysis
- By Country
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Equipment and Process
- By End-Use Industry
- By Application
- By System Delivery Mode
- By Purity Grade
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Kurita Water Industries Ltd.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Organo Corporation
- Veolia Water Technologies
- Xylem Inc.
- Ecolab Inc.
- Nomura Micro Science Co. Ltd.
- DuPont de Nemours Inc.
- Danaher Corporation
- Pentair plc
- Specialized Membrane, Resin, and Point-of-Use Filtration Producers
- Kurita Water Industries Ltd.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Equipment and Process, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by System Delivery Mode, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Purity Grade, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Equipment and Process, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by System Delivery Mode, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Purity Grade, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Equipment and Process, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by System Delivery Mode, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Purity Grade, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Equipment and Process, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by System Delivery Mode, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Purity Grade, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Equipment and Process, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by System Delivery Mode, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Purity Grade, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Equipment and Process, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by System Delivery Mode, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Purity Grade, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Equipment and Process, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by System Delivery Mode, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Purity Grade, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Equipment and Process, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by End-Use Industry, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by System Delivery Mode, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Purity Grade, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Equipment and Process, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Equipment and Process, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Equipment and Process
- Figure 6: Global Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by End-Use Industry
- Figure 9: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Application
- Figure 12: Global Market Value Share and BPS Analysis by System Delivery Mode, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by System Delivery Mode, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by System Delivery Mode
- Figure 15: Global Market Value Share and BPS Analysis by Purity Grade, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Purity Grade, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Purity Grade
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Equipment and Process, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Equipment and Process, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Equipment and Process
- Figure 32: North America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by End-Use Industry
- Figure 35: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Application
- Figure 38: North America Market Value Share and BPS Analysis by System Delivery Mode, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by System Delivery Mode, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by System Delivery Mode
- Figure 41: North America Market Value Share and BPS Analysis by Purity Grade, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Purity Grade, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Purity Grade
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Equipment and Process, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Equipment and Process, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Equipment and Process
- Figure 48: Latin America Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by End-Use Industry
- Figure 51: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Application
- Figure 54: Latin America Market Value Share and BPS Analysis by System Delivery Mode, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by System Delivery Mode, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by System Delivery Mode
- Figure 57: Latin America Market Value Share and BPS Analysis by Purity Grade, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Purity Grade, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Purity Grade
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Equipment and Process, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Equipment and Process, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Equipment and Process
- Figure 64: Western Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by End-Use Industry
- Figure 67: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Application
- Figure 70: Western Europe Market Value Share and BPS Analysis by System Delivery Mode, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by System Delivery Mode, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by System Delivery Mode
- Figure 73: Western Europe Market Value Share and BPS Analysis by Purity Grade, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Purity Grade, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Purity Grade
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Equipment and Process, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Equipment and Process, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Equipment and Process
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by End-Use Industry
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Application
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by System Delivery Mode, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by System Delivery Mode, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by System Delivery Mode
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Purity Grade, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Purity Grade, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Purity Grade
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Equipment and Process, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Equipment and Process, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Equipment and Process
- Figure 96: East Asia Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by End-Use Industry
- Figure 99: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Application
- Figure 102: East Asia Market Value Share and BPS Analysis by System Delivery Mode, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by System Delivery Mode, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by System Delivery Mode
- Figure 105: East Asia Market Value Share and BPS Analysis by Purity Grade, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Purity Grade, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Purity Grade
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Equipment and Process, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Equipment and Process, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Equipment and Process
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by End-Use Industry
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by System Delivery Mode, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by System Delivery Mode, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by System Delivery Mode
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Purity Grade, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Purity Grade, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Purity Grade
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Equipment and Process, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Equipment and Process, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Equipment and Process
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by End-Use Industry, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by End-Use Industry, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by End-Use Industry
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by System Delivery Mode, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by System Delivery Mode, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by System Delivery Mode
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Purity Grade, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Purity Grade, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Purity Grade
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the Ultrapure Water Market in 2026, and what is forecast for 2036?
Global ultrapure water demand stood at USD 9.2 billion in 2025 and reaches an estimated USD 9.9 billion in 2026, advancing toward USD 20.6 billion by 2036.
What is the CAGR for the Ultrapure Water Market from 2026 to 2036?
The ultrapure water sector is projected to expand at a 7.6% CAGR over the 2026 to 2036 window, adding USD 10.7 billion in incremental revenue across semiconductor and biopharma plants.
Which equipment and process segment leads the Ultrapure Water Market?
Reverse Osmosis RO Filtration holds an estimated 44.0% of equipment and process demand in 2026 since two-pass polyamide membranes strip over 99% of bulk ions and organics ahead of polishing loops.
Which end-use industry segment leads the Ultrapure Water Market?
Semiconductor and Microelectronics Wafer Fabs represent an estimated 58.0% of the end-use industry category in 2026 as 300-mm cleanrooms consume thousands of cubic meters daily for wet rinsing and planarization.
Which country has a notable growth outlook during the assessment period?
Mexico leads national expansion projections at an 8.8% CAGR through 2036, driven by electronics assembly nearshoring and industrial saline effluent RO-EDI reclamation projects.
Who are the key players in the market?
Kurita Water Industries Ltd. and Organo Corporation lead global turnkey supply with Veolia Water Technologies, Xylem Inc., and Ecolab Inc. Ovivo Inc. and Nomura Micro Science also compete with DuPont, Danaher, and Pentair.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
