

- Market Size (2026)
- USD 1.7 Bn
- Forecast (2036)
- USD 3.2 Bn
- CAGR (2026 to 2036)
- 6.6%
How big is Texturized Vegetable Protein Market in 2026?
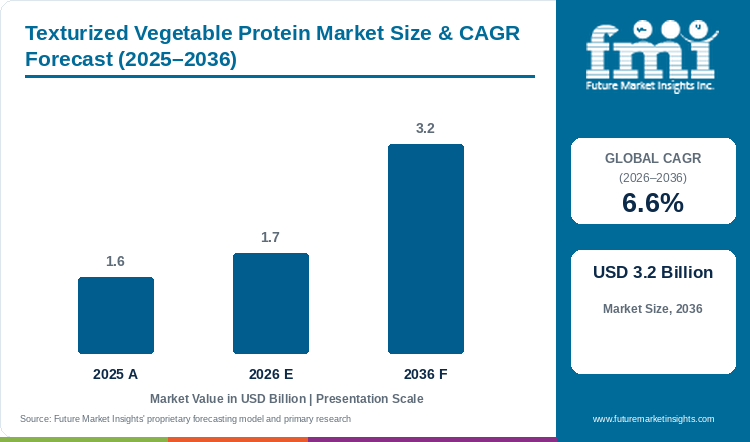
Demand for texturized vegetable protein is projected to expand at 6.6% CAGR between 2026 and 2036. Industry value grows from USD 1.6 billion in 2025 to USD 1.7 billion in 2026 and is projected to reach USD 3.2 billion by 2036.
Increasing consumption of protein-based food products is boosting the demand for texturized vegetable protein across the globe. Protein is no longer limited to dinner products and is increasingly used in snacks, bars, prepared foods and blended recipes. According to Cargill, in April 2025, 61% of surveyed U.S. consumers increased their protein intake during 2024[1]. This increasing preference is creating demand for ingredients that provide protein along with bite and structure. Soy remains highly used due to abundant crop supply and established extrusion facilities. FMI notes that apart from soy, pea protein, wheat and faba bean proteins are also gaining demand among manufacturers looking for different taste, allergen and sourcing options.
Regional demand is changing across markets, which are shaped by variations in food habits, processing capacity and consumer acceptance. Germany is projected to grow at 8.4% CAGR through 2036, while the UK is anticipated to expand at 8.0% CAGR. In July 2025, ADM reported stronger flexitarian participation in Germany[2]. Presence of an established meat substitute industry is supporting ingredient trials in the country. In the UK, manufacturers are focusing on taste, price, safety and clear identity of alternative protein products. However, technical and regulatory issues can slow down the commercialization.
Key Takeaways of Texturized Vegetable Protein Market
- Demand is rising in applications where textures add bite and structure on existing or modestly adapted food-processing lines.
- Based on product type, soy protein is projected to account for 69.6% in 2026, supported by feedstock scale and extrusion familiarity.
- By form, granules are estimated to hold 35.3% in 2026, owing to even hydration in ground and reformed products.
- In 2026, dry TVP is expected to lead process type with 91.2% share, driven by ambient handling and processor-set moisture.
- Germany is projected at 8.4% CAGR through 2036, whereas the UK is forecast at 8.0% as buying conditions differ.
- Notable companies include Cargill, ADM, Roquette, IFF, Fuji Oil, MGP Ingredients, Ingredion, dsm-firmenich, Scoular, and BENEO.
Analyst Perspective
“Consistent texture after hydration and cooking is one of the major factors that will decide the adoption of texturized vegetable protein. In my experience, availability of different protein sources will also support processors when the same can be used without creating production issues.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the Texturized Vegetable Protein Market segmented?
Texturized vegetable protein market is segmented by six primary commercial axes and region: product type, form, process type, end-use, nature, and distribution channel. Soy protein is projected at 69.6%, granules at 35.3%, and dry TVP at 91.2% in 2026.
Product type covers soy protein, pea protein, wheat protein, rice protein, faba bean protein, lentil protein, flax protein, and chia protein.
Form covers granules, chunks, flakes, and slices.
Process type covers dry TVP and wet TVP.
End-use covers meat analogues, animal feed and pet food, household, bakery, ready meals, snacks, commercial, sports nutrition, clinical nutrition, baby food, and others.
Nature covers conventional and organic.
Distribution channel covers direct, hypermarkets and supermarkets, convenience stores, online retail, traditional grocery retailers, and food and drink speciality.
Why does soy protein retain notable product type demand?
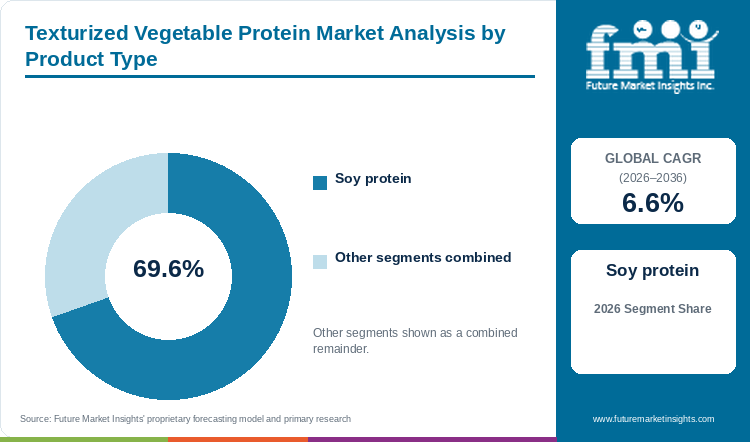
Based on product type, soy protein is projected to account for 69.6% in 2026, supported by feedstock scale and extrusion familiarity.
Soy protein is widely used in texturized vegetable protein owing to its easy availability and established processing methods. However, manufacturers also check flavor, color, hydration and source identity before selecting a grade.
- Soy protein is projected at 69.6% in 2026 because processors can retain established extrusion settings.
- According to USDA, U.S. soybean production was estimated at 4.26 billion bushels in 2025 and the crop recorded an average yield of 53.0 bushels per acre[3]. This large agricultural base supports continuous availability of soy ingredients for industrial production.
What supports granules as a preferred form for processors?
By form, granules are estimated to hold 35.3% in 2026, owing to quick hydration and fit with minced applications.
Granules are increasingly used in ground and reformed food products as they easily get mixed and hydrated in the formulation. They provide controlled particle size and do not require aligned whole-muscle fibers.
- Granules are estimated at 35.3% in 2026 because small particles hydrate evenly during mixing.
- In July 2025, Ingredion showcased plant-based and protein-enhanced food applications at IFT FIRST, connecting texture development with products manufactured on familiar mixing and forming equipment[4]. This allows processors to develop structured food products without installing a separate high-moisture extrusion line.
How does dry TVP meet changing process requirements?
In 2026, dry TVP is expected to lead process type with 91.2% share, driven by ambient storage and controlled rehydration.
Dry TVP is easy to store and gives manufacturers the flexibility to add moisture during the final food processing. Although processors need an additional hydration step, dry TVP reduces storage issues and provides better control over final moisture. Due to these advantages, dry TVP is anticipated to account for 91.2% share in 2026.
- Dry TVP is expected to hold majority share in 2026 as plants can control water uptake.
- In June 2025, Roquette added NUTRALYS textured wheat and pea proteins to its portfolio, including fibrous and larger-piece formats[5]. The development has widened the availability of dry texturized proteins beyond soy.
Why do meat analogues account for notable end-use demand?
By end-use, meat analogues are forecast to represent 29.8% in 2026, attributable to their direct need for bite and structure.
Meat analogues require texturized vegetable protein for producing bite, chew and structure similar to conventional meat products. The ingredient also helps in retaining water and prevents the product from collapsing during mixing, forming, heating and cooling.
- Increasing demand for plant-based meat products is expected to support meat analogues, which are forecast to account for 29.8% share in 2026.
- In January 2025, the U.S. FDA issued draft guidance for naming plant-based alternatives to animal-derived foods[6]. This has increased the importance of clear plant-source identity along with texture performance.
Which conditions keep conventional material relevant by nature?
Conventional material is likely to capture 97.8% share in 2026, influenced by wider feedstock access and simpler chain requirements.
Conventional texturized vegetable protein is available through wider commodity and identity-preserved supply chains. In May 2025, BENEO reported that 81% of surveyed consumers showed interest in protein[7]. This increasing interest supports the use of plant protein ingredients in several food applications.
- Conventional material is likely to hold 97.8% in 2026 because buyers need broad feedstock access.
- Organic products require certified farms, separate handling and complete records throughout the supply chain, which increases sourcing complexity and cost. Therefore, high-volume manufacturers are likely to continue using conventional material unless the organic claim provides enough value.
How does direct purchasing support distribution channel demand?
Direct is set to lead the distribution channel with 86.6% share in 2026, reinforced by sample testing and technical qualification.
Direct purchasing is preferred by industrial buyers as texturized vegetable protein needs sample testing and technical approval before regular use. Manufacturers check hydration, particle strength, cooking response, labeling and batch consistency before changing an existing ingredient. In June 2025, the UK Government Chemist reported that technical and regulatory questions were still affecting alternative protein commercialization[8].
- Direct is set to hold 86.6% in 2026 because qualification favors supplier-to-processor contact.
- Direct contact with suppliers supports trials, corrective work and documentation. Distributors are generally used by smaller buyers with standard requirements.
What are the drivers, restraints, and opportunities in the Texturized Vegetable Protein Market?
In the texturized vegetable protein market, the key driver is scalable texture, the key restraint is qualification risk, and the key opportunity is source diversification.
- Driver: Food manufacturers need plant protein that adds structure on existing mixing, forming, and cooking lines.
- Restraint: Flavor, bite, origin, labeling, and batch consistency can extend industrial qualification before routine purchasing.
- Opportunity: Pea, wheat, faba bean, and blended texturates widen sourcing when process behavior matches established grades.
Existing Lines Support Texture Adoption
Increasing demand for plant protein ingredients that can be used on existing food processing lines is driving the texturized vegetable protein market. In April 2025, Cargill reported that 63% of surveyed consumers looked for protein in snacks[9]. This has increased the requirement for particles and fibers that hold their shape during hydration and cooking. Texturized vegetable protein can be used in plant-based snacks and prepared foods without changing the complete production layout. Easy adoption on mixing, forming and cooking equipment is expected to boost the market during the forecast period.
Qualification Controls Extend Approval Work
The approval of texturized vegetable protein is a time-consuming process as a successful laboratory sample may not perform in the same way during large-scale production. These qualification requirements can restrict quick adoption of new grades.
Source Diversity Opens New Formulations
Increasing availability of non-soy texturized proteins is creating growth opportunities for manufacturers. Pea, wheat and fava bean proteins can be used where soy labeling, flavor or sourcing does not meet the product requirement. In July 2025, ADM reported that 46% of surveyed consumers identified as flexitarian globally[11]. This preference is supporting blended food products that retain familiar taste and eating formats while changing the protein mix. However, alternative sources need to provide similar processing stability before replacing soy in regular production.
Which country CAGRs are profiled in the Texturized Vegetable Protein Market?
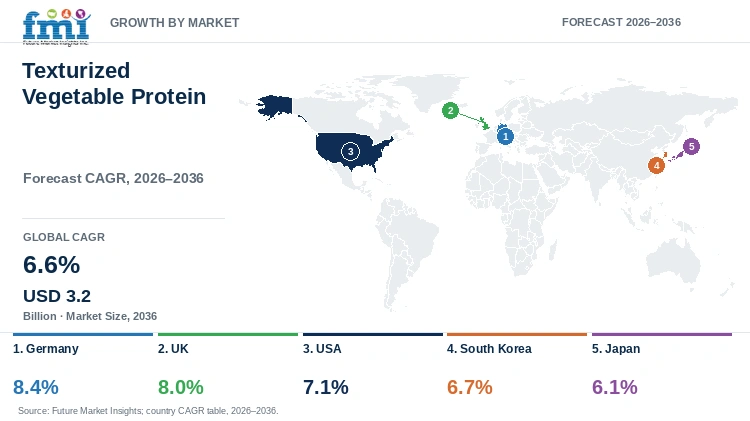
| Country | CAGR |
|---|---|
| Germany | 8.4% |
| UK | 8.0% |
| USA | 7.1% |
| South Korea | 6.7% |
| Japan | 6.1% |
How do country-level CAGRs compare in the texturized vegetable protein market?
The growth of texturized vegetable protein market is expected to follow different routes across the profiled countries. Germany has an established meat substitute manufacturing base, while the UK is witnessing continued development in alternative proteins. The U.S. benefits from large soybean production and food processing capacity. South Korea is supported by prepared food exports, whereas Japan has a long familiarity with soy foods and growing food-technology activities.
- Germany combines established meat-substitute manufacturing with expanding flexitarian consumer demand and texture improvement.
- UK alternative-protein processors operate within food-security and affordability conditions using dry and granule formats.
- USA draws large soy-texturate availability from a broad agricultural and processing base for domestic food manufacturing.
- South Korea connects export-oriented prepared food trade with dry TVP moisture control and localized formulation.
- Japan uses established soy-food familiarity and public-private food-tech initiatives for structured plant protein development.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Country-wise Analysis
- Germany’s texturized vegetable protein outlook is anticipated to advance at 8.4% CAGR over the assessment period, supported by established meat-substitute production. Destatis reported in May 2026 that Germany produced 124,900 tonnes of meat substitutes during 2025, and while output fell 1.2% from 2024, production remained 107% above 2019[12]. This is a mature manufacturing base rather than an early trial category. Food makers now need better price control and eating quality while keeping output stable. TVP grades that control hydration and cooking texture can support that work. German demand should therefore favor measurable process improvement instead of novelty alone.
- Texturized vegetable protein demand in the UK is forecast to rise at 8.0% CAGR over the forecast period, influenced by active alternative-protein development. The United Kingdom Food Security Digest was published in December 2025 with updated evidence on domestic production, imports, and supply resilience[13]. Alternative-protein processors operate inside that wider food-security and affordability setting. Granules and dry formats can enter existing plants with limited equipment changes. Buyers still compare taste, cost, safety, and labeling before approving recipes. UK expansion therefore depends on practical eating quality and production control rather than consumer awareness alone.
- Adoption of texturized vegetable protein in the USA is estimated to expand at 7.1% CAGR through 2036, owing to large soybean supply. USDA reported that U.S. soybean exports reached USD 16.2 billion during 2025[14]. A broad agricultural and processing base supports soy-texturate availability for domestic food manufacturing. Source scale does not remove grade-level qualification inside the food plant. U.S. processors still review hydration, allergens, source identity, and label wording together. The local opportunity remains strongest where suppliers connect dependable feedstock with repeatable cooking performance and complete records.
- South Korea is estimated to post 6.7% CAGR over the forecast period, aided by processed-food trade and food-industry investment. MAFRA reported in January 2026 that K-Food Plus exports reached USD 13.62 billion during 2025, while prepared-food exports reached USD 744.8 million, up 9.5% from the previous year[15]. Export-oriented recipes need texture that remains stable after storage, distribution, and reheating. Dry TVP fits that route because processors set moisture during production. Korean demand should widen where suppliers provide localized flavor and clear source documentation.
- Texturized vegetable protein sales in Japan are forecast to expand at 6.1% CAGR by 2036, supported by established soy-food familiarity. A March 2026 MAFF presentation stated that the Food Tech Public-Private Council included about 1,700 participants, with activities covering a plant-based working team and development of sprouted-soy materials for improved flavor and texture[16]. Familiarity with soy gives formulators a practical starting point for new structured foods. Growth remains measured because products must match local eating expectations and labeling practices. Precise particle, hydration, and source information can support that development route.
Who are the notable companies in the Texturized Vegetable Protein Market?
Notable companies include Cargill, Incorporated; Archer Daniels Midland Company; Roquette Freres; International Flavors & Fragrances Inc.; Fuji Oil Co., Ltd.; MGP Ingredients, Inc.; Ingredion Incorporated; dsm-firmenich; The Scoular Company; and BENEO GmbH.
The texturized vegetable protein market consists of global ingredient companies, protein source specialists and sourcing partners. Global companies are strengthening feedstock supply, extrusion capacity and application support, while specialists are focusing on selected protein sources and texture systems. Sourcing partners support manufacturers in managing origin, substitute grades and trial quantities. Buyers generally compare hydration, cooking response, flavor, source records and production consistency before adopting a product. At present, publicly available information does not establish one company as the verified market share leader.
- Diversified extrusion platforms: ADM, Roquette, Ingredion, Cargill, and dsm-firmenich provide multi-source application support.
- Source and texture specialists: IFF, Fuji Oil, MGP Ingredients, and BENEO supply focused texturates.
- Sourcing and formulation network: The Scoular Company links ingredient sourcing with formulation and customer trial support.
Competitive Benchmarking: Texturized Vegetable Protein Market
| Company | Source breadth | Application support | Non-soy options | Geographic reach |
|---|---|---|---|---|
| Cargill, Incorporated | Medium | High | High | High |
| Archer Daniels Midland Company | High | High | High | High |
| Roquette Freres | High | High | High | High |
| International Flavors & Fragrances Inc. | Medium | Medium | Low | High |
| Fuji Oil Co., Ltd. | Medium | High | Low | Medium |
| MGP Ingredients, Inc. | Medium | Medium | High | Medium |
| Ingredion Incorporated | Medium | High | Medium | High |
| dsm-firmenich | Medium | High | High | High |
| The Scoular Company | Medium | High | Medium | Medium |
| BENEO GmbH | High | High | High | High |
The above comparison is based on available evidence for source range, application support, non-soy products and geographic presence. High indicates broad documented capability, Medium indicates limited or selected capability and Low indicates less public evidence. The ratings do not represent product quality, revenue share or company ranking.
Key Developments in the Texturized Vegetable Protein Market
- In June 2025, IFF expanded the distribution reach of its SUPRO TEX dry textured proteins and SUPRO MAX structured vegetable proteins in the UK and Ireland through a long-term supply agreement with ACI Group, connecting its soy and pea texturate range with regional meat-alternative and prepared-food manufacturers.
- In January 2026, Ingredion updated the specification of VITESSENCE TEX Crumbles 1651, confirming the textured pea protein contains 65% protein and provides a shelf life of 24 months under stated storage conditions[18].
- In May 2026, BENEO highlighted hybrid meat products for flexitarian consumers looking for familiar taste and texture. This is expected to create new application opportunities for texturized vegetable proteins.
- In April 2026, dsm-firmenich introduced next-generation Vertis pea TVP formulations featuring integrated ModulaSENSE technology to address pea off-notes during processing.
Key Players in the Texturized Vegetable Protein Market
Diversified Extrusion and Texturization Platforms
- Cargill, Incorporated
- Archer Daniels Midland Company
- Roquette Freres
- Ingredion Incorporated
- dsm-firmenich
Source-Specialist Texturized Protein Portfolios
- International Flavors & Fragrances Inc.
- Fuji Oil Co., Ltd.
- MGP Ingredients, Inc.
- BENEO GmbH
Sourcing and Formulation Support Network
- The Scoular Company
Texturized Vegetable Protein Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; form; process type; end-use; nature; distribution channel; region. |
| Quantitative units | USD billion. |
| Market definition | Revenue from texturized vegetable protein ingredients. Finished foods and non-texturized protein products are excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa. |
| Countries covered | Germany; UK; USA; South Korea; Japan. |
| Key companies profiled | Cargill, Incorporated; Archer Daniels Midland Company; Roquette Freres; International Flavors & Fragrances Inc.; Fuji Oil Co., Ltd.; MGP Ingredients, Inc.; Ingredion Incorporated; dsm-firmenich; The Scoular Company; BENEO GmbH. |
| Forecast period | 2026 to 2036. |
| Approach | The Future Market Insights report covers market value, segment structure, country outlook, company activity, and buyer qualification conditions. |
Texturized Vegetable Protein Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical support. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for date, geography, relevance, and consistency with the defined scope. |
| Market Sizing and Forecasting | The market model combined baseline value, historical performance, segment structure, pricing, volume indicators, adoption levels, company participation, and country demand. Forecast assumptions considered economic activity, regulation, technology adoption, purchasing cycles, and supply availability. |
| Data Validation | Estimates were checked against public data, company activity, trade patterns, industry developments, and primary interviews. Adjacent categories, overlapping revenue, and activities outside the market boundary were excluded. |
The segment shares and forecast values are proprietary estimates of Future Market Insights. These values are not government statistics or directly measured global market shares.
Texturized Vegetable Protein Market by Segments
Texturized Vegetable Protein Market segmented by Product Type:
- Soy protein
- Pea protein
- Wheat protein
- Rice protein
- Faba bean protein
- Lentil protein
- Flax protein
- Chia protein
Texturized Vegetable Protein Market segmented by Form:
- Granules
- Chunks
- Flakes
- Slices
Texturized Vegetable Protein Market segmented by Process Type:
- Dry TVP
- Wet TVP
Texturized Vegetable Protein Market segmented by End-use:
- Meat analogues
- Animal feed and pet food
- Household
- Bakery
- Ready meals
- Snacks
- Commercial
- Sports nutrition
- Clinical nutrition
- Baby food
- Others
Texturized Vegetable Protein Market segmented by Nature:
- Conventional
- Organic
Texturized Vegetable Protein Market segmented by Distribution Channel:
- Direct
- Hypermarkets and supermarkets
- Convenience stores
- Online retail
- Traditional grocery retailers
- Food and drink speciality
Texturized Vegetable Protein Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Cargill, Incorporated. (2025, April 1). Consumers are seeking more protein for health and taste in 2025.
- [2] Archer Daniels Midland Company. (2025, July). The powerful trends that are shaping alternative protein innovation.
- [3] U.S. Department of Agriculture, National Agricultural Statistics Service. (2026, January 12). Crop Production 2025 Summary.
- [4] Ingredion Incorporated. (2025, July 22). Ingredion at IFT FIRST 2025: Connecting texture, health and innovation.
- [5] Roquette. (2025, June 17). NUTRALYS Portfolio: New textured wheat and pea proteins.
- [6] U.S. Food and Drug Administration. (2025, January). Draft Guidance for Industry: Labeling of Plant-Based Alternatives to Animal-Derived Foods.
- [7] BENEO. (2025, May 28). Global food and drink trends for 2025.
- [8] Government Chemist. (2025, June 16). Quantitative review of sustainable novel food production.
- [9] Cargill, Incorporated. (2025). The 2025 Protein Profile.
- [10] dsm-firmenich. (2026, April 8). Next generation Vertis TVPs with integrated ModulaSENSE taste modulation technology.
- [11] Archer Daniels Midland Company. (2025). ADM 2025 alternative protein outlook report.
- [12] Federal Statistical Office of Germany. (2026, May 18). Fleischersatz-Produktion sinkt 2025 um 1,2 % gegenüber dem Vorjahr.
- [13] Department for Environment, Food and Rural Affairs. (2025, December 11). United Kingdom Food Security Digest 2025.
- [14] U.S. Department of Agriculture, Foreign Agricultural Service. (2026). Soybeans.
- [15] Ministry of Agriculture, Food and Rural Affairs. (2026, January 20). Exports of K-Food Plus reached USD 13.6 billion in 2025.
- [16] Ministry of Agriculture, Forestry and Fisheries. (2026, March 12). Food-tech initiatives.
- [17] International Flavors & Fragrances Inc. (2026, June 9). IFF 2025 Do More Good Report highlights progress in nature-based innovation.
- [18] Ingredion Incorporated. (2026, January 23). VITESSENCE TEX Crumbles 1651 technical specification.
- [19] BENEO. (2026, May 13). Plant-forward, not perfect: The rise of hybrid meat products.
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is Texturized Vegetable Protein Market during 2026?
- What CAGR is forecast for the Texturized Vegetable Protein Market through 2036?
- Which product type holds notable Texturized Vegetable Protein Market share?
- Which form holds a notable texturized vegetable protein share in 2026?
- Which countries show notable Texturized Vegetable Protein Market growth?
- Which companies are active in the Texturized Vegetable Protein Market during 2026?
Frequently Asked Questions
How large is the Texturized Vegetable Protein Market expected to be in 2026?
Future Market Insights estimates that the texturized vegetable protein market will reach USD 1.7 billion in 2026. The market is projected to expand further and reach USD 3.2 billion by 2036.
What CAGR is forecast for the Texturized Vegetable Protein Market through 2036?
As per FMI, the texturized vegetable protein market is projected to grow at a 6.6% CAGR from 2026 to 2036. Growth is supported by demand for structured plant protein in processed foods.
Which product type holds a notable texturized vegetable protein demand share in 2026?
Future Market Insights projects soy protein to hold 69.6% of product type demand in 2026. The segment benefits from feedstock scale and established extrusion knowledge.
Which form holds a notable texturized vegetable protein share in 2026?
FMI finds that granules will hold 35.3% of form demand in 2026. Demand is supported by controlled hydration in ground and reformed food applications.
Which country has a notable texturized vegetable protein expansion outlook during the forecast period?
Future Market Insights predicts Germany to expand at an 8.4% CAGR during the 2026 to 2036 assessment period. Growth is supported by established meat-substitute production and continued texture improvement.
Which companies are active in the Texturized Vegetable Protein Market during 2026?
As per FMI analysis, notable companies include Cargill, Incorporated; Archer Daniels Midland Company; Roquette Freres; International Flavors & Fragrances Inc.; Fuji Oil Co., Ltd.; MGP Ingredients, Inc.; Ingredion Incorporated; dsm-firmenich; The Scoular Company; BENEO GmbH. These companies focus on source breadth, extrusion capability, application support, and supply reach.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Soy protein
- Pea protein
- Wheat protein
- Rice protein
- Faba bean protein
- Lentil protein
- Flax protein
- Chia protein
- Soy protein
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Granules
- Chunks
- Flakes
- Slices
- Granules
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Process Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Process Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Process Type, 2026 to 2036
- Dry TVP
- Wet TVP
- Dry TVP
- Y-o-Y Growth Trend Analysis By Process Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Process Type, 2026 to 2036
- Global Market Analysis and Forecast, By End-use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-use, 2026 to 2036
- Meat analogues
- Animal feed and pet food
- Household
- Bakery
- Ready meals
- Snacks
- Commercial
- Sports nutrition
- Clinical nutrition
- Baby food
- Others
- Meat analogues
- Y-o-Y Growth Trend Analysis By End-use, 2021 to 2025
- Absolute $ Opportunity Analysis By End-use, 2026 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Nature, 2026 to 2036
- Conventional
- Organic
- Conventional
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Direct
- Hypermarkets and supermarkets
- Convenience stores
- Online retail
- Traditional grocery retailers
- Food and drink speciality
- Direct
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Form
- By Process Type
- By End-use
- By Nature
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Cargill, Incorporated
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Archer Daniels Midland Company
- Roquette Freres
- Ingredion Incorporated
- dsm-firmenich
- International Flavors & Fragrances Inc.
- Fuji Oil Co., Ltd.
- MGP Ingredients, Inc.
- BENEO GmbH
- The Scoular Company
- Cargill, Incorporated
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


