

- Market Size (2026)
- USD 240.8 Mn
- Forecast (2036)
- USD 381.2 Mn
- CAGR (2026 to 2036)
- 4.7%
How big is Sulphur Bentonite Market in 2026?
Sales of sulphur bentonite are projected to expand at a 4.7% CAGR between 2026 and 2036. Sales are estimated at USD 240.8 million in 2026, up from USD 230.0 million in 2025, and are projected to reach USD 381.2 million by 2036.
Sulphur bentonite market size stood at USD 230.0 million in 2025 and is projected to grow from USD 240.8 million in 2026 to USD 381.2 million by 2036, at a CAGR of 4.7% from 2026 to 2036, as per FMI.
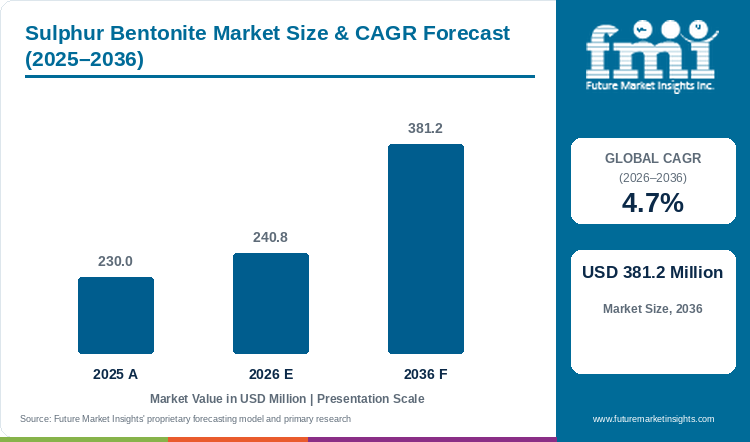
Crop area on sulphur-poor soils sets the base for sales of slow-release sulphur. The University of Nebraska-Lincoln announced in January 2026 a two-year project with the University of Colorado Boulder, the International Fertilizer Association and The Sulphur Institute to compile global sulphur data for major cropping systems[1]. The project team says a deficiency in sulphur may be limiting crop yields in many regions around the world[1]. Better soil data will show farmers and fertilizer firms the regions with the widest sulphur gaps. Demand for sulphur bentonite will rise in those regions as growers add sulphur to oilseed, cereal and pulse programmes. Key drivers of the market include yield pressure and the need for slow-release nutrient formats. Key challenges include price competition from other sulphur fertilizers and the pace of farmer education. Growth of the sulphur bentonite market will be steady across the forecast period.
Key Market Trends & Insights
- By application, oilseeds led the market with a share of 45% in 2026, ahead of cereals and grains at 27%, as rapeseed, soybean, sunflower and groundnut crops need steady sulphur. Indian Farming reports that oilseeds and legumes, which have high sulphur demands, are particularly affected.[2]
- By sulphur content, 90% sulphur bentonite accounted for 62% of sales in 2026, as a higher grade carries more sulphur in each bag.
- By distribution channel, agri-retail dealers handled 46% of sales in 2026. In February 2026, the board of National Fertilizers Limited approved in principle a bentonite sulphur plant of 25,000 tonnes a year at Vijaipur.[3]
Regional Highlights
- Fastest-growing profiled country: India (5.6% CAGR, 2026 to 2036).
- By country: China (5.2%) and Brazil (5%) follow, with Turkey at 4.8%, the USA at 4.5% and Australia at 4.3%, and Germany recording the lowest profiled CAGR at 4.1%.
- Farmers in India planted an estimated 9.3 million hectares of rapeseed in the 2025/26 marketing year, USDA reported in February 2026.[4]
Market Size & Forecast
Table 1: Market Size and Forecast for the Sulphur Bentonite Market (USD million and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 230.0 million |
| Estimated Market Size in 2026 | USD 240.8 million |
| Projected Market Size by 2036 | USD 381.2 million |
| CAGR, 2026 to 2036 | 4.7% |
| Added Revenue, 2026 to 2036 | USD 140.4 million |
| Market Expansion Multiple | 1.6x |
Demand for sulphur bentonite follows the area of crops grown on soils that no longer supply enough sulphur. The Mosaic Company reports a 34% to 86% decline in atmospheric sulphur deposition across North America between 2000 and 2020.[5] A CU Boulder researcher on the Nebraska project attributes expected sulphur deficiency to less atmospheric sulphur, purer fertilizers, higher crop yields and loss of soil organic matter.[1] Buyers purchase sulphur bentonite in the same season as nitrogen and phosphate products, and the phosphate fertilizer market shows the nutrient basket that dealers stock. Elemental sulphur is also the raw material for the sulphuric acid market, so sulphur supply links two separate industries. As per FMI, farmers apply slow-release pastilles ahead of sowing, and sales track oilseed area.
Oilseed Area and Soil Sulphur Readiness
Oilseed area across the largest producing countries is the base for sulphur bentonite sales, and the data show uneven growth. Bentonite clay is blended with elemental sulphur to form each pastille, so supply from the bentonite market connects directly to production. India, China and Brazil carry the largest oilseed plantings among the profiled countries. Soybean grown in Brazil supplies crushers, and the soybean oil market draws on the same fields. Only 5% to 15% of applied elemental sulphur is available to the crop in the same growing season, Mosaic notes.[5] A slow release makes timing before sowing important for buyers.
Table 2: Oilseed Area and Soil Sulphur Indicators for the Sulphur Bentonite Market (hectares, tonnes, percentage and currency), mixed reporting years from 2022 to 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| India oilseed area, 2022-23 and 2030-31 target | 29 million hectares, with a mission aim of 33 million hectares by 2030-31 | Wider oilseed area adds hectares that need sulphur. | [6] |
| India soils deficient in sulphur | Nearly 44%, citing earlier studies | A large deficient share widens the buyer base. | [7] |
| India planted area, 2025/26 | Rapeseed 9.3 million hectares; soybean 12.5 million; peanut 5.62 million | Mustard and groundnut growers form a large buyer base. | [4] |
| China planted area, 2025/26 | Rapeseed 7.5 million hectares, from 7.45 million; soybean 9.96 million | A steady rapeseed base keeps sulphur needs in view. | [8] |
| Brazil soybean area, 2025/26 | 48.7 million hectares, from 47.4 million; production 176.1 million tonnes | Higher yields demand more sulphur from soil. | [9] |
| Turkiye sunflower harvested area, 2025/26 | 760,000 hectares, up about 10%; production 1.2 million tonnes | Area recovery supports fertiliser programmes. | [10] |
| North America sulphur deposition, 2000 to 2020 | Down 34% to 86% | Falling deposition leaves less sulphur for crops. | [5] |
| Soil test sulphur in five Great Lakes states, 1996 to 2024 | Down close to 50% | Falling soil sulphur widens the buyer base. | [5] |
| Elemental sulphur available in the same season | 5% to 15% of the amount applied | Slow release favours application before sowing. | [5] |
| NFL bentonite sulphur plant, February 2026 | 25,000 tonnes a year; Rs. 104.03 crore | New Indian capacity serves growing domestic demand. | [3] |
Analyst Perspective
“Farmers in India, China and Brazil are expected to answer wider sulphur gaps with slow-release pastilles applied before sowing. Producers that keep 90% sulphur grades on dealer shelves ahead of each sowing window will serve most of the new oilseed area through 2036.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the Sulphur Bentonite Market segmented?
The sulphur bentonite market is segmented into application, sulphur content and distribution channel, and region. In 2026, oilseeds hold 45% of application sales, followed by cereals and grains at 27%, fruits and vegetables at 14%, plantation and cash crops at 9% and others at 5%. In 2026, 90% sulphur bentonite holds 62% of sulphur content sales and agri-retail dealers hold 46% of distribution channel sales.
By application: oilseeds (soybean, rapeseed/canola, sunflower, and groundnut and others), cereals and grains, fruits and vegetables, plantation and cash crops, and others.
By sulphur content: 90% sulphur bentonite, 85-89% sulphur bentonite, and below 85% sulphur and blends.
By distribution channel: agri-retail dealers, cooperatives, direct-to-farm, and online/marketplace.
By region: North America, Latin America, Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why are oilseeds the largest application for sulphur bentonite?
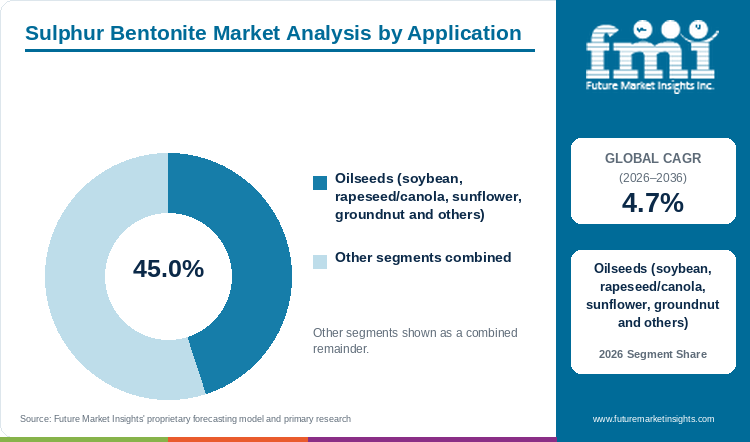
Oilseeds account for 45% of application sales in 2026, as rapeseed, soybean, sunflower and groundnut crops need steady sulphur.
Table 3: Application Share for the Sulphur Bentonite Market (percentage share), 2026
| Application | Share (2026) |
|---|---|
| Oilseeds | 45% |
| Cereals and Grains | 27% |
| Fruits and Vegetables | 14% |
| Plantation and Cash Crops | 9% |
| Others | 5% |
| Total | 100% |
Table 4: Application Leadership and Market Growth for the Sulphur Bentonite Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.7% |
| Leading Segment | Oilseeds |
Oilseeds and legumes have high sulphur demands, and Indian Farming reported in an article published online in January 2026 that both are particularly affected.[2] The FMI report places oilseeds at 45% of application sales in 2026. Within oilseeds, soybean holds 35%, rapeseed and canola 28%, sunflower 22%, and groundnut and others 15%. Cereals and grains follow with 27%, fruits and vegetables with 14%, plantation and cash crops with 9%, and other crops with 5%. India aims to widen oilseed area from 29 million hectares in 2022-23 to 33 million hectares by 2030-31.[6] Wider area under the mission adds to the base that already puts oilseeds in front.
- Soybean is the largest oilseed with 35% of oilseed sales, and oilseeds as a group hold 45% of application sales in 2026.
- Growers of mustard and groundnut are advised to confirm soil sulphur before sowing.
Why does 90% sulphur bentonite lead sulphur content sales?
In 2026, 90% sulphur bentonite takes 62% of sulphur content sales, as a higher grade carries more sulphur in each bag.
Sales of 90% sulphur bentonite lead because each bag carries more sulphur, so buyers need fewer bags for each hectare. Per the FMI report, this grade holds 62% of sulphur content sales in 2026, with 85-89% grades near 25% and grades below 85% plus blends near 13%. Blends below 85% sulphur suit buyers who want sulphur alongside other nutrients, as in the wider specialty fertilizers market. Sulphate-based fertilizers give sulphur to plants at once but are subject to leaching, Mosaic notes in a 2026 publication.[5] Buyers weighing a slow-release 90% pastille against sulphate sources face a trade between release speed and leaching.
- 90% sulphur bentonite holds 62% of sulphur content sales in 2026, supported by lower bag counts for each hectare.
- Buyers compare sulphur percentage, pastille size and breakdown time in moist soil before ordering.
What gives agri-retail dealers the lead in distribution channel sales?
Agri-retail dealers handle 46% of distribution channel sales in 2026, as farmers buy inputs from the shop nearest the field.
Local dealers stock seed, nutrients and advice at one counter before sowing, so farmers buy sulphur bentonite there. Agri-retail dealers hold 46% of channel sales in 2026, as per FMI, followed by cooperatives at 28%, direct-to-farm sales at 18% and online marketplaces at 8%. Stocking ahead of the sowing window matters most for dealers in oilseed districts. Dealer demonstrations of pastilles on mustard and soybean plots give smaller farms a trial before purchase.
- Agri-retail dealers handle 46% of channel sales in 2026, with cooperatives next at 28%.
- Suppliers check dealer stock levels and pastille delivery dates before each sowing window.
What are the drivers, restraints, and opportunities in the Sulphur Bentonite Market?
Falling soil sulphur and wider oilseed area push sales of sulphur bentonite, slow release and uneven crop area limit adoption, and new bentonite sulphur capacity in India opens the main opportunity.
- Driver: Falling soil sulphur and wider oilseed cultivation raise the need for slow-release sulphur.
- Restraint: Slow release of elemental sulphur and weather risk to crop returns may hold back purchases among smallholders.
- Opportunity: New bentonite sulphur capacity in India opens growth for domestic supply.
Falling Soil Sulphur Supports Demand
Growth of the sulphur bentonite market is tied to shrinking sulphur reserves in major cropping regions. Mosaic reports that soil test levels in Illinois, Indiana, Michigan, Ohio and Wisconsin have fallen close to 50% from 1996 to 2024.[5] The Nebraska project team attributes expected sulphur deficiency to less atmospheric sulphur, higher fertilizer purity and loss of soil organic matter.[1] Farmers can no longer count on rain and soil to meet crop needs. Oilseed fields with low organic matter carry the highest need for slow-release sulphur.
Slow Release and Weather Risk Limit Adoption
Key challenges in the sulphur bentonite market include the slow release of pastilles. Only 5% to 15% of applied elemental sulphur is available to the crop in the same growing season, Mosaic reports.[5] USDA reported in September 2025 that drought cut the Turkiye sunflower production forecast to 1.2 million tonnes, from 1.35 million tonnes a year earlier.[10] Weak harvests reduce the cash available for inputs on smallholder farms. Smallholders in dry regions buy fewer inputs after weak seasons.
New Indian Capacity Opens Supply
Adoption of locally made sulphur bentonite in India is set to widen as new capacity arrives. In February 2026, NFL approved in principle a bentonite sulphur plant of 25,000 tonnes a year at Vijaipur, and the board cited growing demand.[3] The estimated cost is Rs. 104.03 crore, and the project is at an initial stage.[3] The Vijaipur unit has nil bentonite sulphur capacity today.[3] Local production is expected to shorten delivery times to dealers in oilseed districts through 2036.
Which country CAGRs are profiled in the Sulphur Bentonite Market?
Table 5: Country CAGR Comparison for the Sulphur Bentonite Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| India | 5.6% |
| China | 5.2% |
| Brazil | 5% |
| Turkey | 4.8% |
| USA | 4.5% |
| Australia | 4.3% |
| Germany | 4.1% |
How do country-level CAGRs compare in the sulphur bentonite market?
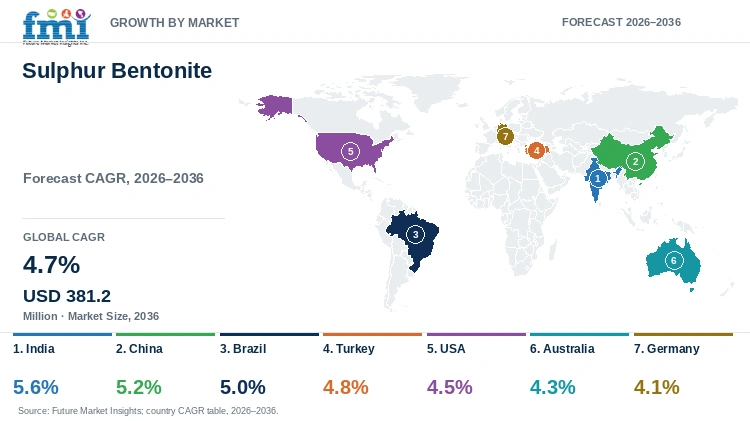
Growth across the seven profiled countries differs owing to oilseed area, soil sulphur status and supplier reach. As per the analysis from FMI, India is projected at 5.6% CAGR from 2026 to 2036, followed by China at 5.2% and Brazil at 5%. Turkey is estimated at 4.8%, the USA at 4.5% and Australia at 4.3%. Germany is projected at 4.1%. Crop area and soil sulphur gaps separate the faster countries from the slower ones.
- India pairs oilseed mission targets with sulphur-poor soils and a planned domestic plant.
- China draws on a steady rapeseed base and soil health programmes.
- Brazil combines a large soybean area with higher sulphur removal.
- Turkey links sunflower area recovery to soil health programmes.
- US growth follows falling soil sulphur in Midwest crop states.
- Australia draws on regional supply from Devco Australia and Coogee Chemicals.
- Germany records the smallest CAGR of the profiled countries within a European market.
Full report country CAGRs cover North America, Latin America, Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Country-wise Analysis
India Sulphur Bentonite Market Outlook (2026 to 2036)
India is projected at 5.6% CAGR from 2026 to 2036, the fastest of the profiled countries, with oilseed mission targets on sulphur-poor soils driving demand. Nearly 44% of Indian soils are deficient in sulphur, a 2025 agronomy paper notes, citing earlier studies.[7] USDA estimated in February 2026 that farmers planted 9.3 million hectares of rapeseed, 12.5 million hectares of soybean and 5.62 million hectares of peanut in the 2025/26 marketing year.[4] The mission aims to widen oilseed area from 29 million hectares in 2022-23 to 33 million hectares by 2030-31.[6] NFL has approved in principle a 25,000 tonne a year bentonite sulphur plant at Vijaipur.[3]
Key takeaway: Mustard and groundnut growers in sulphur-poor districts form the core of Indian orders, and the planned Vijaipur plant would shorten delivery times.
China Sulphur Bentonite Market Outlook (2026 to 2036)
Chinese rapeseed growers form the buyer base for slow-release sulphur. USDA Beijing estimated in December 2025 that China planted 7.5 million hectares of rapeseed in 2025/26, up from 7.45 million hectares a year earlier.[8] Soybean planted area was estimated at 9.96 million hectares.[8] China records a 5.2% CAGR from 2026 to 2036, second only to India. Government soil health programmes drive demand, and balanced fertilisation favours sulphur in slow-release form. Oilseeds and legumes have high sulphur demands and are particularly affected, Indian Farming notes.[2]
Key takeaway: A large and steady rapeseed base and soil health programmes hold Chinese orders for sulphur grades at a steady level.
Brazil Sulphur Bentonite Market Outlook (2026 to 2036)
Brazil is set for a 5% CAGR from 2026 to 2036, third among the profiled countries. Conab forecast in January 2026 that the 2025/26 soybean area would reach 48.7 million hectares, up from 47.4 million hectares.[9] Production was forecast at 176.1 million tonnes.[9] Higher crop yields demand more sulphur from soil, a factor a CU Boulder researcher on the Nebraska project links to expected deficiency.[1] Large soybean farms suit bulk purchases of pastilles.
Key takeaway: Large soybean farms add sulphur top-ups as yields rise.
Turkey Sulphur Bentonite Market Outlook (2026 to 2036)
Drought set the tone for the Turkish sunflower crop in 2025. USDA Ankara reported in September 2025 that sunflower harvested area in Turkiye was projected at 760,000 hectares for 2025/26, up approximately 10% from the prior year, yet production was revised lower to 1.2 million tonnes from 1.35 million tonnes in 2024/25, reflecting drought-driven yield losses.[10] Growers rebuilding yield per hectare have reason to widen fertiliser programmes. Turkey records a 4.8% CAGR from 2026 to 2036, and government soil health programmes support sales.
Key takeaway: Sunflower farmers recovering from a dry year can add sulphur to fertiliser plans.
USA Sulphur Bentonite Market Outlook (2026 to 2036)
Falling sulphur deposition is the main case for sulphur products in the USA. Mosaic reported in 2026 that deposition across North America declined 34% to 86% between 2000 and 2020.[5] Soil test sulphur in Illinois, Indiana, Michigan, Ohio and Wisconsin fell close to 50% from 1996 to 2024.[5] Sulphur depletion leads to yield penalties in corn, wheat and soybeans when not addressed.[5] The USA grows at a 4.5% CAGR from 2026 to 2036, as per FMI estimates. Sulphate sources are subject to leaching.[5]
Key takeaway: Midwest growers on depleted soils face yield penalties unless sulphur rates rise.
Australia Sulphur Bentonite Market Outlook (2026 to 2036)
Supply in Australia is served by regional producers. Devco Australia and Coogee Chemicals focus on regional supply and cost-effective production. Australia is projected at 4.3% CAGR from 2026 to 2036, below the leading profiled countries. Growth follows local fertiliser programmes and the stocking plans of regional dealers.
Key takeaway: Regional producers give Australian farms short supply lines, and growth stays moderate at 4.3%.
Germany Sulphur Bentonite Market Outlook (2026 to 2036)
The lowest profiled CAGR, 4.1% from 2026 to 2036, belongs to Germany. Buyers in Germany are served within the European market, and Tiger-Sul Products supplies sulphur bentonite across North America, Europe and Asia. The Nebraska project team links expected sulphur deficiency to less atmospheric sulphur and higher fertilizer purity.[1] Farm demand in Germany runs through established fertiliser programmes and dealer networks.
Key takeaway: Germany grows at the lowest profiled rate of 4.1%, as supply from established importers serves a mature market.
Who are the notable companies in the Sulphur Bentonite Market?
Tiger-Sul Products, Coromandel International, NFL, Devco Australia, Coogee Chemicals, IFFCO, The Mosaic Company, ICL Group, Abu Dhabi Fertilizer Industries, and Kugler Company are notable companies profiled in this market.
Tiger-Sul Products, now operating as a brand within Tessenderlo Kerley following an acquisition completed in November 2024, supplies sulphur bentonite across North America, Europe and Asia. Coromandel International and NFL operate at large scale with advanced formulation technology. Devco Australia, Coogee Chemicals and IFFCO focus on regional supply and cost-effective production. Suppliers differ in scale, formulation and distribution reach. NFL has approved a Vijaipur plant, and Mosaic publishes agronomy research on sulphur. Suppliers with local capacity and dealer networks hold the shortest route to new oilseed area.
- Scale leaders: Tiger-Sul Products, Coromandel International, and NFL supply large volumes of formulated sulphur bentonite.
- Regional challengers: Devco Australia, Coogee Chemicals, and IFFCO serve regional markets.
- Global fertilizer suppliers: The Mosaic Company, ICL Group, Abu Dhabi Fertilizer Industries, and Kugler Company offer tailored sulphur fertilizers, global supply chains and cooperative partnerships.
Competitive Benchmarking: Sulphur Bentonite Market
Table 6: Competitive Benchmarking for the Sulphur Bentonite Market (qualitative documentation ratings), 2026
| Company | Sulphur Bentonite | Agronomy Evidence | Activity | Disclosure |
|---|---|---|---|---|
| NFL | Medium | Low | High | High |
| The Mosaic Company | Low | High | Medium | High |
| Tiger-Sul Products | Medium | Low | Low | Low |
High indicates wider documentation in company filings and releases, Medium indicates limited documentation, and Low indicates less direct documentation. Ratings do not indicate product quality, market share or company rank.
Key Developments in the Sulphur Bentonite Market
- In February 2026, the board of National Fertilizers Limited approved in principle a bentonite sulphur plant of 25,000 tonnes a year at Vijaipur, at an estimated cost of Rs. 104.03 crore.[3]
- USDA New Delhi estimated in February 2026 that 2025/26 area planted in India was 9.3 million hectares for rapeseed and 12.5 million hectares for soybean.[4]
- The Mosaic Company published AgriSight Issue 28 in 2026 on sulphur application in North American cropping systems.[5]
- In January 2026, the University of Nebraska-Lincoln, the University of Colorado Boulder, the International Fertilizer Association and The Sulphur Institute announced a two-year project to compile global sulphur data for major crop systems.[1]
Key Players in the Sulphur Bentonite Market
Scale Leaders
- Tiger-Sul Products (Tessenderlo Kerley)
- Coromandel International Limited
- National Fertilizers Limited (NFL)
Regional Challengers
- Devco Australia
- Coogee Chemicals
- Indian Farmers Fertiliser Cooperative Limited (IFFCO)
Global Fertilizer Suppliers
- The Mosaic Company
- ICL Group
- Abu Dhabi Fertilizer Industries
- Kugler Company
Sulphur Bentonite Market - Report Scope
Table 7: Report Scope for the Sulphur Bentonite Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Application; sulphur content; distribution channel; region |
| Quantitative units | USD million |
| Market definition | Sales of slow-release sulphur formulations that blend elemental sulphur with bentonite, sold as pastilles or granules by percentage sulphur content. |
| Regions covered | North America; Latin America; Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | India; China; Brazil; Turkey; USA; Australia; Germany |
| Key companies profiled | Tiger-Sul Products, Coromandel International, NFL, Devco Australia, Coogee Chemicals, IFFCO, The Mosaic Company, ICL Group, Abu Dhabi Fertilizer Industries, Kugler Company |
| Forecast period | 2026 to 2036 |
Sulphur Bentonite Market - Research Methodology
Table 8: Research Methodology for the Sulphur Bentonite Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Market sizes, segment shares, country CAGRs and company shares follow the market model. Crop area and soil sulphur facts come from government reports, journals, company filings and trade press dated May 2025 or later. |
| Desk Research | Desk research covers company filings, USDA attache reports, agronomy journals and publications from fertilizer producers. |
| Market Sizing and Forecasting | Sizing starts from the 2025 base size of USD 230.0 million and the 4.7% CAGR. |
| Data Validation | Agronomy and company facts are matched to dated government, journal or company records before use. |
Sulphur Bentonite Market by Segments
Sulphur Bentonite Market segmented by Application:
- Oilseeds (soybean, rapeseed/canola, sunflower, groundnut and others)
- Cereals and grains
- Fruits and vegetables
- Plantation and cash crops
- Others
Sulphur Bentonite Market segmented by Sulphur Content:
- 90% sulphur bentonite
- 85-89% sulphur bentonite
- Below 85% sulphur and blends
Sulphur Bentonite Market segmented by Distribution Channel:
- Agri-retail dealers
- Cooperatives
- Direct-to-farm
- Online/marketplace
Sulphur Bentonite Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Nordics and Benelux
- Central and Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkey
- South Africa
- Rest of Middle East and Africa
Research Sources and Bibliography
- [1] University of Nebraska-Lincoln, Institute of Agriculture and Natural Resources. (2026, January 21). Nebraska joins international collaboration to map global crop sulfur use and deficiencies. https://ianrnews.unl.edu/article/nebraska-joins-international-collaboration-to-map-global-crop-sulfur-use-and-deficiencies-0
- [2] Choudhary, S. and Singh, A., Indian Farming, Indian Council of Agricultural Research. (2026, January 6). Sulfur: An overlooked essential plant nutrient. https://epubs.icar.org.in/index.php/IndFarm/article/view/165491
- [3] National Fertilizers Limited (stock exchange intimation under SEBI Regulation 30). (2026, February 13). Board approval in principle for a bentonite sulphur plant at Vijaipur. https://nsearchives.nseindia.com/corporate/NFL_13022026181125_SignedNSEreg30.pdf
- [4] USDA Foreign Agricultural Service, New Delhi. (2026, February 4). India: Oilseeds and Products Update (IN2026-0002). https://apps.fas.usda.gov/newgainapi/api/Report/DownloadReportByFileName?fileName=Oilseeds%20and%20Products%20Update_New%20Delhi_India_IN2026-0002.pdf
- [5] The Mosaic Company. (2026). The Case for Increased Sulfur Application in North American Cropping Systems (AgriSight, Issue 28). https://www.cropnutrition.com/wp-content/uploads/2026/02/MC-1718-AgriSight-28-Increased-Sulfur-App-in-NA-Cropping-Systems-FNL-ELECTRONIC-1.pdf
- [6] New India Samachar, Press Information Bureau, Government of India. (2026, February 1-15). Steps towards self-reliance in edible oils and pulses. https://newindiasamachar.pib.gov.in/WriteReadData/flipbook/2026/Feb/1st/English/files/basic-html/page27.html
- [7] Giri, K. S., Sahoo, B. K., Behera, B., Behera, S. D. and Jena, J., Indian Journal of Agronomy. (2025, June). Sulphur management in rice (Oryza sativa)-groundnut (Arachis hypogaea) to boost crop growth and system productivity. https://pub.isa-india.in/index.php/ija/article/download/6552/5321/8976
- [8] USDA Foreign Agricultural Service, Beijing. (2025, December 4). China: Oilseeds and Products Update (CH2025-0226). https://apps.fas.usda.gov/newgainapi/api/Report/DownloadReportByFileName?fileName=Oilseeds%20and%20Products%20Update_Beijing_China%20-%20People%27s%20Republic%20of_CH2025-0226.pdf
- [9] Conab – Companhia Nacional de Abastecimento. (2026, January 15). Acompanhamento da Safra Brasileira de Grãos – Safra 2025/26, 5° Levantamento. Brasília: Conab. [Brazil 2025/26 soybean area estimated at 48.67 million hectares; production estimated at 176.1 million tonnes]
- [10] USDA Foreign Agricultural Service, Ankara. (2025, September 25). Turkiye: Oilseeds and Products Update (TU2025-0050). https://apps.fas.usda.gov/newgainapi/api/Report/DownloadReportByFileName?fileName=Oilseeds%20and%20Products%20Update_Ankara_Turkiye_TU2025-0050.pdf
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the sulphur bentonite market during 2026?
- What market size is projected by 2036?
- Which application holds notable share?
- Which sulphur content grade holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the sulphur bentonite market expected in 2026?
Future Market Insights estimates sulphur bentonite market size at USD 240.8 million in 2026. The market is projected to reach USD 381.2 million by 2036, a steady rise over the forecast period.
What CAGR is projected for the sulphur bentonite market through 2036?
As per FMI analysis, sulphur bentonite sales are projected to grow at a 4.7% CAGR from 2026 to 2036. Wider oilseed area and falling soil sulphur support the outlook.
Which application holds a notable market share in 2026?
Oilseeds account for 45% of application sales in 2026, followed by cereals and grains at 27%. Soybean, rapeseed, sunflower and groundnut crops need steady sulphur.
Which sulphur content grade holds a notable market share in 2026?
The 90% sulphur grade accounts for 62% of sulphur content sales in 2026, because each bag carries more sulphur for each hectare.
Which country has a notable growth outlook through 2036?
The fastest growth, 5.6% CAGR from 2026 to 2036, is projected for India, according to FMI. Oilseed mission targets on sulphur-poor soils add to demand.
Who are the key companies in the sulphur bentonite market?
Notable companies include Tiger-Sul Products, Coromandel International, NFL, Devco Australia, Coogee Chemicals, IFFCO, The Mosaic Company, ICL Group, Abu Dhabi Fertilizer Industries, and Kugler Company.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application, 2026 to 2036
- Oilseeds (soybean, rapeseed/canola, sunflower, groundnut and others)
- Cereals and grains
- Fruits and vegetables
- Plantation and cash crops
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Sulphur Content, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sulphur Content, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sulphur Content, 2026 to 2036
- 90% sulphur bentonite
- 85-89% sulphur bentonite
- Below 85% sulphur and blends
- Y-o-Y Growth Trend Analysis By Sulphur Content, 2021 to 2025
- Absolute $ Opportunity Analysis By Sulphur Content, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Agri-retail dealers
- Cooperatives
- Direct-to-farm
- Online/marketplace
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Application
- By Sulphur Content
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Sulphur Content
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Application
- By Sulphur Content
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Sulphur Content
- By Distribution Channel
- Key Takeaways
- Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Nordics and Benelux
- Central and Eastern Europe
- By Application
- By Sulphur Content
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Sulphur Content
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Application
- By Sulphur Content
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Sulphur Content
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia
- Rest of South Asia and Pacific
- By Application
- By Sulphur Content
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Sulphur Content
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Turkey
- South Africa
- Rest of Middle East and Africa
- By Application
- By Sulphur Content
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Application
- By Sulphur Content
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- Turkey
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Application
- By Sulphur Content
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Application
- By Sulphur Content
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- NFL
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- The Mosaic Company
- Tiger-Sul Products
- Tiger-Sul Products LLC
- Coromandel International Limited
- National Fertilizers Limited (NFL)
- Devco Australia
- Coogee Chemicals
- Indian Farmers Fertiliser Cooperative Limited (IFFCO)
- ICL Group
- Abu Dhabi Fertilizer Industries
- Kugler Company
- NFL
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


