

- Market Size (2026)
- USD 6.2 Bn
- Forecast (2036)
- USD 14.0 Bn
- CAGR (2026 to 2036)
- 8.5%
How Big is the Soluble Fiber Market in 2026?
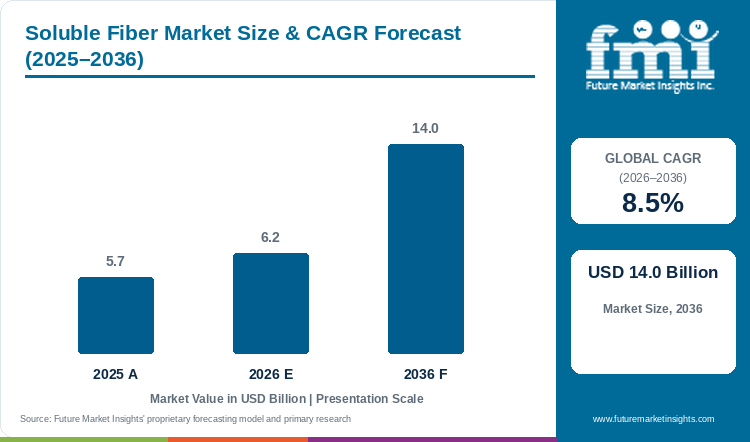
Sales of soluble fiber will reach USD 6.2 Billion in 2026, up from USD 5.7 Billion in 2025. The market will expand at an 8.5% CAGR from 2026 to 2036 and touch USD 14.0 Billion by 2036.
Soluble fiber market size is estimated at USD 6.2 Billion in 2026, up from USD 5.7 Billion in 2025, as per FMI. Sales will reach USD 14.0 Billion by 2036 at an 8.5% CAGR, about 2.3 times the 2026 base.
Growth of the soluble fiber market will run a little below the parent dietary fiber market, which is set to expand from USD 15.0 Billion in 2026 to USD 40.0 Billion by 2036 at a 10.3% CAGR, an opportunity of USD 25.0 Billion. Demand for gut health claims is opening a second pool, as the prebiotic ingredient market will grow from USD 8.2 Billion to USD 15.7 Billion at 6.7%. Single-chemistry fibers are moving at a slower pace. The beta glucan market will gain USD 774.9 Million at a 6.2% CAGR, and the polydextrose market will widen by USD 127.2 Million at 4.1%. Soluble fiber will outpace both, since one ingredient choice covers fiber enrichment, sugar replacement and bulk recovery in the same recipe. The same versatility will keep adoption potential of resistant maltodextrin high, at 30.4% of product type revenue in 2026.
Key drivers of the soluble fiber market include sugar reduction targets and the fiber gap in everyday diets, as food and beverage makers are replacing sugar without losing body or mouthfeel. Key challenges include dose tolerance, owing to which suppliers with clinical data at the target serving will see better ROI than suppliers selling fiber content alone. Opportunities will open in beverages, gummies and protein products, where clear-label soluble fibers with proven gut health benefits will command a premium over commodity fiber grades.
Technical evidence keeps building, and ADM reported in July 2026 that Fibersol is well tolerated at up to 68 grams per day [1]. Supply will continue to scaling too, as Tate & Lyle delivered 18.3 billion servings that each close a 15-gram daily fiber gap between April 2020 and March 2026 [2].
Key Takeaways of Soluble Fiber Market
- Maltodextrin, mostly resistant grades, holds 30.4% of product type market share in 2026.
- The Others category accounts for 35.4% of end use application revenue in 2026.
- FMI profiles Cargill, ADM, Tate & Lyle, Ingredion, Roquette Frères, BENEO, Nexira, and Cosucra Groupe Warcoing among other suppliers.
- Sales of soluble fiber will grow fastest in the USA (10.3%) and the UK (9.4%) through 2036, and South Korea grows slowest at 6.5%.
- Third-party prebiotic verification is spreading, with Roquette in February 2026 and Tate & Lyle in June 2026 gaining NutraStrong Prebiotic Verified status for core fiber lines [3] [4].
Analyst Perspective
“Soluble fiber sales will reach USD 14.0 Billion by 2036, and resistant maltodextrin, at 30.4% of product type revenue, will set the pace. In my opinion, the next share gains will go to suppliers that bring tolerance data, prebiotic verification and claim files to the first customer meeting.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Soluble Fiber Market Segmented?
FMI splits the market by product type, end use application, and region.
Product type covers maltodextrin, pectin, natural/native, FOS, beta-glucan, GOS, polydextrose, and others.
End use application covers functional food & beverages, bakery, confectionery, pharmaceutical, weight management, pet food, animal feed, and others.
Why Does Maltodextrin Lead the Soluble Fiber Market by Product Type?
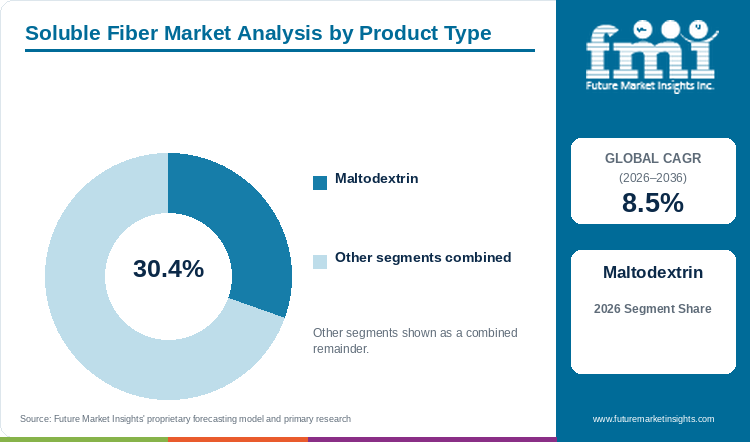
Resistant grades will keep maltodextrin at 30.4% of product type market share in 2026.
Soluble fiber market share for maltodextrin will account for 30.4% in 2026. Commercial volume sits in resistant maltodextrin and resistant dextrin, not the digestible maltodextrin used as a carrier. These grades dissolve clear, stay thin and hold up through heat and acid. One grade can therefore move from a beverage line to a bakery line without a new base recipe.
Demand for resistant dextrin also follows clinical proof. Corn remains the main raw material, as FMI's soluble corn fiber market study shows, and Roquette makes NUTRIOSE from both non-GMO corn and wheat [3].
- By product type, maltodextrin will account for 30.4% of soluble fiber market share in 2026, with resistant grades leading demand.
- In February 2026, Roquette reported NutraStrong Prebiotic Verified certification for three NUTRIOSE grades, FM 06, FB 06 and FM 15S, backed by more than 26 clinical studies [3].
What are the Drivers, Restraints, and Opportunities in the Soluble Fiber Market?
According to FMI's report, sugar limits and fiber-gap targets will keep reformulation demand high through 2036.
- Driver: Public health guidance in the USA and the UK now pushes lower sugar and higher fiber, and brands need ingredients that do both jobs.
- Restraint: Digestive tolerance, sensory change and country-specific fiber definitions narrow the usable dose and lengthen qualification.
- Opportunity: Clinically supported prebiotic fibers with regulator-accepted claims can move into health products and claim-bearing foods.
Key drivers of the soluble fiber market start with sugar. The Dietary Guidelines for Americans, 2025-2030, released in January 2026, ask people to prioritize fiber-rich whole grains and cap added sugars at 10 grams per meal [6]. In March 2026, the UK Department of Health and Social Care confirmed that the new nutrient profiling model awards more positive points to fiber and called this a reformulation opportunity [7]. Tolerance will set the ceiling, as a dose that supports a fiber claim can soften a bar or thicken a drink. The Thai FDA prebiotic claim granted to BENEO for Orafti Inulin in September 2025 shows how evidence opens a new route to market [8].
Which Country CAGRs are Profiled in the Soluble Fiber Market?
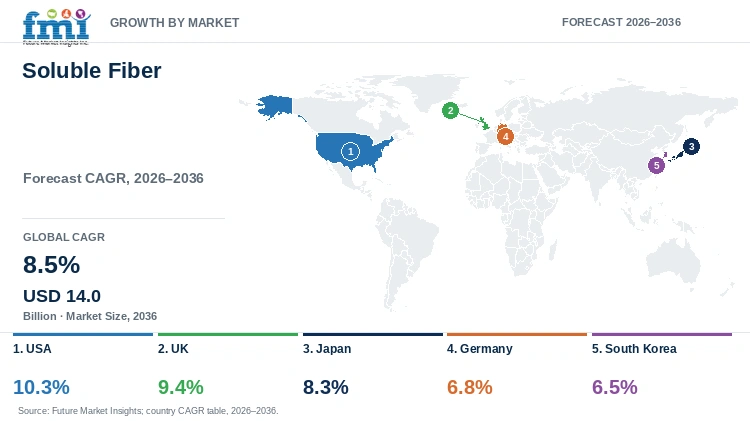
| Country | CAGR, 2026 to 2036 |
|---|---|
| USA | 10.3% |
| UK | 9.4% |
| Japan | 8.3% |
| Germany | 6.8% |
| South Korea | 6.5% |
How do Country-level CAGRs Compare in the Soluble Fiber Market?
Soluble fiber market growth across the five profiled countries spans 3.8 percentage points through 2036, from the USA at 10.3% to South Korea at 6.5%. The UK follows at 9.4%, and Japan sits in the middle at 8.3%. Sugar policy, claim systems and fiber intake gaps account for most of the spread.
- The USA will lead the demand as federal guidance sets a 10-gram limit on added sugars per meal [6].
- The UK grows 0.9 points slower, though the new nutrient profiling model gives more positive points to fiber [7].
- Japan at 8.3% grows on claim-led foods, and full GMP enforcement from September 2026 adds compliance cost [9].
- Germany and South Korea differ by only 0.3 points. German demand rests on a wide intake gap, and Korean demand rests on ingredient recognition by MFDS [10].
Soluble fiber market growth rates for the other countries in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa are part of the full FMI report.
Country Outlook
- Sugar caps will make the USA the fastest-growing soluble fiber market at a 10.3% CAGR from 2026 to 2036. The Dietary Guidelines for Americans, 2025-2030, released by HHS and USDA in January 2026, set a limit of 10 grams of added sugars per meal [6]. Resistant dextrin and soluble corn fiber replace the lost bulk, and new claims are forming, as a University of Illinois trial reported in March 2026 found faster attention responses in 42 adults taking PROMITOR soluble corn fiber [11].
- Demand for soluble fiber in the UK will rise at a 9.4% CAGR through 2036, with nutrient profiling as the main lever. The Department of Health and Social Care confirmed in March 2026 that the new nutrient profiling model gives more positive points to fiber and treats free sugars more strictly [7]. The Food Standards Agency noted in June 2026 that mandatory healthy food sales reporting for large food businesses is in preparation [12].
- Japan will grow at an 8.3% CAGR, with quality compliance shaping supplier choice as much as price. Full GMP enforcement for supplement-form Foods with Function Claims began on September 1, 2026, and Nihon Shokuryo Shimbun reported raw material quality assurance as the open issue [9]. ADM and Matsutani marked 20 years of the ADM/Matsutani Fibersol joint venture in July 2026 [1]. FMI's Japan digestion-resistant maltodextrin study covers this segment in more detail.
- Growth of the soluble fiber market in Germany will hold at a 6.8% CAGR over the forecast period. The intake gap is wide, with the Max Rubner-Institut reporting in June 2026 a median intake of 18 grams per day for women and 19 grams for men against the DGE reference of at least 30 grams [13]. Chicory fibers carry an EU blood glucose claim tied to a 30% sugar reduction, as listed by Cosucra, giving chicory suppliers an edge in sugar-reduced bakery [14].
- Sales of soluble fiber in South Korea will rise at a 6.5% CAGR through 2036, the slowest of the five profiled countries. The Ministry of Food and Drug Safety (MFDS) issued Regulation No. 2026-33 on recognition of functional ingredients and standards for health functional foods in August 2026 [10]. Suppliers that file local dossiers early will shorten the path from trial to listed product.
Who are the Notable Companies in the Soluble Fiber Market?
Cargill, ADM, Tate & Lyle, Ingredion, Roquette Frères, BENEO, Nexira, and Cosucra Groupe Warcoing are notable soluble fiber suppliers profiled by FMI.
As per FMI, soluble fiber market share among suppliers follows clinical evidence, claim approvals and the ability to support many applications from one grade. Specialists compete on prebiotic data, tolerance and plant origin. Consolidation is under way, as Tate & Lyle shareholders approved the GBP 2.7 Billion Ingredion acquisition in July 2026, with completion expected in the second half of 2027 [15]. FMI's prebiotic fiber market and pectin market studies track these suppliers in more detail.
- Corn-Based Fiber Platforms Inside Broad Ingredient Groups: Cargill, ADM, Tate & Lyle and Ingredion sell soluble corn fiber, resistant dextrin or polydextrose next to sweetener and texture systems.
- Clinically Backed Resistant Dextrin and Chicory Fiber Portfolios: Roquette Frères and BENEO build sales on NUTRIOSE and Orafti fibers, backed by prebiotic certification and regulator-approved claims.
- Botanical Fiber Specialists in Acacia and Chicory: Nexira and Cosucra Groupe Warcoing focus on acacia fiber and chicory root fiber with high tolerance and plant-origin positioning.
Competitive Benchmarking
| Company | Portfolio Breadth | Application Support | Evidence Depth | Geographic Reach |
|---|---|---|---|---|
| Cargill | Medium | High | Medium | North America |
| ADM | Medium | High | High | North America, Japan and Australia |
| Tate & Lyle | High | High | High | Global, 37 countries |
| Ingredion | Medium | High | Medium | North America and EMEA |
| Roquette Frères | Medium | High | High | North America and Europe |
| BENEO | High | High | High | Europe, the Americas and Southeast Asia |
| Nexira | Medium | Medium | High | Europe and the USA |
| Cosucra Groupe Warcoing | Medium | High | High | Belgium-based, international sales |
Scoring basis: Portfolio Breadth counts documented soluble fiber chemistries. Application Support measures documented use across food, beverage and supplement matrices. Evidence Depth measures published trials, third-party prebiotic verification and regulator-accepted claims. High means broad, clearly documented capability, Medium means narrower documented capability, and Low means limited public documentation. In September 2026, FMI reviewed public company documentation, regulatory records and trade press to set these scores.
Key Developments
- In September 2025, ADM's Fibersol gained approval from the Australian Therapeutic Goods Administration as an active ingredient for listed medicines, prescription medicines and biologicals [16].
- In February 2026, Roquette Frères announced NutraStrong Prebiotic Verified certification for three NUTRIOSE soluble fiber grades [3].
- In June 2026, Ingredion acquired the Benicaros prebiotic carrot fiber from NutriLeads, and the ingredient received EU novel food authorization later the same month [17] [18].
Key Players
Corn-Based Fiber Platforms Inside Broad Ingredient Groups
- Cargill
- ADM
- Tate & Lyle
- Ingredion
Clinically Backed Resistant Dextrin and Chicory Fiber Portfolios
- Roquette Frères
- BENEO
Botanical Fiber Specialists in Acacia and Chicory
- Nexira
- Cosucra Groupe Warcoing
Report Scope and Methodology
| Coverage field | Report scope |
|---|---|
| Market breakdown | 3 categories: Product Type (Maltodextrin, Pectin, Natural/Native, FOS, Beta-glucan, GOS, Polydextrose, Others), End Use Application (Others, Animal Feed, Pet Food, Pharmaceutical, Functional Food & Beverages, Bakery, Confectionery, Weight Management), and Region |
| Quantitative units | USD Billion |
| Market definition | Revenue from soluble fiber ingredients sold for soluble fiber functionality within the stated product type and end use application segmentation. The market excludes finished-product revenue, insoluble fiber, sweeteners and proteins sold separately, and digestible maltodextrin not sold as a soluble fiber grade. |
| Regions covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Countries covered | The USA, the UK, Japan, Germany, and South Korea are profiled, with further countries listed in the regional segmentation |
| Key companies profiled | A few of the notable companies out of many players covered by FMI include Cargill, ADM, Tate & Lyle, Ingredion, Roquette Frères, BENEO, Nexira, and Cosucra Groupe Warcoing |
| Forecast period | 2026 to 2036 |
| Approach | FMI combines supplier capacity and grade-level price data with reformulation activity and country claim rules, then reconciles bottom-up and top-down estimates for each product type and end use application. |
Research Methodology
| Method | Approach |
|---|---|
| Primary research | FMI speaks with fiber producers, ingredient distributors, food and supplement formulators, regulatory managers and procurement teams to test grade pricing, inclusion levels, tolerance limits, claim timelines and switching costs. |
| Desk research | The analysis reviews dietary guidelines, nutrient profiling rules, health functional food and claim regulations, company releases, clinical study reports and trade press in the profiled countries. FMI keeps sources that describe soluble fiber demand, approvals or supply inside the market boundary. |
| Market sizing and forecasting | The model multiplies grade-level volumes by average selling prices for each product type and end use application, then adjusts for reformulation pace, claim approvals, capacity additions and country growth conditions. |
| Data validation | Supplier evidence is checked against regulatory records and buyer interviews. Insoluble fiber, digestible maltodextrin, finished-product revenue and duplicate counting between producers and distributors are removed before final reconciliation. |
Soluble Fiber Market by Segments
Soluble Fiber Market Segmented by Product Type
- Maltodextrin
- Pectin
- Natural/Native
- FOS
- Beta-glucan
- GOS
- Polydextrose
- Others
Soluble Fiber Market Segmented by End Use Application
- Others
- Animal Feed
- Pet Food
- Pharmaceutical
- Functional Food & Beverages
- Bakery
- Confectionery
- Weight Management
Soluble Fiber Market Segmented by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Archer Daniels Midland Company (2026, July 28). ADM and Matsutani Mark 20 Years of Partnership and Innovation.
- [2] Tate & Lyle plc (2026, August 20). Tate & Lyle adds new purpose target to improve everyday consumer health through fibre fortification.
- [3] Roquette Frères (2026, February 3). NUTRIOSE® Soluble Fibers, NutraStrong™ Prebiotic Verified Certified.
- [4] Tate & Lyle plc (2026, June 3). Tate & Lyle fibre portfolio receives NutraStrong™ Prebiotic Verified certification.
- [5] Asia Food Journal (2026, September 17). BENEO spotlights fibre innovation as Indonesia’s next nutrition opportunity.
- [6] U.S. Department of Health and Human Services and U.S. Department of Agriculture (2026, January 7). Dietary Guidelines for Americans, 2025-2030.
- [7] Department of Health and Social Care (2026, March 25). Applying the new NPM to advertising and promotions restrictions, consultation response.
- [8] BENEO GmbH (2025, September 18). BENEO secures first-ever Thai FDA approval for exclusive prebiotic claim.
- [9] Nihon Shokuryo Shimbun (2026, August 31). Supplement-form Foods with Function Claims face full GMP enforcement from September 1.
- [10] Ministry of Food and Drug Safety, Republic of Korea (2026, August 13). Regulation on Recognition of Functional Ingredient and of Standard·Specification for Health Functional Foods (No. 2026-33).
- [11] Nutrition Insight (2026, March 18). Tate & Lyle’s soluble corn fiber improved focus in healthy adults, study finds.
- [12] Food Standards Agency (2026, June 25). Healthier Food Targets and Reporting (HFTR).
- [13] Max Rubner-Institut (2026, June). Wissenschaftliche Einordnung Ballaststoffe.
- [14] Cosucra Groupe Warcoing (2026, September). Fibruline™ chicory root fibre product page.
- [15] FoodNavigator (2026, July 28). Tate & Lyle shareholders vote in favour of £2.7bn Ingredion acquisition.
- [16] Archer Daniels Midland Company (2025, September 29). ADM’s Fibersol® Approved by Therapeutic Goods Administration (TGA) as an Active Ingredient for Health Products in Australia.
- [17] NutraIngredients (2026, June 16). Benicaros gains EFSA Novel Food approval.
- [18] NutraIngredients (2026, June 4). Ingredion strengthens functional fiber portfolio with Benicaros acquisition.
- [19] Tate & Lyle plc (2026, June 8). Recommended Cash Acquisition of Tate & Lyle PLC by Ingredion Incorporated.
This bibliography is provided for reader reference and is not exhaustive. The full FMI report contains the complete reference list and detailed citations.
This Report Answers
- What will the soluble fiber market be worth in 2026, and what value will FMI forecast for 2036?
- Which sugar-reduction and fiber-gap policies will keep supporting demand for soluble fiber?
- Why will maltodextrin, led by resistant grades, hold the leading position within the product type category?
- How will the Others category keep the largest share of end use application revenue?
- How will growth rates differ across the USA, the UK, Japan, Germany, and South Korea through 2036?
- Which capabilities will separate the profiled soluble fiber suppliers from each other?
- How will dose tolerance, sensory change and claim rules slow soluble fiber adoption?
- What will the Ingredion and Tate & Lyle combination mean for supplier choice?
- What will formulators need to check before qualifying a new soluble fiber grade?
Frequently Asked Questions
How big will the soluble fiber market be in 2026?
FMI estimates the soluble fiber market at USD 6.2 Billion in 2026, up from USD 5.7 Billion in 2025. Reformulation for sugar reduction and fiber enrichment will account for much of that value.
What will the CAGR of the soluble fiber market be from 2026 to 2036?
According to FMI, the market will grow at an 8.5% CAGR from 2026 to 2036, reaching USD 14.0 Billion by 2036. New claim approvals and prebiotic evidence will add to the pace.
Which product type will hold the largest share of the soluble fiber market?
Maltodextrin will lead with 30.4% of product type revenue in 2026. Resistant maltodextrin and dextrin grades will stay in demand, since these grades dissolve clear, add little sweetness and hold up through processing.
Which end use application will lead the soluble fiber market?
As per FMI, the Others category will hold 35.4% of end use application revenue in 2026. The share will come from many smaller formats outside the named segments.
Which country will grow fastest in the soluble fiber market?
Sales of soluble fiber in the USA will grow at a 10.3% CAGR through 2036, ahead of the UK at 9.4%. South Korea will be the slowest of the five profiled countries at 6.5%.
What restraint will affect the soluble fiber market?
Dose tolerance will limit inclusion levels, since a fiber dose that supports a claim can change texture or cause digestive discomfort. Country-specific fiber definitions and claim reviews will add time before launch.
Which are the key companies in the soluble fiber market?
FMI profiles Cargill, ADM, Tate & Lyle, Ingredion, Roquette Frères, BENEO, Nexira, and Cosucra Groupe Warcoing among the many suppliers covered in the full report.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Maltodextrin
- Pectin
- Natural/Native
- FOS
- Beta-glucan
- GOS
- Polydextrose
- Others
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use Application, 2026 to 2036
- Others
- Animal Feed
- Pet Food
- Pharmaceutical
- Functional Food & Beverages
- Bakery
- Confectionery
- Weight Management
- Y-o-Y Growth Trend Analysis By End Use Application, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use Application, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Application
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Application
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Application
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Application
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Application
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Application
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By End Use Application
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By End Use Application
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By End Use Application
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By End Use Application
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Cargill
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- ADM
- Tate & Lyle
- Ingredion
- Roquette Frères
- BENEO
- Nexira
- Cosucra Groupe Warcoing
- Cargill
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


