

- Market Size (2026)
- USD 337.7 Bn
- Forecast (2036)
- USD 735.9 Bn
- CAGR (2026 to 2036)
- 8.1%
How big is Senior Care Product Market in 2026?
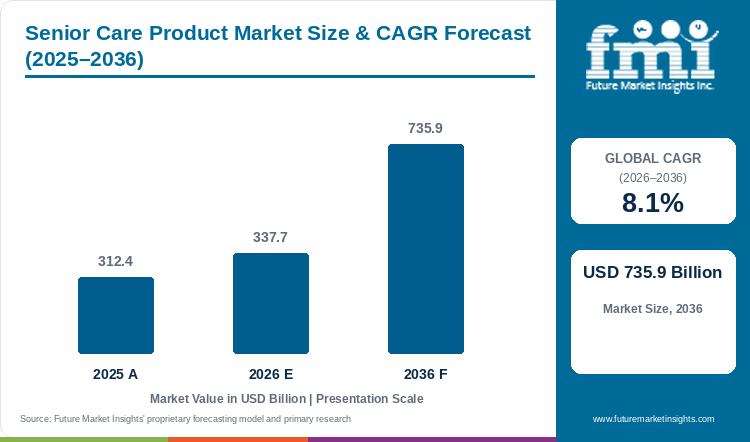
The senior care product market is estimated at USD 312.4 billion in 2025 and is projected to reach USD 337.7 billion in 2026. Senior care product sales are expected to grow at an 8.1% CAGR and reach USD 735.9 billion by 2036.
Senior care product market size, with home buyers now behind most purchases, is estimated at USD 312.4 billion in 2025 and is likely to rise to USD 337.7 billion in 2026. By 2036, FMI analysts expect senior care product sales of USD 735.9 billion, on an 8.1% CAGR. An adoption review shows older adults and family carers buying more products for use at home, as people over 80 stay longer in a private home before moving to a facility. Essity reported 6.6% organic growth in Incontinence Products Retail in the April to June 2026 quarter, mainly from higher volumes, against 2.4% for Incontinence Products Health Care.[1] Pharmacy and supermarket shelves are gaining buyers who once received products through care homes, and brands are widening the shelf for home-use care by placing pants, skin care and nutrition drinks in the same aisle.
Competition is turning on price and on retail shelf space. Essity said in July 2026 that selective price adjustments continued and that cost inflation is being managed through price increases.[1] Abbott reported Adult Nutrition sales of USD 1,119 million for the June quarter, down 3.4%, as lower volumes followed pricing actions from late 2025.[2] Price rises on branded drinks and pads are pushing budget-minded households toward retailer brands. Mid-sized brands without scale or a low-price line face the tightest squeeze, as large brands hold shelf space.
Key Market Trends & Insights
- Demand for oral nutrition drinks, vitamin and mineral combinations, fibre and food thickeners puts nutritional supplements first in 2026, at an expected 41.2%, with consumables near 30.5%.
- Home health care is the likely end user leader in 2026, on 42.4%. Organic growth of 6.6% in Incontinence Products Retail at Essity, faster than in the health care channel, shows home buyers moving to retail shelves.[1]
- Care delivered at home is projected to hold 43.6% of type of care sales in 2026, and chronic illness care about 30.3%.
Regional Highlights
- China has the strongest rate in FMI's country model, 8.3%, faster than the senior care product market average of 8.1%, as 323.38 million people aged 60 and over create the largest group of older buyers.
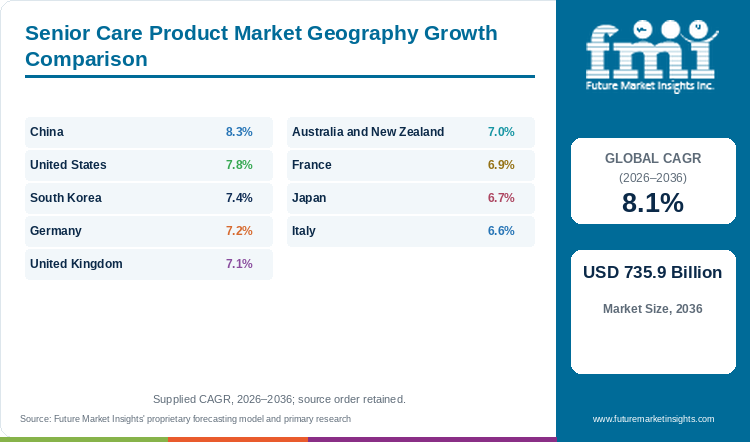
- Next comes the United States on 7.8%. Fast ageing in South Korea gives 7.4%, two-tenths ahead of German home-care buying at 7.2%. Grant-funded home equipment keeps the United Kingdom and Australia and New Zealand near 7%, with France slightly lower at 6.9%. The oldest populations, in Japan and Italy, carry the slowest rates of 6.7% and 6.6%.
- People aged 65 and over in South Korea reached 11.12 million in 2026, or 21.6% of the population, the Ministry of Data and Statistics reported.[3]
Market Size & Forecast
Table 1: Market Size and Forecast for the Senior Care Product Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 312.4 billion |
| Estimated Market Size in 2026 | USD 337.7 billion |
| Projected Market Size by 2036 | USD 735.9 billion |
| CAGR, 2026 to 2036 | 8.1% |
| Added Revenue, 2026 to 2036 | USD 398.2 billion |
| Market Expansion Multiple | 2.2x |
Repeat purchases set the rhythm of senior care product sales. Pads, gloves, dressings and supplements are bought every month, and wheelchairs, beds and commode chairs are bought once and replaced after several years, usually after a reimbursement decision. At-home supply volumes helped Cardinal Health to USD 1,721 million of Other segment sales for April to June 2026, 7% above the prior year, with at-Home Solutions among the growth drivers, and the company has a pending purchase of the Diabetes Health business of AdaptHealth.[4] Devices used in the home are a close adjacent group, and an 8.9% CAGR is forecast for the homecare medical devices market as more treatment moves into the home. FMI analysts expect the senior care product market in 2036 to be 2.2 times the 2026 size, an increase of USD 398.2 billion. Reimbursement cuts are the main risk to this path, since many consumables reach patients through insurer or state budgets.
Reimbursement, Home Care Budgets and Ageing Populations
Public budgets set the pace at which assistive devices reach older people at home. Australia opened the Assistive Technology and Home Modifications scheme within Support at Home on 1 November 2025, with assistive technology tiers of AUD 500, AUD 2,000 and above AUD 15,000 for prescribed needs, and incontinence consumables funded under nursing care.[5] England set the Disabled Facilities Grant budget for 2026/27 at GBP 723 million, GBP 12 million more than the earlier plan.[6] Grant-funded buyers will order walking frames, wheelchairs, hoists and bathroom aids in larger numbers as these budgets are spent.
Population ageing sets the base for consumables. China had 323.38 million people aged 60 and over at the end of 2025, 23% of the population, and 223.65 million aged 65 and over.[7] Japan counted 36.24 million people aged 65 and over in September 2026, a 29.6% share.[8] Larger groups of people over 75 will buy more incontinence products, catheters and nutrition drinks, as daily needs rise with age.
Table 2: Ageing, Funding and Supplier Indicators for the Senior Care Product Market (population, budgets and sales), 2026
| Indicator | Data Point | Relevance | Source |
|---|---|---|---|
| Population aged 60 and over in China, end 2025 | 323.38 million; 23% of population | Largest group of older buyers. | [7] |
| Population aged 65 and over in Japan, September 2026 | 36.24 million; 29.6% of population | Highest share among major countries. | [8] |
| Population aged 65 and over in South Korea, 2026 | 11.12 million; 21.6% of population | Fast entry into a super-aged society. | [3] |
| Disabled Facilities Grant budget in England, 2026/27 | GBP 723 million | Funds home adaptations and aids. | [6] |
| Essity Incontinence Products Retail organic growth, Q2 2026 | 6.6% | Retail buyers adopt products faster. | [1] |
| Abbott Adult Nutrition sales, Q2 2026 | USD 1,119 million; down 3.4% | Price rises cut volume in nutrition. | [2] |
Analyst Perspective
“New care-home beds and other capacity additions are only part of the story. The buyer in the senior care product market is changing from the care home purchasing manager to the daughter or son shopping for a parent who still lives at home. I expect brands that sell continence, nutrition and mobility products through pharmacies and online subscriptions to gain the most ground by 2036. That buyer chooses on comfort, discretion and delivery.”
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the senior care product market segmented?
The market is segmented into product, end user, type of care, and region. Nutritional supplements are expected to lead product sales with 41.2% share in 2026, and home health care leads end user sales with 42.4%.
By product: incontinence products, consumables, assistive devices, and nutritional supplements.
By end user: home health care, nursing care facilities, and hospitals.
By type of care: home care, chronic illness care, and other care types.
By region: older adults, carers and care providers in North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do nutritional supplements lead senior care product sales by product?
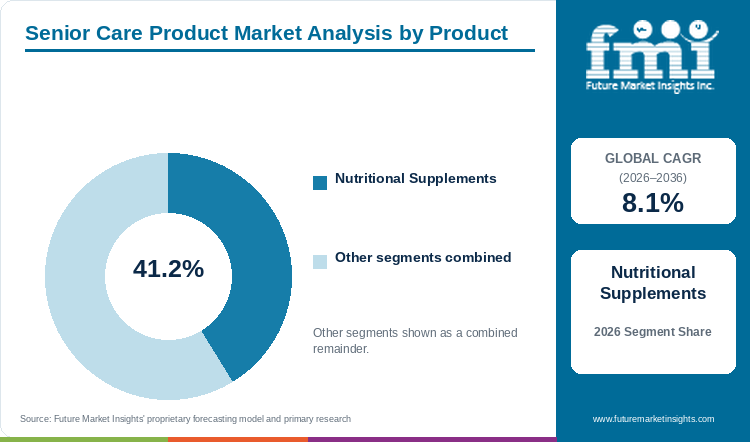
Nutritional supplements are expected to lead product sales with 41.2% share in 2026, ahead of consumables at about 30.5% and assistive devices at roughly 20.1%.
Table 3: Product Share for the Senior Care Product Market (percentage share), 2026
| Product | Estimated Share (2026) |
|---|---|
| Nutritional Supplements | 41.2% |
| Consumables | 30.5% |
| Assistive Devices | 20.1% |
| Incontinence Products | 8.2% |
| Total | 100.0% |
Table 4: Product Leadership and Market Growth for the Senior Care Product Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 8.1% |
| Leading Segment | Nutritional Supplements |
Nutritional supplements hold the product lead, with 41.2% share expected in 2026, as vitamins, fibre and oral nutrition drinks are taken daily by healthy and frail older adults alike. Consumables, about 30.5%, include gloves, masks, dressings, catheters and urine bags that follow clinical need, so the buyer group is smaller. Assistive devices, near 20.1%, are durable canes, wheelchairs, commode chairs and pressure relief mattresses bought once every few years. Incontinence products, an estimated 8.2%, are bought every week at a lower unit price than nutrition drinks. Adult nutrition faced a volume test in 2026, with Abbott reporting a 3.4% fall in Adult Nutrition sales in Q2 2026 after earlier price rises.[2] An older shopper with a fixed budget will keep supplements in the basket, since daily use and pharmacy advice support the habit.
- Vitamin and mineral combinations, dietary fibre, food thickeners and milk powder form the supplement range.
- Pricing actions and new product launches are contributing to improving Nutrition performance, Abbott said in July 2026.[2]
Why does home health care lead senior care product sales by end user?
Home health care is likely to hold 42.4% of end user sales in 2026, with nursing care facilities at about 32.2% and hospitals at roughly 25.4%.
Table 5: End User Share for the Senior Care Product Market (percentage share), 2026
| End User | Estimated Share (2026) |
|---|---|
| Home Health Care | 42.4% |
| Nursing Care Facilities | 32.2% |
| Hospitals | 25.4% |
| Total | 100.0% |
Home health care, at a projected 42.4% share in 2026, leads end user sales, as most older people live in a private home and buy pads, supplements and walking aids for daily use there. Nursing care facilities, an estimated 32.2%, buy in bulk through tenders and serve frailer residents with higher daily needs. Hospitals, near 25.4%, buy catheters, dressings and pressure relief mattresses for short stays, and procurement teams set prices through group contracts. Essity saw stronger organic growth in retail incontinence than in the health care channel during the June quarter.[1] Families caring for a parent at home will keep buying through pharmacies and online stores, and facilities will keep buying through supply contracts.
- Home buyers include older adults living alone, couples and family carers ordering on behalf of a parent.
- Organic growth in Incontinence Products Health Care at Essity was 2.4% in the June quarter, attributed to higher volumes.[1]
Why does home care lead senior care product sales by type of care?
Home care is estimated at 43.6% of type of care sales in 2026, against about 30.3% for chronic illness care and 26.1% for other care types.
Table 6: Type of Care Share for the Senior Care Product Market (percentage share), 2026
| Type of Care | Estimated Share (2026) |
|---|---|
| Home Care | 43.6% |
| Chronic Illness Care | 30.3% |
| Other Care Types | 26.1% |
| Total | 100.0% |
Home care is first by type of care, with 43.6% share expected in 2026, as governments fund support in the home and older people prefer to stay in familiar surroundings. Chronic illness care, about 30.3%, covers diabetes, heart and lung conditions that need monitors, dressings and diet products, and the buyer is often a clinic or pharmacy. Other care types, near 26.1%, cover respite, palliative and post-acute care with shorter stays and smaller product baskets. Australia replaced Home Care Packages with Support at Home on 1 November 2025.[5] Older people leaving hospital will return home with a care plan that lists the products to buy, which keeps home care ahead.
- Home care purchases centre on continence, toileting, bathing and mobility products.
- Support at Home funds walking frames, wheelchairs and hoisting equipment under the Assistive Technology and Home Modifications scheme, the Australian health department said in October 2025.[5]
What are the drivers, restraints, and opportunities in the senior care product market?
Longer lives spent at home keep families and carers buying daily-use products. Reimbursement cuts and price rises squeeze buyers and makers, and retail, online and funded home channels open new sales.
- Driver: Longer lives and a preference for ageing at home raise the number of households buying continence, nutrition and mobility products every month.
- Restraint: Insurers and governments review the price paid for consumables, and cost inflation forces makers to raise prices that some households cannot absorb.
- Opportunity: Funded home programmes and online subscriptions give suppliers direct access to older buyers and family carers.
Ageing at Home Raises Daily Product Use
Consumer preference for staying at home late in life is setting the base for senior care product sales. Japan counted 29.6% of the population at 65 or older in September 2026, and 17.7% at 75 or older.[8] In South Korea, 38% of households headed by older adults were single-person homes in 2026.[3] Older people living alone will buy more products delivered to the door, from pads to nutrition drinks.
Reimbursement Reviews and Cost Inflation Squeeze Makers
Producers of senior care products face payers that cut prices and input costs that rise. Hartmann said in August 2026 that changes in reimbursement policies dampened wound care, that reimbursement changes came into force in France in 2025, and that planned long-term care reform will weigh on 2027 sales.[9] The company expects higher costs for materials, energy and freight in the second half of 2026, only partly offset by pricing.[9] Makers selling mainly through public payers will protect margins by cutting low-value lines, and households will feel the price rises in retail.
Funded Home Programmes and Online Channels Open New Sales
Adoption potential of senior care products is highest in funded home programmes and direct channels. England raised the Disabled Facilities Grant budget to GBP 723 million for 2026/27.[6] Cardinal Health has a pending acquisition of the Diabetes Health business of AdaptHealth, which is built into the fiscal 2027 guidance.[4] Agencies sending carers into homes order supplies for each client, and the home care services market is projected to expand on a 10.5% CAGR. Suppliers selling through home care agencies and subscriptions will reach buyers before a retail shelf does.
Which country CAGRs are profiled in the senior care product market?
Table 7: Country CAGR Comparison for the Senior Care Product Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026 to 2036) |
|---|---|
| China | 8.3% |
| United States | 7.8% |
| South Korea | 7.4% |
| Germany | 7.2% |
| United Kingdom | 7.1% |
| Australia and New Zealand | 7% |
| France | 6.9% |
| Japan | 6.7% |
| Italy | 6.6% |
How do country-level CAGRs compare in the senior care product market?
China had 323.38 million people aged 60 and over at the end of 2025, the largest older population in the table, and China is the only profiled country growing faster than the senior care product market average of 8.1%, at 8.3% per FMI's country model.[7] Ageing markets outside the table, including India, ASEAN and Latin America, carry the global rate above most profiled countries. The United States, at 7.8%, has a large home health channel. South Korea is ageing quickest among the mature markets and grows at 7.4%. Germany and the United Kingdom are almost level, one-tenth of a point apart. Japan and Italy, with the oldest populations, grow slowest from large existing bases.
- Older buyers in China form the largest single group in any country.
- Home delivery and pharmacy channels lead purchases in the United States.
- Super-aged status is arriving fast in South Korea.
- Long-term care reform creates uncertainty for German suppliers.
- Grant-funded home adaptations support British demand.
- Support at Home is changing purchases in Australia and New Zealand.
- Reimbursement cuts from 2025 weigh on prices in France.
- The highest elderly share among major countries gives Japan a large, mature base.
- Family care at home shapes buying in Italy.
Full report country CAGRs cover: China, with 323.38 million people aged 60 and over, is the single country above 8.1% in FMI's full report. The mature markets in the table range from 7.8% for the United States down to 6.6% for Italy, and India, ASEAN, Latin America and Middle East and Africa are covered as faster-growing regional figures.
Country-wise Analysis
China Senior Care Product Market Outlook (2026 to 2036)
Demand for senior care products in China grows with the largest older population of any country. People aged 60 and over reached 323.38 million at the end of 2025, and 53.54 million older people received government subsidies and allowances.[7] Domestic brands sell adult diapers, supplements and mobility aids online at low prices, and city governments are funding home care services. The country table gives China 8.3%, the only rate above the senior care product market average.
Key takeaway: The size and speed of ageing put China first on growth.
United States Senior Care Product Market Outlook (2026 to 2036)
Sales of senior care products in the United States run through pharmacies, distributors and home delivery firms. Cardinal Health reported a 7% sales increase in the Other segment, which includes at-Home Solutions, in the June 2026 quarter.[4] Abbott said new product launches and pricing actions are improving Nutrition performance.[2] Medicare and private insurers pay for many home supplies, which supports a 7.8% CAGR.
Key takeaway: Home delivery firms and pharmacy shelves carry the United States outlook.
South Korea Senior Care Product Market Outlook (2026 to 2036)
South Korea became a super-aged society, with 11.12 million people aged 65 and over in 2026, or 21.6% of the population.[3] The share is expected to reach 30% in 2036.[3] The employment rate for people aged 65 and over was 39.5% in 2025, so many older buyers still have income for supplements and mobility aids.[3] The outlook for South Korea is 7.4%.
Key takeaway: Rapid ageing and working older adults raise buying power in South Korea.
Germany Senior Care Product Market Outlook (2026 to 2036)
German long-term care reform is under discussion, and Hartmann said in August 2026 that planned changes will have a negative impact on 2027 sales and earnings.[9] The company's incontinence growth came from pants and products for moderate to severe incontinence in January to June 2026.[9] Care insurance will keep funding most products for people at home, and a 7.2% rate is likely for Germany.
Key takeaway: Care insurance funding supports German volume, and reform adds price risk.
United Kingdom Senior Care Product Market Outlook (2026 to 2036)
Councils in England fund home adaptations for older and disabled residents through the Disabled Facilities Grant, set at GBP 723 million for 2026/27.[6] Stair chairs, level-access showers and handrails installed under the grant often come with mobility aids and bathroom products. NHS continence services supply pads to many older patients. A 7.1% CAGR follows for the United Kingdom.
Key takeaway: Grant-funded adaptations open product sales in British homes.
Australia and New Zealand Senior Care Product Market Outlook (2026 to 2036)
Australia moved home care funding to Support at Home on 1 November 2025, with separate tiers for assistive technology and home modifications.[5] Assistive technology above AUD 15,000 is available for participants with a prescribed need.[5] New Zealand funds equipment through health and disability services. Growth for Australia and New Zealand is expected to stay near 7%, short of the senior care product market average.
Key takeaway: New tiered funding in Australia guides device orders.
France Senior Care Product Market Outlook (2026 to 2036)
Reimbursement changes in France came into force in 2025, Hartmann reported, which held back wound care sales.[9] French pharmacies sell incontinence and nutrition products to a large retired population, and home nursing services buy dressings and catheters. Lower reimbursed prices keep value growth modest. Value growth in France is expected at 6.9%.
Key takeaway: Reimbursement cuts on dressings keep French growth 1.2 points under 8.1%.
Japan Senior Care Product Market Outlook (2026 to 2036)
Japan has the highest elderly share among major countries, 29.6% in September 2026, and 36.24 million people aged 65 and over.[8] The older population grew by only 20,000 over twelve months, so new buyers are few and growth comes from deeper use per person. Domestic makers sell adult diapers and care foods through drugstores. The FMI country table puts Japan at 6.7%.
Key takeaway: A very large, slow-growing older population keeps Japan steady.
Italy Senior Care Product Market Outlook (2026 to 2036)
Families in Italy often care for older relatives at home, and many households employ live-in carers who buy daily products for the person in care. Regional health services supply continence products and mobility aids through local tenders. Tender prices limit value gains, so Italy is forecast at 6.6%.
Key takeaway: Family care and regional tenders give Italy slow, steady growth.
Who are the notable companies in the senior care product market?
Essity, Kimberly-Clark, Unicharm, Procter & Gamble, Hartmann, Abbott, Invacare, Sunrise Medical, Stryker, Philips, Cardinal Health, McKesson, B. Braun, Mölnlycke, Hollister, Solventum, Flexicare and Marlen are the profiled companies.
Hygiene groups, nutrition makers, device companies and distributors compete for older buyers. FMI profiles eighteen companies across these groups. Essity had group net sales of SEK 35,061 million for April to June 2026, against SEK 34,185 million a year before.[1] Hartmann grew sales to EUR 1,252.0 million in the first half of 2026.[9] Cardinal Health and McKesson distribute consumables and home supplies, and Invacare and Sunrise Medical supply wheelchairs and mobility aids.
- Hygiene and incontinence groups: Essity, Kimberly-Clark, Unicharm, Procter & Gamble and Hartmann.
- Nutrition maker: Abbott.
- Mobility, bed and monitoring makers: Invacare, Sunrise Medical, Stryker and Philips.
- Medical consumable makers and distributors: Cardinal Health, McKesson, B. Braun, Mölnlycke, Hollister, Solventum, Flexicare and Marlen.
Competitive Benchmarking: Senior Care Product Market
Table 8: Competitive Benchmarking for the Senior Care Product Market (qualitative documentation ratings), 2026
| Company | Incontinence Range | Nutrition Range | Home Channel | Recency |
|---|---|---|---|---|
| Essity | High | Low | High | High |
| Hartmann | High | Low | Medium | High |
| Abbott | Low | High | High | High |
| Cardinal Health | Medium | Low | High | High |
| Kimberly-Clark | High | Low | High | Medium |
In the FMI benchmark, each rating follows the number of dated releases and filings found for that company, and no score ranks share.
Key Developments in the Senior Care Product Market
- On 1 October 2026, the Ministry of Data and Statistics reported 11.12 million people aged 65 and over in South Korea.[3]
- On 20 September 2026, Japan reported that people aged 65 and over formed 29.6% of the population.[8]
- On 18 August 2026, Hartmann announced first-half sales of EUR 1,252.0 million and 3.3% organic growth.[9]
- On 11 August 2026, Cardinal Health said at-Home Solutions helped Other segment sales grow 7% in the June quarter.[4]
- On 31 July 2026, the Ministry of Civil Affairs reported 323.38 million people aged 60 and over in China.[7]
- On 16 July 2026, Essity reported 6.6% organic growth in Incontinence Products Retail.[1]
- On 16 July 2026, Abbott put Adult Nutrition sales for the June quarter at USD 1,119 million, 3.4% lower than a year before after price rises cut volume.[2]
- In February 2026, England set the Disabled Facilities Grant budget for 2026/27 at GBP 723 million.[6]
- In October 2025, the Australian health department published the AT-HM scheme guidelines for Support at Home.[5]
Key Players in the Senior Care Product Market
Hygiene and Incontinence Groups
- Essity
- Kimberly-Clark
- Unicharm
- Procter & Gamble
- Hartmann
Nutrition Maker
- Abbott
Mobility, Bed and Monitoring Makers
- Invacare
- Sunrise Medical
- Stryker
- Philips
Medical Consumable Makers and Distributors
- Cardinal Health
- McKesson
- B. Braun
- Mölnlycke
- Hollister
- Solventum
- Flexicare
- Marlen
Senior Care Product Market - Report Scope
Table 9: Report Scope for the Senior Care Product Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product; end user; type of care; region |
| Quantitative units | USD billion |
| Market definition | Products used by and for older adults, including incontinence products, medical consumables, assistive devices such as canes, wheelchairs, commode chairs and pressure relief mattresses, and nutritional supplements, for home health care, nursing care facilities and hospitals. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | United States; Canada; Brazil; Mexico; Argentina; Chile; Germany; France; United Kingdom; Italy; Spain; Benelux; Nordics; Poland; Czech Republic; Romania; Hungary; China; Japan; South Korea; India; ASEAN; Australia and New Zealand; GCC Countries; South Africa; Türkiye; Israel |
| Key companies profiled | Essity, Kimberly-Clark, Unicharm, Procter & Gamble, Hartmann, Abbott, Invacare, Sunrise Medical, Stryker, Philips, Cardinal Health, McKesson, B. Braun, Mölnlycke, Hollister, Solventum, Flexicare, Marlen |
| Forecast period | 2026 to 2036 |
Senior Care Product Market - Research Methodology
Table 10: Research Methodology for the Senior Care Product Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Company results, national statistics on ageing, health department guidelines, housing grant notices and news agency reports from May 2025 onward. |
| Desk Research | Desk research covers population ageing, care funding, reimbursement changes and results from hygiene, nutrition and distribution companies. |
| Market Sizing and Forecasting | Sizing starts from the 2026 base of USD 337.7 billion and the 8.1% CAGR for 2026 to 2036. |
| Data Validation | Population figures, budgets and company results were checked against the issuing agency or company. |
Senior Care Product Market by Segments
Senior Care Product Market segmented by Product:
- Incontinence Products
- Consumables
- Assistive Devices
- Nutritional Supplements
Senior Care Product Market segmented by End User:
- Home Health Care
- Nursing Care Facilities
- Hospitals
Senior Care Product Market segmented by Type of Care:
- Home Care
- Chronic Illness Care
- Other Care Types
Senior Care Product Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Essity Aktiebolag. (2026, July 16). Interim Report Quarter 2, 2026. https://mb.cision.com/Main/15798/4375134/4193962.pdf
- [2] Abbott Laboratories. (2026, July 16). Exhibit 99.1: Abbott reports second-quarter 2026 results (Form 8-K). https://www.sec.gov/Archives/edgar/data/0000001800/000162828026048377/abt-2026q2xexhibitx991.htm
- [3] The Korea Times (Yonhap). (2026, October 1). 1 in 5 South Koreans aged 65 and older in 2026: data. https://www.koreatimes.co.kr/southkorea/20261001/1-in-5-south-koreans-aged-65-and-older-in-2026-data
- [4] Cardinal Health. (2026, August 11). Cardinal Health reports fourth quarter and fiscal year 2026 results and provides fiscal year 2027 guidance. https://s201.q4cdn.com/566741227/files/doc_financials/2026/q4/Q4-FY26-Earnings-Press-Release.pdf
- [5] Department of Health, Disability and Ageing. (2025, October). Assistive Technology and Home Modifications (AT-HM) scheme guidelines, Version 1. https://www.health.gov.au/sites/default/files/2025-10/at-hm-scheme-guidelines.pdf
- [6] Housing LIN. (2026, February 18). Disabled Facilities Grant budget to increase to £723 million in 2026/27. https://www.housinglin.org.uk/News/Disabled-Facilities-Grant-budget-to-increase-to-723-million-in-202627/
- [7] China Daily. (2026, July 31). China's population aged 60 and above reaches 323.38 million. https://global.chinadaily.com.cn/a/202607/31/WS6a6c5c42a310986e2b468665.html
- [8] The Star (Kyodo). (2026, September 20). Japan's elderly population hits a record 29.6 per cent, highest among major nations. https://www.thestar.com.my/aseanplus/aseanplus-news/2026/09/20/japan039s-elderly-population-hits-a-record-296-per-cent-highest-among-major-nations
- [9] PAUL HARTMANN AG. (2026, August 18). January to June 2026: HARTMANN increases sales again. https://corporate.hartmann.info/en/news-media/media-room/2026/press-release-q2-2026
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the senior care product market during 2026?
- What market size is projected by 2036?
- Which product holds notable share?
- Which end user holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the senior care product market expected in 2026?
The 2026 estimate from FMI for the senior care product market is USD 337.7 billion, against USD 312.4 billion in 2025. Senior care product sales are projected to reach USD 735.9 billion by 2036.
What CAGR is projected for the senior care product market through 2036?
An 8.1% CAGR is expected for the senior care product market from 2026 to 2036. Ageing populations and the move toward care at home carry that growth.
Which product holds a notable market share in 2026?
Product sales are led by nutritional supplements, expected at 41.2% share in 2026. Consumables follow at an estimated 30.5%.
Which end user holds a notable market share in 2026?
The leading end user is home health care, likely to hold 42.4% share in 2026. Nursing care facilities follow at an estimated 32.2%.
Which country has a notable expansion outlook through 2036?
China leads the FMI country table with an 8.3% CAGR. The United States follows at 7.8%.
Who are the key companies in the senior care product market?
Hygiene groups lead the profiled set, with Essity, Kimberly-Clark, Unicharm, Procter & Gamble and Hartmann, alongside Abbott in nutrition. Invacare, Sunrise Medical, Stryker, Philips, Cardinal Health, McKesson, B. Braun, Mölnlycke, Hollister, Solventum, Flexicare and Marlen complete the profiled group.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product, 2026 to 2036
- Incontinence Products
- Consumables
- Assistive Devices
- Nutritional Supplements
- Y-o-Y Growth Trend Analysis By Product, 2021 to 2025
- Absolute $ Opportunity Analysis By Product, 2026 to 2036
- Global Market Analysis and Forecast, By End User, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End User, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End User, 2026 to 2036
- Home Health Care
- Nursing Care Facilities
- Hospitals
- Y-o-Y Growth Trend Analysis By End User, 2021 to 2025
- Absolute $ Opportunity Analysis By End User, 2026 to 2036
- Global Market Analysis and Forecast, By Type of Care, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Type of Care, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Type of Care, 2026 to 2036
- Home Care
- Chronic Illness Care
- Other Care Types
- Y-o-Y Growth Trend Analysis By Type of Care, 2021 to 2025
- Absolute $ Opportunity Analysis By Type of Care, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product
- By End User
- By Type of Care
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By End User
- By Type of Care
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product
- By End User
- By Type of Care
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By End User
- By Type of Care
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product
- By End User
- By Type of Care
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By End User
- By Type of Care
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product
- By End User
- By Type of Care
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By End User
- By Type of Care
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product
- By End User
- By Type of Care
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By End User
- By Type of Care
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product
- By End User
- By Type of Care
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By End User
- By Type of Care
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product
- By End User
- By Type of Care
- By Country
- Market Attractiveness Analysis
- By Country
- By Product
- By End User
- By Type of Care
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product
- By End User
- By Type of Care
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product
- By End User
- By Type of Care
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Essity
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Hartmann
- Abbott
- Cardinal Health
- Kimberly-Clark
- Unicharm
- Procter & Gamble
- Invacare
- Sunrise Medical
- Stryker
- Philips
- McKesson
- B. Braun
- Mölnlycke
- Hollister
- Solventum
- Flexicare
- Marlen
- Essity
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


