

- Market Size (2026)
- USD 16.8 Bn
- Forecast (2036)
- USD 34.0 Bn
- CAGR (2026 to 2036)
- 7.3%
How big is Pigeon Pea Market in 2026?
Sales in the pigeon pea market are projected to grow at 7.3% CAGR, with the market size rising from USD 15.7 billion in 2025 to USD 16.8 billion in 2026 and reaching USD 34.0 billion by 2036.
According to Future Market Insights analysis, the global pigeon pea market stands at USD 15.7 billion in 2025 and rises to USD 16.8 billion in 2026. Industry valuation is projected to reach USD 34.0 billion by 2036, expanding at a 7.3% CAGR and generating USD 17.2 billion in added revenue. Growth is underpinned by essential dietary staple requirements across South Asia and East Africa, where commercial processors modernize dal milling to satisfy recurring household protein demand. In June 2025, ICRISAT validated the extreme heat-tolerant cultivar ICPV 25444, which withstood 45 degrees Celsius temperatures across multi-state trials while delivering a 2-tonne-per-hectare yield in a condensed 125-day growing cycle [1]. Dried pigeon peas lead form demand with a 34.0% share in 2026, because whole and split dry grain offers multi-month storage resilience without cold storage. Growth across evaluated economies spans 10.3% in the USA to 11.2% in India, though monsoonal harvest volatility, shipping demurrage, and variable milling recovery rates continue to constrain processor capacity utilization.
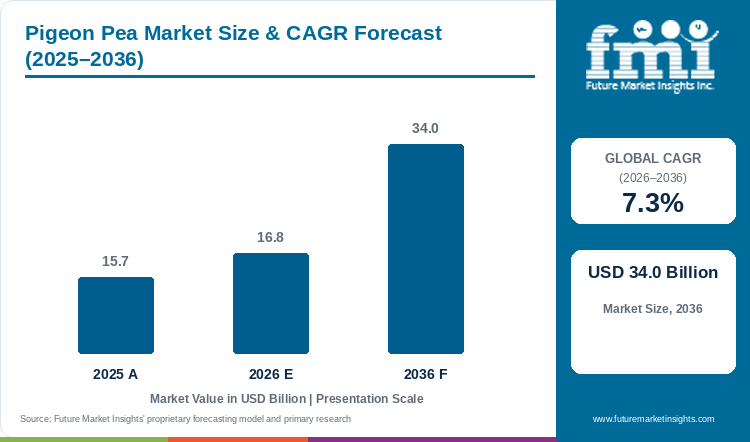
Key Market Trends & Insights
- By form: Dried pigeon peas are projected to account for 34.0% in 2026, supported by shelf stability and established milling demand.
- By distribution channel: Grocery stores are estimated to hold 24.0% in 2026, driven by frequent household purchases of whole and split pigeon peas.
- By processing demand: Split dal and flour formats support wider use across commercial pulse ingredients in packaged foods, snacks, soups, and ready-to-cook meals.
- By supply strategy: Heat-tolerant seeds and expanded import origins are reducing exposure to monsoon-linked production gaps.
Regional Highlights
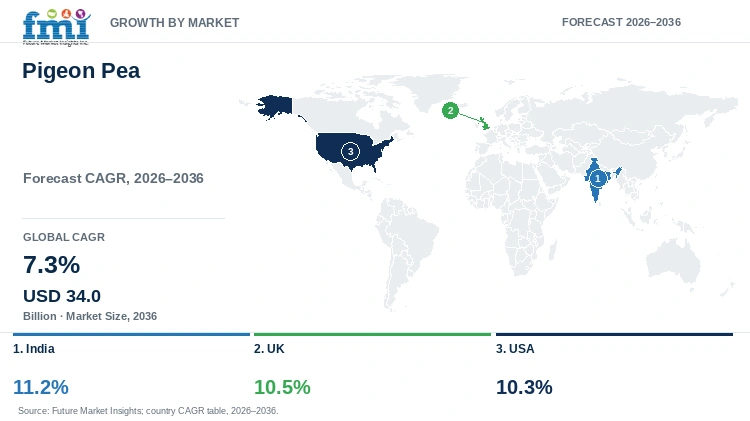
- Fastest-growing evaluated country: India, at 11.2% CAGR from 2026 to 2036.
- The UK follows at 10.5%, while the USA records 10.3% CAGR over the assessment period.
Market Size & Forecast
Table 1: Market Size and Forecast for the Pigeon Pea Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 15.7 billion |
| Estimated Market Size in 2026 | USD 16.8 billion |
| Projected Market Size by 2036 | USD 34.0 billion |
| CAGR, 2026 to 2036 | 7.3% |
| Added Revenue, 2026 to 2036 | USD 17.2 billion |
Country demand conditions differ across regions as domestic crop arrivals and bilateral agricultural import treaties dictate milling margins. FMI research indicates that commercial millers experience margin erosion when uneven grain moisture and foreign matter reduce splitting yields. In March 2026, the Directorate General of Foreign Trade extended India's duty-free import regime for tur and pigeon peas through March 31, 2027 [2]. This regulatory mechanism enables domestic processing plants to balance seasonal kharif harvest deficits with African and South American crop flows, insulating retail markets from acute supply shortages.
Supply, Processing, and Channel Sizing
Table 2: Supply and Commercial Conversion Indicators for the Pigeon Pea Market (USD billion and index values), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 15.7 | 16.8 | 34.0 |
| Dried form revenue (USD billion) | 5.2 to 5.4 | 5.7 | 11.1 to 11.8 |
| Grocery channel revenue (USD billion) | 3.6 to 3.8 | 4.0 | 7.8 to 8.4 |
| Value-add processing index | 100 | 107 | 185 to 200 |
Trade and Production Exposure Sizing
Household consumption provides a dependable baseline demand for pigeon pea, but commercial value realization depends on post-harvest processing efficiency. Raw grain must arrive at standardized moisture levels below 12% to facilitate clean hulling and dehusking. In 2025-26, APEDA reported that India produced 27.4 million tonnes of pulses and exported 1.0 million tonnes valued at USD 1.0 billion [3]. These aggregate flows highlight the extensive commercial infrastructure surrounding the pigeon pea value chain.
Table 3: Trade and Production Exposure Indicators for the Pigeon Pea Market (volume and percentage measures), 2025 to 2026
| Metric | Value | Commercial Meaning |
|---|---|---|
| India pulse production, 2025-26 | 27.4 million tonnes | Broad domestic pulse supply context |
| India pulse exports, 2025-26 | 1.0 million tonnes | Processed and whole-pulse trade base |
| India pulse export value, 2025-26 | USD 1.0 billion | Export channel signal |
| ICPV 25444 trial yield | 2 tonnes per hectare | Higher summer sourcing potential |
Table 4: Segment Revenue and Procurement Indicators for the Pigeon Pea Market (USD billion and percentages), 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 16.8 billion | Report value |
| Dried form revenue, 2026 | USD 5.7 billion | 34.0% share |
| Grocery store revenue, 2026 | USD 4.0 billion | 24.0% share |
| Absolute opportunity, 2026 to 2036 | USD 17.2 billion | Forecast difference |
Analyst Perspective
“Pigeon pea buyers are shifting from seasonal spot procurement toward climate-resilient varieties and diversified origin contracts. Processors that control moisture, grading, and milling consistency will secure dependable retail and food-manufacturing supply agreements.”
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the pigeon pea market segmented?
The pigeon pea market is segmented by form, distribution channel, and region. In 2026, dried pigeon peas lead form demand with 34.0%, while grocery stores represent 24.0% across distribution channels.
- By form: Dried, frozen, canned, and fresh.
- By distribution channel: Grocery stores, supermarkets, direct stores, and online.
Why do dried pigeon peas lead the form category?
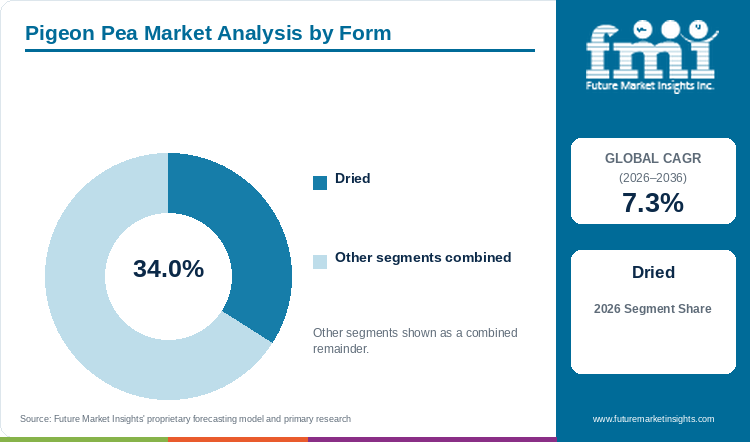
Dried pigeon peas represent 34.0% of form revenue in 2026, balancing storage life with established milling and cooking demand.
Table 5: Form Share for the Pigeon Pea Market (percentage share), 2026
| Form | Share (2026) |
|---|---|
| Dried | 34.0% |
| Other Forms Combined | 66.0%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment share from 100.0%.
Table 6: Form Leadership and Market Growth for the Pigeon Pea Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.3% |
| Leading Segment | Dried pigeon peas |
Dried pigeon peas command 34.0% of form revenue because desiccated pulses provide superior storage endurance across non-refrigerated warehouse channels. Commercial millers store dried whole grain for multi-month processing cycles, applying water conditioning and oil tempering to separate the seed coat efficiently. In addition, dried pulse flour is increasingly incorporated into plant based protein extrudates and fortified baked goods. However, old grain stock can develop hard-to-cook defects that extend boiling times.
- Dried pigeon peas are projected to hold 34.0% of form demand in 2026, underpinned by year-round storage and split-dal processing.
- ICRISAT demonstrated a heat-tolerant cultivar in 2025 that supports wider seasonal production windows.
What supports grocery stores as the preferred distribution channel?
Grocery stores hold 24.0% of distribution revenue in 2026, supported by frequent household replenishment and familiar pack formats.
Traditional grocery stores and neighborhood kirana shops account for 24.0% of channel turnover as consumers purchase dal in frequent, localized quantities. Proximity to residential neighborhoods and bulk loose grain dispensing make local grocers difficult to displace. While modern supermarket banners expand packaged pulse selections, grocery stores maintain strong consumer trust through visual grain inspection. Emerging consumer demand for certified organic foods encourages grocers to stock transparently sourced, unpolished pigeon pea packs.
- Grocery stores are estimated to hold 24.0% in 2026, driven by household access and repeat purchases.
- Retail growth depends on reliable cleaning, grading, packaging integrity, and origin documentation.
What are the drivers, restraints, and opportunities in the pigeon pea market?
Plant-protein demand and public procurement support volume, while weather-linked supply swings constrain availability, and heat-tolerant varieties widen cultivation options.
- Driver: Routine dal consumption and wider plant-protein use support recurring household and food-processing demand.
- Restraint: Monsoon variability, import dependence, and inconsistent post-harvest handling create price and quality volatility.
- Opportunity: Heat-tolerant varieties and new import origins can extend supply windows and improve processor utilization.
Growth Analysis and Future Potential: Climate-Resilient Supply Catalysts
Pigeon pea procurement is transitioning from seasonal reliance toward climate-resilient breeding innovations. Cultivar ICPV 25444 introduces a summer production window because its thermo-insensitive genetics mature in 125 days under severe heat. In July 2025, ICRISAT held multi-stakeholder field demonstrations across Karnataka, showcasing uniform summer crop performance [4]. Commercial dal millers that contract summer harvests can operate processing equipment across off-season months, reducing capital depreciation.
Risk Assessment of the Pigeon Pea Market: Weather and Post-Harvest Friction
Monsoon irregularities represent the foremost operational vulnerability across the pigeon pea supply chain. Unseasonal rains during late pod-filling stages cause fungal pod rot and field sprouting, resulting in darkened seed coats that trade at steep commercial discounts. Import volumes from Myanmar, Mozambique, and Tanzania mitigate domestic deficits, but cross-border freight volatility and phytosanitary clearance delays create working capital strain for importers distributing formulated foods raw materials.
Commercial Opportunity Analysis: Value-Added Formats and Origin Diversification
Value addition creates compelling commercial opportunities for pulse processors expanding into precision-graded split dal, instant-cooking dehulled peas, and protein-rich flours. In the FMI report, food manufacturers incorporate de-flavored pigeon pea flour into extruded snack foods, noodles, and ready-to-eat stews. Processors investing in optical color sorters and vacuum-sealed retail packaging capture premium margins across export markets.
Pigeon Pea Market by Country (2026 to 2036)
As per Future Market Insights, India represents the fastest-growing pigeon pea market among the three reported countries, at 11.2% CAGR from 2026 to 2036. Across covered economies, commercial success depends on sourcing resilience, product familiarity, and reliable import logistics.
Table 7: Country CAGR and Primary Growth Levers for the Pigeon Pea Market (CAGR percentage and commercial drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| India | 11.2% | Dal consumption, procurement support, and import-linked supply balancing |
| UK | 10.5% | Ethnic retail demand and plant-protein adoption |
| USA | 10.3% | Specialty grocery growth and pulse-based food formulation |
Source: Future Market Insights analysis
India Pigeon Pea Market Outlook (2026 to 2036)
India leads global demand with an 11.2% CAGR through 2036, as pigeon pea represents the primary culinary foundation for daily dal consumption across hundreds of millions of households. Government minimum support price procurement and duty-free import mechanisms ensure steady mill throughput during domestic harvest shortfalls. However, traditional unorganized processing leads to high splitting breakage that erodes miller margins. Modern processors deploy automated de-stoning and rubber-roller dehullers to maximize recovery.
Key takeaway: In India, staple consumption and public supply measures support rapid growth, while processors prioritize dependable origin diversification.
UK Pigeon Pea Market Outlook (2026 to 2036)
The United Kingdom is expanding at a 10.5% CAGR through 2036, anchored by large South Asian, Caribbean, and West African communities in London, Birmingham, and Manchester. Demand shifts toward convenient canned pigeon peas and retort-packaged curried meals that cater to second-generation diaspora lifestyles. Importers must comply with stringent UK Food Standards Agency maximum residue limits for pesticides, favoring suppliers with audited origin traceability.
Key takeaway: In the UK, ethnic retail depth supports demand, while traceability and diversified imports determine supplier acceptance.
USA Pigeon Pea Market Outlook (2026 to 2036)
The United States is projected to record a 10.3% CAGR over the assessment period, driven by Caribbean culinary traditions in New York and Florida, alongside mainstream interest in the wider plant-protein category. Food formulators test pigeon pea starch and protein concentrates for gluten-free snack development. Expanding commercial distribution beyond specialty Hispanic and Asian bodegas requires consumer education and recipe integration.
Key takeaway: In the USA, specialty food demand provides the entry point, while ingredient standardization can widen commercial adoption.
Full report country coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Who are the notable companies in the pigeon pea market?
Olam Agri, ITC Limited, Sun Impex, Interamsa Agroindustrial SAC, Unitex Tanzania Limited, Taj Foods, and selected regional pulse processors are notable participants in this market.
Competition across the pigeon pea landscape connects agricultural origin aggregation with industrial cleaning, splitting, and branded retail distribution. Global agribusiness platforms manage international maritime pulse supply, while regional millers optimize local dal grades to match consumer culinary preferences.
- Global and Integrated Agribusiness: Olam Agri and ITC Limited provide sourcing, processing, and distribution capability across agricultural value chains.
- Pulse Export and Trading Specialists: Sun Impex, Interamsa Agroindustrial SAC, and Unitex Tanzania Limited support cross-border pulse supply.
- Branded and Regional Food Platforms: Taj Foods and local dal processors convert pigeon peas into retail and convenience formats.
Competitive Benchmarking: Pigeon Pea Market
Table 8: Competitive Benchmarking for the Pigeon Pea Market (qualitative capability ratings), 2026
| Company | Origin Sourcing | Processing Depth | Retail / Ingredient Access | Geographic Reach |
|---|---|---|---|---|
| Olam Agri | High | High | High | High |
| ITC Limited | High | High | High | Medium |
| Sun Impex | High | Medium | High | High |
| Interamsa Agroindustrial SAC | Medium | Medium | Medium | Medium |
| Unitex Tanzania Limited | High | Medium | Medium | Medium |
| Taj Foods | Medium | High | High | Medium |
Scoring basis: High indicates broad public evidence of capability across the named dimension. Medium indicates a narrower regional or format focus. Ratings are qualitative and do not represent financial rankings.
Key Developments in the Pigeon Pea Market
- In March 2026, India extended the duty-free import policy for tur and pigeon peas through March 31, 2027 to ensure domestic price stability.
- In July 2025, ICRISAT and regional agricultural partners demonstrated successful summer pigeon pea cultivation across southern India.
- In June 2025, heat-tolerant cultivar ICPV 25444 completed multi-location trials, exhibiting 45-degree heat tolerance and 2-tonne-per-hectare yield.
- In 2025-26, India achieved 27.4 million tonnes of total pulse production, sustaining robust domestic processing activity.
Key Players in the Pigeon Pea Market
Integrated Agribusiness and Processing
- Olam Agri
- ITC Limited
Pulse Trading and Export Platforms
- Sun Impex
- Interamsa Agroindustrial SAC
- Unitex Tanzania Limited
Branded and Regional Food Suppliers
- Taj Foods
- Regional dal millers and grocery packers
Pigeon Pea Market - Report Scope
Table 9: Report Scope for the Pigeon Pea Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Form; Distribution Channel; Region |
| Quantitative units | USD Billion |
| Market definition | Revenue from production, processing, and trade of whole, split, flour, fresh, frozen, canned, and dried pigeon peas. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries highlighted | India, UK, USA |
| Key companies covered | Olam Agri, ITC Limited, Sun Impex, Interamsa Agroindustrial SAC, Unitex Tanzania Limited, Taj Foods |
| Forecast period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation |
Pigeon Pea Market - Research Methodology
Table 10: Research Methodology for the Pigeon Pea Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Interviews with growers, aggregators, millers, exporters, importers, distributors, retailers, food processors, and sector experts validate demand, pricing, quality, and purchasing decisions. |
| Secondary Research | Sources include annual reports, investor presentations, regulatory publications, agricultural agencies, technical papers, trade journals, company websites, product literature, and public datasets. |
| Market Sizing and Forecasting | Top-down and bottom-up approaches assess revenue, processing demand, channel shares, trade exposure, and adoption from 2026 to 2036. |
| Data Triangulation and Validation | Data is validated against crop production, trade policy, consumption patterns, corporate developments, and historical trends to improve consistency. |
Pigeon Pea Market by Segments
Pigeon Pea Market segmented by Form:
- Dried
- Frozen
- Canned
- Fresh
Pigeon Pea Market segmented by Distribution Channel:
- Grocery Stores
- Supermarkets
- Direct Stores
- Online
Pigeon Pea Market by Region
- North America: United States, Canada, Mexico
- Latin America: Brazil, Chile, Rest of Latin America
- Western Europe: Germany, UK, Italy, Spain, France, Nordics, Benelux
- Eastern Europe: Poland, Romania, Rest of Eastern Europe
- East Asia: Japan, South Korea
- South Asia and Pacific: India, ASEAN, Australia and New Zealand
- Middle East and Africa: GCC Countries, East Africa, Southern Africa, Rest of MEA
Research Sources and Bibliography
- [1] International Crops Research Institute for the Semi-Arid Tropics. (2025, June 9). Breakthrough at ICRISAT: World’s first extreme heat-tolerant pigeonpea developed via speed breeding.
- [2] Directorate General of Foreign Trade. (2026, March 31). Extension in free import policy of tur/pigeon peas through March 31, 2027.
- [3] Agricultural and Processed Food Products Export Development Authority. (2026). Pulses: Production and export overview, 2025-26.
- [4] International Crops Research Institute for the Semi-Arid Tropics. (2025, July 29). A season redefined: Farmers and scientists unite to pioneer summer pigeonpea cultivation.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the pigeon pea market in 2026 and what is forecast for 2036?
- Which climate and procurement pressures shape pigeon pea demand?
- Why do dried pigeon peas lead the form category?
- Why do grocery stores remain the largest distribution channel?
- How do growth rates differ across India, the UK, and the USA?
- Which companies participate across sourcing, processing, and distribution?
- What limits supplier reliability and product consistency?
- What should buyers assess before contracting pigeon pea supply?
Frequently Asked Questions
How big is the pigeon pea market in 2026, and what is forecast for 2036?
Future Market Insights estimates the global market will reach USD 16.8 billion in 2026. Sector valuation is projected to expand to USD 34.0 billion by 2036.
What is the CAGR forecast for the pigeon pea market from 2026 to 2036?
As per FMI, the market is projected to expand at a 7.3% CAGR over the assessment period. Expansion is supported by daily staple consumption, public procurement programs, and expanding crop breeding resilience.
Which form segment leads the pigeon pea market?
Dried pigeon peas lead the form category with a 34.0% share in 2026. Whole and split dry pulses provide ambient storage stability and established dal milling infrastructure.
Which distribution channel accounts for the largest share of market activity?
Grocery stores represent 24.0% of channel turnover in 2026. Proximity to residential households and visual grain grading support high repeat neighborhood purchases.
Which country has the strongest expansion outlook during the forecast period?
India is projected to register an 11.2% CAGR from 2026 to 2036. Demand is fueled by massive daily dal consumption and government minimum support price frameworks.
Who are the prominent companies active in the pigeon pea landscape?
Significant participants include Olam Agri, ITC Limited, Sun Impex, Interamsa Agroindustrial SAC, Unitex Tanzania Limited, and Taj Foods. Market participants focus on supply diversification, origin cleaning, and standardized split dal processing.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Form, 2026 to 2036
- Dried
- Frozen
- Canned
- Fresh
- Y-o-Y Growth Trend Analysis By Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Form, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Grocery Stores
- Supermarkets
- Direct Stores
- Online
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- Mexico
- By Form
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Chile
- Rest of Latin America
- By Form
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordics
- Benelux
- By Form
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Romania
- Rest of Eastern Europe
- By Form
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- By Form
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Form
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- East Africa
- Southern Africa
- Rest of MEA
- By Form
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Form
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Distribution Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Form
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Form
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Olam Agri
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- ITC Limited
- Sun Impex
- Interamsa Agroindustrial SAC
- Unitex Tanzania Limited
- Taj Foods
- Regional dal millers and grocery packers
- Olam Agri
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


