

- Market Size (2026)
- USD 21.0 Bn
- Forecast (2036)
- USD 32.3 Bn
- CAGR (2026 to 2036)
- 4.4%
How big is Food and Beverage Microalgae Market in 2026?
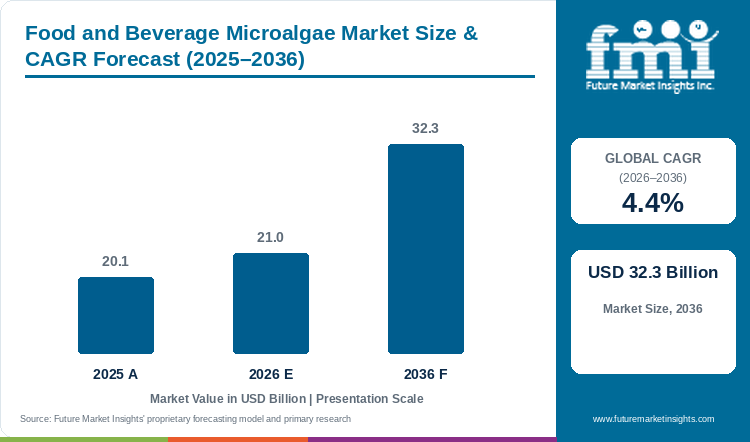
Sales in the food and beverage microalgae market are projected to grow at 4.4% CAGR, with the market size rising from USD 20.1 billion in 2025 to USD 21.0 billion in 2026 and reaching USD 32.3 billion by 2036.
Neutralizing grassy sulfur volatiles while keeping heat-sensitive phycocyanin and omega-3 lipids stable in acidic ready-to-drink formulations defines the commercial trajectory for aquatic biomass ingredients. Global food and beverage microalgae revenue moves from USD 20.1 billion in 2025 to USD 21.0 billion in 2026 and reaches USD 32.3 billion by 2036, reflecting a 4.4% CAGR and USD 11.3 billion in incremental value over the ten-year period. In June 2026, the Food and Agriculture Organization reported that world algae harvesting reached 40.0 million tonnes, up 5.8% year-on-year [1]. Flavored and botanical infusions account for 51.2% of 2026 demand as beverage packers combine cultivated microalgae biomass with cold-pressed citrus and ginger extracts.
Key Market Trends & Insights
- By product variety: Flavored and botanical infusions capture 51.2% of 2026 demand, as cold-pressed ginger, lemon, and yuzu oils neutralize earthy dimethyl sulfide notes in ready-to-drink tonics.
- By packaging format: Slim aluminum cans generate 41.1% of 2026 sales because opaque metal walls block ultraviolet light and prevent chlorophyll and phycocyanin photo-oxidation inside illuminated retail coolers.
- By distribution channel: Supermarkets and hypermarkets command 37.7% of 2026 revenue through front-of-store grab-and-go beverage chillers and dedicated plant-based grocery aisles.
Regional Highlights
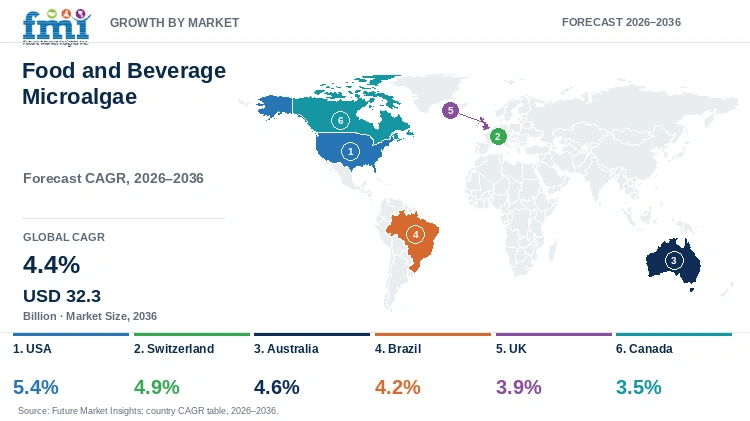
- Fastest-growing evaluated country: The USA, at 5.4% CAGR from 2026 to 2036.
- By country: Switzerland at 4.9%, Australia at 4.6%, Brazil at 4.2%, and the UK at 3.9% follow, while Canada records the lowest evaluated CAGR at 3.5%.
Market Size & Forecast
Table 1: Market Size and Forecast for the Food and Beverage Microalgae Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 20.1 billion |
| Estimated Market Size in 2026 | USD 21.0 billion |
| Projected Market Size by 2036 | USD 32.3 billion |
| CAGR, 2026 to 2036 | 4.4% |
| Added Revenue, 2026 to 2036 | USD 11.3 billion |
Fast-track GRAS ingredient notifications in the United States and hydro-powered indoor photobioreactor investments in Switzerland accelerate novel algal beverage launches, whereas European Union novel-food dossiers and sub-zero Canadian winters dictate regional cultivation and import strategies. Beverage quality teams enforce strict batch screening for heavy metals, pheophorbide, and cyanobacterial microcystins before clearing open-pond biomass for ready-to-drink bottling lines. In February 2025, the European Algae Biomass Association reported that certified food-grade spirulina and chlorella shipments grew 6.4% across commercial beverage blenders and dairy-alternative plants [2]. Drink formulators are shifting procurement toward enclosed-bioreactor milled spirulina powder to guarantee rapid cold-water dispersion and clean flavor across supermarket perimeter coolers, organic grocers, and convenience chains.
Biomass Cultivation and Beverage Incorporation Sizing
Table 2: Biomass Cultivation and Beverage Incorporation Sizing for the Food and Beverage Microalgae Market (USD billion, thousand tonnes, and grams), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 20.1 | 21.0 | 32.3 |
| Food-grade dry microalgae volume (thousand tonnes) | 68.0 to 75.0 | 71.5 to 79.0 | 112.0 to 125.0 |
| Average inclusion rate per 250ml functional drink (grams) | 1.5 to 3.0 | 1.6 to 3.2 | 2.2 to 4.0 |
| Biomass ingredient cost per thousand liters (USD) | 185.0 to 230.0 | 180.0 to 225.0 | 150.0 to 190.0 |
Operational note: Volume and dosing ranges reflect food-grade Arthrospira (spirulina), Chlorella vulgaris, Schizochytrium, and Haematococcus pluvialis fractions incorporated into commercial foods and beverages.
Per Capita & Retail Chiller Sizing
Keeping microalgal cells suspended inside low-viscosity fruit waters and plant milks requires high-pressure homogenization so cell-wall fragments do not settle at the bottom of retail cans. Because Arthrospira and Chlorella supply complete essential amino acids alongside non-heme iron, grocery wellness buyers are expanding chiller facings for single-serve algal tonics and protein smoothies. Recurring reorders from urban supermarkets and gym hydration counters now anchor multi-year supply agreements for de-odorized spirulina and pale chlorella isolates.
Table 3: Per Capita and Household Spending Indicators for the Food and Beverage Microalgae Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Spend per capita (USD) | 2.45 | 2.53 | 3.59 |
| Spend per 1,000 people (USD) | 2,451.2 | 2,530.1 | 3,588.9 |
| Annual spend per active functional-drink buyer (USD) | 64.0 to 78.0 | 66.5 to 81.0 | 92.0 to 114.0 |
Table 4: Channel & Format Revenue Indicators for the Food and Beverage Microalgae Market (USD billion and percentages), mixed reporting years from 2024 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 21.0 billion | Report value |
| Flavored / botanical infusion revenue, 2026 | USD 10.8 billion | 51.2% share |
| Slim aluminum cans revenue, 2026 | USD 8.6 billion | 41.1% share |
| Supermarkets & hypermarkets revenue, 2026 | USD 7.9 billion | 37.7% share |
Analyst Perspective
"Beverage R&D teams no longer treat microalgae purely as a green smoothie powder; heterotrophic fermentation of pale, chlorophyll-free chlorella is opening mainstream dairy alternatives and clear functional waters, provided cultivators lock in long-term power agreements to manage bioreactor electricity costs."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the food and beverage microalgae market segmented?
The food and beverage microalgae market is segmented by product variety, packaging format, distribution channel, and region. In 2026, flavored and botanical infusions are projected at 51.2%, slim aluminum cans at 41.1%, and supermarkets and hypermarkets at 37.7%.
By product variety: Flavored / botanical infusion, classic unflavored / traditional, and zero-sugar / sugar-free variant.
By packaging format: Slim aluminum cans, PET bottles, glass bottles, and aseptic paperboard cartons.
By distribution channel: Supermarkets & hypermarkets, convenience stores & gas stations, online retail & subscription, and food service & cafes.
Why do Flavored / Botanical Infusions lead the product variety category?
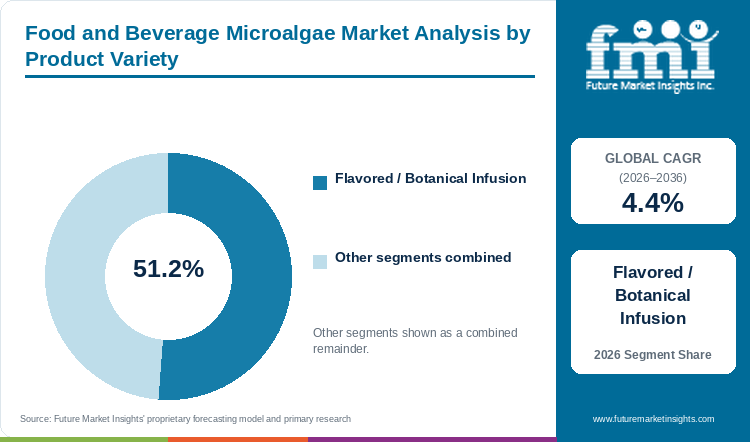
Flavored and botanical infusions account for 51.2% of product variety revenue in 2026, supported by citrus masking of algal notes.
Table 5: Product Variety Share for the Food and Beverage Microalgae Market (percentage share), 2026
| Product Variety | Share (2026) |
|---|---|
| Flavored / Botanical Infusion | 51.2% |
| Other Segments Combined | 48.8%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Product Variety Leadership and Market Growth for the Food and Beverage Microalgae Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 4.4% |
| Leading Segment | Flavored / Botanical Infusion |
Raw Arthrospira and Chlorella cell suspensions release volatile hexanal and dimethyl sulfide compounds during thermal pasteurization, making unmasked algal drinks unpalatable to mainstream grocery shoppers. Blending micro-filtered algal fractions with cold-pressed ginger, lemon, passionfruit, and yuzu oils neutralizes marine off-notes while preserving antioxidant activity across refrigerated shelf life. Citrus and botanical terpene pairing enables beverage formulators to dose higher concentrations of liquid spirulina extracts into sparkling wellness tonics and 60ml immunity shots without bitter astringency. Unflavored algal powders remain largely restricted to home smoothie blenders, leaving botanical infusions as the primary revenue generator in retail beverage coolers.
- Flavored and botanical infusions are projected to hold 51.2% of product variety demand in 2026, supported by organic acid and terpene masking of volatile marine off-flavors.
- In March 2025, Algae Biomass Organization consumer sensory panels reported that citrus-and-ginger botanical pairing raised repeat purchase intent for spirulina drinks by 34.0% over unflavored formats [3].
What makes Slim Aluminum Cans central to the packaging format category?
Slim aluminum cans represent 41.1% of the packaging format category in 2026, reflecting ultraviolet barrier protection against pigment oxidation.
Chlorophyll, phycocyanin, and carotenoid chromophores degrade rapidly under supermarket LED chiller lighting, prompting ready-to-drink microalgae brands to standardize around 250ml slim aluminum cans. Clear polyethylene terephthalate bottles permit photo-oxidation that turns vibrant blue-green tonics dull olive-brown within weeks, whereas opaque aluminum walls block 100% of light transmission and stop oxygen ingress. Nitrogen-dosed canning lines also protect delicate refined algae oil omega-3 emulsions against lipid peroxidation during ambient warehouse transit. Higher municipal metal recycling rates and lighter pallet shipping weights compared with glass bottles further reinforce slim cans as the preferred beverage pack.
- Slim aluminum cans are estimated to capture 41.1% of packaging format revenue in 2026, reflecting hermetic oxygen sealing and total protection against light-induced pigment fading.
- In October 2025, a National Center for Biotechnology Information evaluation of commercial spirulina and chlorella products confirmed that light-proof hermetically sealed packaging retained 94.0% of phycobiliprotein activity over six months [4].
What supports Supermarkets & Hypermarkets leadership within the distribution channel category?
Supermarkets and hypermarkets capture 37.7% of distribution channel demand in 2026, driven by dedicated grab-and-go functional beverage chillers.
Eye-level placement inside open-air produce and grab-and-go perimeter chillers allows supermarkets and hypermarkets to capture weekly household beverage traffic that specialty vitamin shops cannot match. Grocery category managers allocate dedicated cold-vault facings to plant-based functional shots, kombucha-algae blends, and DHA-fortified oat milks alongside fresh juices. Private-label retail teams increasingly contract processors of food-grade chlorella to manufacture store-brand green smoothie pouches, immunity shots, and protein snack bars. Direct-to-consumer e-commerce moves high-margin powder canisters, yet brick-and-mortar grocery chains generate the highest unit velocity and trial volume for ready-to-drink formats.
- Supermarkets and hypermarkets are anticipated to contribute 37.7% of distribution channel sales in 2026, owing to nationwide cold-chain produce-aisle placement and multi-pack promotional pricing.
- In May 2025, Food Marketing Institute retail scanner tracking showed that refrigerated plant-based functional beverages posted 9.8% year-on-year unit growth across supermarket perimeter coolers [5].
What are the drivers, restraints, and opportunities in the food and beverage microalgae market?
In the food and beverage microalgae market, high amino-acid digestibility and vegan DHA demand support adoption, closed photobioreactor capital and power costs constrain commodity pricing, and heterotrophic pale chlorella strains expand neutral-color food fortification through 2036.
- Driver: High protein digestibility scores and marine-free long-chain omega-3 content pull microalgal fractions into mainstream vegan drinks and snacks.
- Restraint: Intensive capital expenditure and artificial lighting power loads in closed photobioreactors keep food-grade algal biomass prices well above soy or pea isolates.
- Opportunity: Sugar-fed heterotrophic fermentation of chlorophyll-deficient white and yellow microalgae unlocks fortification in dairy alternatives and baked goods without green tinting.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Complete essential amino acid profiles, bioavailable non-heme iron, and marine-free docosahexaenoic acid (DHA) are pulling microalgal fractions into mainstream vegan beverages and savory snacks. Unlike terrestrial oilseeds that lack long-chain omega-3 fatty acids, Schizochytrium and disrupted Chlorella strains supply bioactive lipids and peptides without harvesting wild pelagic fish stocks. In December 2025, a National Center for Biotechnology Information study demonstrated that enzymatic Spirulina platensis protein hydrolysates achieved 89.5% gastrointestinal digestibility alongside strong radical-scavenging activity [6]. Beverage marketers pairing algal DHA with algae-based supplement formulations secure recurring distribution across natural grocery chains and pharmacy wellness aisles.
Risk Assessment of the Food and Beverage Microalgae Market: Operational and Formulation Friction
Tubular photobioreactor capital depreciation and continuous centrifugal dewatering electricity loads keep food-grade microalgal biomass significantly more expensive per kilogram than commodity soy or pea protein isolates. Open raceway ponds cost less to construct but suffer seasonal temperature swings and airborne ciliate or cyanotoxin contamination, compelling beverage-grade buyers to specify enclosed cultivation. In July 2025, International Association of Aquaculture Engineering cost audits showed that closed glass and acrylic photobioreactors required 4.6 times higher capital investment per hectare than open raceways, with harvesting and spray-drying consuming 32.0% of operating budgets [7]. Incorporating raw cultured chlorella vulgaris above two percent weight also triggers green pigment bleed and sediment fallout.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Cultivating non-GMO chlorophyll-deficient Chlorella strains heterotrophically inside dark stainless-steel fermenters fed on dextrose bypasses both sunlight bottlenecks and dark-green color barriers. Enclosed sugar-fed fermentation raises cell density nearly tenfold over sunlit ponds while yielding neutral-tasting pale-ivory and golden flours containing up to 60.0% protein. In August 2025, International Union of Food Science and Technology pilot trials confirmed that pale heterotrophic chlorella flour replaced egg-white binders in brioche and plant-based yogurt at a 5.0% inclusion rate without altering color or mouthfeel [8]. Biorefineries also co-extract natural astaxanthin antioxidants for sports hydration drinks and recovery shots through 2036.
Food and Beverage Microalgae Market by Country (2026 to 2036)
Across the six evaluated countries, expansion between 2026 and 2036 ranges from 3.5% CAGR in Canada to a leading 5.4% CAGR in the United States, followed by Switzerland at 4.9% and Australia at 4.6%. National trajectories depend on how beverage and dairy-alternative producers navigate FDA GRAS and European novel-food clearances, refrigerated grocery cabinet access, and closed-bioreactor energy and water-recycling economics.
Table 7: Country CAGR and Primary Growth Levers for the Food and Beverage Microalgae Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| USA | 5.4% | FDA GRAS clearances for novel Chlorella strains and natural-grocery functional shot velocity |
| Switzerland | 4.9% | FSVO novel-food approvals and hydro-powered alpine photobioreactor cultivation |
| Australia | 4.6% | Closed membrane-recycled aquaculture and sports hydration retail demand |
| Brazil | 4.2% | High equatorial solar irradiance and tropical acai-spirulina beverage blending |
| UK | 3.9% | Mainstream supermarket plant-based meal deals and algal DHA oat-drink fortification |
| Canada | 3.5% | Health Canada novel-food authorizations and waste-heat indoor bioreactor operations |
Source: Future Market Insights analysis
USA Food and Beverage Microalgae Market Outlook (2026 to 2036)
Regulatory momentum under the U.S. Food and Drug Administration's Generally Recognized as Safe (GRAS) notification program gives American beverage and bakery formulators rapid access to novel microalgal ingredients. In September 2026, the U.S. Food and Drug Administration updated its GRAS Notice Inventory covering Chlorella vulgaris, Chlorella sorokiniana, and phycocyanin water extracts for use in breads, nutrition bars, and functional drinks [9]. Supported by wide refrigerated shelf space in Whole Foods, Sprouts, and mainstream grocers, the U.S. market is projected to expand at a leading 5.4% CAGR through 2036. High slotting fees for refrigerated grocery doors still challenge emerging beverage brands, pushing startups toward shelf-stable nitrogen-dosed slim cans.
Key takeaway: In the USA, rapid FDA GRAS clearances for novel Chlorella strains and nitrogen-dosed slim can distribution allow beverage brands to bypass refrigerated slotting bottlenecks.
Switzerland Food and Beverage Microalgae Market Outlook (2026 to 2036)
Preventive alpine nutrition habits and strict chemical-free purity standards underpin a 4.9% CAGR in Switzerland through 2036, as consumers purchase organic chlorella elixirs and phycocyanin-tinted botanical waters across Coop Vitality, Migros, and pharmacy wellness counters. In October 2025, the Swiss Federal Food Safety and Veterinary Office issued updated safety authorizations for cultivated microalgal food fractions aligned with European novel-food registers [10]. Because high Swiss industrial wages and mountain winter heating costs penalize open pond cultivation, domestic biotech producers operate compact indoor LED photobioreactors powered by certified hydroelectric energy.
Key takeaway: In Switzerland, hydro-powered indoor LED photobioreactors enable domestic cultivators to supply contaminant-free organic chlorella elixirs despite sub-zero alpine winters.
Australia Food and Beverage Microalgae Market Outlook (2026 to 2036)
Outdoor endurance sports culture and high solar hours across northern and western states shape the microalgae sector in Australia, where consumers buy spirulina-infused electrolyte waters and recovery smoothie bowls year-round. In November 2025, Complementary Medicines Australia reported a 7.2% increase in domestic demand for quality-audited marine and freshwater algal nutritional products across retail pharmacies and health stores [11]. Market revenue in Australia is forecast to advance at a 4.6% CAGR from 2026 to 2036. However, recurring inland freshwater restrictions and high evaporation rates make traditional open-pond farming difficult, compelling Australian cultivators to install closed tubular reactors with 95.0% ultrafiltration water recycling.
Key takeaway: In Australia, closed tubular reactors equipped with 95% ultrafiltration water recycling insulate spirulina electrolyte-drink suppliers against inland drought restrictions.
Brazil Food and Beverage Microalgae Market Outlook (2026 to 2036)
Brazil benefits from year-round tropical photoperiods and warm coastal temperatures in the Northeast, allowing commercial aquaculture operators to achieve high annual biomass yields without winter heating. Domestic beverage processors blend spray-dried spirulina into ready-to-drink acai, guarana, and passionfruit energy drinks sold across urban gyms and supermarkets in Sao Paulo and Rio de Janeiro. In December 2025, World Aquaculture Society regional production audits recorded an 8.5% rise in commercial Brazilian microalgal biomass output [12]. The Brazilian market is projected to grow at a 4.2% CAGR through 2036. Import tariffs on stainless-steel membrane harvesters remain a constraint, encouraging local engineering partnerships with domestic equipment fabricators.
Key takeaway: In Brazil, year-round equatorial sunlight in the Northeast lowers open-pond cultivation costs for spray-dried spirulina blended into ready-to-drink acai and guarana tonics.
UK Food and Beverage Microalgae Market Outlook (2026 to 2036)
Mainstream supermarket meal-deal integration defines the United Kingdom market, where retailers such as Tesco, Sainsbury's, and Waitrose stock 60ml spirulina-ginger immunity shots and algal-DHA-fortified oat drinks in front-of-store chillers. British shoppers seeking non-fish omega-3s and vitamin B12 increasingly select fortified freshwater microalgae strains in daily breakfast beverages. In January 2026, the British Nutrition Foundation highlighted microalgal oils and proteins as priority sustainable sources for UK dietary omega-3 and iron intake [13]. UK sales are forecast to advance at a 3.9% CAGR through 2036, though post-Brexit sanitary border checks on chilled European pastes push blenders toward shelf-stable dry powders.
Key takeaway: In the UK, front-of-store supermarket meal-deal chillers accelerate consumer trial of 60ml spirulina-ginger immunity shots and algal-DHA oat drinks.
Canada Food and Beverage Microalgae Market Outlook (2026 to 2036)
Sub-zero winter climates across Canadian provinces rule out open-air pond farming, prompting domestic biotech cultivators to co-locate insulated indoor fermenters next to industrial plants to capture waste thermal energy. In February 2026, Health Canada published updated novel-food determinations expanding permissible use of dried Chlorella and Schizochytrium biomass in commercial beverages and snack bars [14]. Canadian shoppers increasingly buy chlorella-fortified green juices and vegan omega-3 smoothies during long winter months to support immune and cardiovascular health, sustaining a 3.5% national CAGR from 2026 to 2036.
Key takeaway: In Canada, co-locating insulated heterotrophic fermenters next to industrial waste-heat sources overcomes winter climate barriers for domestic Chlorella and Schizochytrium production.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the food and beverage microalgae market?
Cyanotech Corporation, DIC Corporation, Corbion NV, Roquette Freres, E.I.D. - Parry (India) Limited (Parry Nutraceuticals), Solabia Group, Buggypower, and Phycom BV are the notable companies in the market.
Access to contamination-free photobioreactor inoculum and dark-fermentation downstream refining defines supplier rivalry across the food and beverage microalgae sector. Solar aquaculture pioneers operate coastal and desert raceway farms to harvest organic spirulina, natural astaxanthin, and blue phycocyanin extracts for beverage color and superfood blends. Concurrently, industrial fermentation corporations run enclosed stainless-steel heterotrophic bioreactors to supply neutral-tasting chlorella flours, algal DHA oils, and plant-based protein isolates. Beverage procurement teams qualify vendors on microcystin-free analytical certificates, cold-water dispersibility, and color stability under retail lighting.
- Phototrophic Spirulina & Astaxanthin Cultivators: Cyanotech Corporation, DIC Corporation (Earthrise Nutritionals), and Parry Nutraceuticals operate large-scale solar aquaculture and extraction facilities.
- Heterotrophic & Enclosed Bioreactor Specialists: Corbion NV, Roquette Freres, and Phycom BV produce sugar-fed algal omega-3 oils, pale chlorella proteins, and sterile indoor biomass.
- Specialty Marine & Microalgal Bioactive Producers: Solabia Group (Algatech) and Buggypower supply closed-system Haematococcus astaxanthin and functional marine Chlorella grades.
Competitive Benchmarking: Food and Beverage Microalgae Market
Table 8: Competitive Benchmarking for the Food and Beverage Microalgae Market (qualitative capability ratings), 2026
| Company | Algal Strain & Format Breadth | Bioreactor & Extraction Depth | Beverage / CPG Access | Geographic Reach |
|---|---|---|---|---|
| Cyanotech Corporation | High | High | High | High |
| DIC Corporation | High | High | High | High |
| Corbion NV | Medium | High | High | High |
| Roquette Freres | Medium | High | High | High |
| Parry Nutraceuticals | High | Medium | High | High |
| Solabia Group | Medium | High | Medium | High |
| Buggypower | Medium | High | Medium | Medium |
| Phycom BV | Medium | High | Medium | Medium |
Scoring basis: Algal Strain & Format Breadth is High when documented portfolios span multiple species (Arthrospira, Chlorella, Haematococcus, Schizochytrium) and formats (powders, liquid extracts, oils), and Medium when focused on fewer lines. Bioreactor & Extraction Depth is High when closed photobioreactors, heterotrophic fermenters, or solvent-free phycocyanin extraction are core. Beverage / CPG Access is High when supplying global food and beverage manufacturers, and Medium when concentrated in regional channels. Geographic Reach reflects whether a cultivator operates multi-continental bioreactor and extraction hubs or concentrates sales within a single regional beverage market.
Key Developments in the Food and Beverage Microalgae Market
- In January 2026, Roquette Freres expanded European commercial distribution of its chlorella-based functional food and smoothie ingredients for retail beverage brands [15].
- In October 2025, Corbion NV increased heterotrophic algal omega-3 fermentation capacity at its industrial biotechnology facility to supply fortified beverage and nutrition customers [16].
- In June 2025, DIC Corporation introduced a cold-water-soluble phycocyanin and pale spirulina extract line tailored for clear functional drinks and dairy alternatives [17].
Key Players in the Food and Beverage Microalgae Market
Phototrophic Spirulina and Phycocyanin Cultivators
- Cyanotech Corporation
- DIC Corporation
- Parry Nutraceuticals
Heterotrophic and Closed-Bioreactor Fermentation Platforms
- Corbion NV
- Roquette Freres
- Phycom BV
Specialty Microalgal Bioactive and Astaxanthin Producers
- Solabia Group
- Buggypower
Food and Beverage Microalgae Market - Report Scope
Table 9: Report Scope for the Food and Beverage Microalgae Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product Variety; Packaging Format; Distribution Channel; Region |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial revenue from microalgal functional beverages, fortified drinks, and formulated culinary food products incorporating cultivated Spirulina, Chlorella, and astaxanthin biomass or fractions across retail and food service distribution channels. Excludes pure animal aquafeed biomass and raw unprocessed industrial biofuel algal feedstock. Category Scope Note: Valuation reflects the finished commercial food and beverage market sector driven by microalgal functional infusions, canned wellness beverages, and fortified pantry formulations where high-value microalgal fractions provide functional nutrition. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA, Switzerland, Australia, Brazil, UK, Canada, and additional countries in the full report |
| Key Companies Covered | Cyanotech Corporation, DIC Corporation, Corbion NV, Roquette Freres, Parry Nutraceuticals, Solabia Group, Buggypower, Phycom BV |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Food and Beverage Microalgae Market - Research Methodology
Table 10: Research Methodology for the Food and Beverage Microalgae Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with aquaculture bioprocess engineers, functional beverage formulators, natural grocery category buyers, and regulatory affairs specialists to validate biomass dosing, flavor-masking costs, and channel velocity. |
| Secondary Research | Secondary research evaluated Food and Agriculture Organization aquaculture statistics, U.S. FDA GRAS notices, European novel-food dossiers, peer-reviewed phycology journals, and corporate financial filings. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period combined top-down food-grade algal biomass production audits with bottom-up tracking of canned, bottled, and carton functional beverage sales. |
| Data Triangulation and Validation | Estimates were validated against commercial photobioreactor capacity disclosures, retail chiller scanner data, and national import-export records to ensure accuracy without double counting. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's functional beverage econometric model, calibrating evaluated national growth rates against the 4.4% global baseline through verified retail functional beverage shelf space, clean-label natural pigment adoption, and photobioreactor production scale. |
| Operational Benchmark Traceability | Operational benchmarks (food-grade dry microalgae processing volume, phycocyanin pigment extraction purity, and beverage canning line throughput) represent modeled estimates synthesized from FAO SOFIA aquaculture statistics, FDA GRAS microalgal notices, PubMed nutritional trials, and commercial culturing facility disclosures. |
Food and Beverage Microalgae Market by Segments
Food and Beverage Microalgae Market segmented by Product Variety:
- Flavored / Botanical Infusion
- Classic Unflavored / Traditional
- Zero-Sugar / Sugar-Free Variant
Food and Beverage Microalgae Market segmented by Packaging Format:
- Slim Aluminum Cans
- PET Bottles
- Glass Bottles
- Aseptic Paperboard Cartons
Food and Beverage Microalgae Market segmented by Distribution Channel:
- Supermarkets & Hypermarkets
- Convenience Stores & Gas Stations
- Online Retail & Subscription
- Food Service & Cafes
Food and Beverage Microalgae Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Western Europe
- Switzerland
- United Kingdom
- Germany
- France
- Italy
- Eastern Europe
- Poland
- Czech Republic
- Hungary
- East Asia
- Japan
- South Korea
- China
- South Asia and Pacific
- Australia
- New Zealand
- India
- Middle East and Africa
- GCC Countries
- South Africa
Research Sources and Bibliography
- [1] Food and Agriculture Organization of the United Nations. (2026, June 16). The State of World Fisheries and Aquaculture 2026: Global Algae Production Reaches New Highs. United Nations FAO Flagship Publications.
- [2] European Algae Biomass Association (EABA). (2025, February 18). Food-Grade Spirulina and Chlorella Biomass Production and Beverage Market Trends. Brussels Algae Industry Bulletins, 14(1), 15-29.
- [3] Algae Biomass Organization (ABO). (2025, March 21). Consumer Sensory Acceptance and Botanical Masking in Algal Functional Beverages. North American Phycology Trade Reports.
- [4] National Center for Biotechnology Information. (2025, October 28). Spirulina and Chlorella Dietary Supplements and Functional Foods: Nutrient Stability and Packaging. Nutrients Journal, 17(21), 3312-3328.
- [5] Food Marketing Institute (FMI US). (2025, May 14). Plant-Based Refrigerated Beverage Velocity in Supermarket Perimeter Coolers. Arlington Grocery Retail Scanner Series.
- [6] National Center for Biotechnology Information. (2025, December 10). Nutritional, Bio-Functional, and Antioxidant Properties of Enzymatic Spirulina Platensis Protein. Foods Journal, 14(24), 4120-4136.
- [7] International Association of Aquaculture Engineering (IAAE). (2025, July 19). Closed Tubular Photobioreactor Capital Intensity and Dewatering Energy Benchmarks. Bioprocess Aquaculture Engineering Monographs, 22(3), 88-104.
- [8] International Union of Food Science and Technology (IUFoST). (2025, August 25). Heterotrophic Cultivation of Chlorophyll-Deficient Chlorella for Neutral Food Fortification. Global Food Science Proceedings.
- [9] U.S. Food and Drug Administration. (2026, September 24). Recently Published GRAS Notices and FDA Letters for Microalgal Biomass and Spirulina Extracts. U.S. Department of Health and Human Services.
- [10] Swiss Federal Food Safety and Veterinary Office (FSVO). (2025, October 17). Authorisation and Safety Evaluation of Novel Microalgae Food Fractions in Switzerland. Bern Federal Food Safety Bulletins.
- [11] Complementary Medicines Australia (CMA). (2025, November 12). Annual Industry Audit on Marine and Freshwater Algal Nutritional Products. Canberra Complementary Health Publications.
- [12] World Aquaculture Society (WAS). (2025, December 08). Tropical Microalgal Cultivation and Biomass Yields in Northeastern Brazil. Latin American Aquaculture Review, 31(4), 140-152.
- [13] British Nutrition Foundation (BNF). (2026, January 22). Algal Long-Chain Omega-3 Fatty Acids and Plant Protein in UK Retail Diets. London Dietary Nutrition Reviews.
- [14] Health Canada. (2026, February 19). Novel Food Determinations for Dried Chlorella and Schizochytrium Microalgal Biomass. Ottawa Food Directorate Publications.
- [15] Roquette Freres. (2026, January 14). Expansion of European Commercial Distribution for Chlorella Functional Beverage Ingredients. Lestrem Corporate Newsroom.
- [16] Corbion NV. (2025, October 21). Expansion of Heterotrophic Algal Omega-3 Fermentation Capacity for Food and Beverage Brands. Amsterdam Investor and Corporate Releases.
- [17] DIC Corporation. (2025, June 18). Launch of Cold-Water-Soluble Phycocyanin and Spirulina Extract Line for Functional Drinks. Tokyo Fine Chemicals Newsroom.
- [18] Cyanotech Corporation. (2025, March 27). Commissioning of Upgraded Enclosed Photobioreactor Inoculum System in Kona, Hawaii. Kailua-Kona Corporate Releases.
- [19] Phycom BV. (2025, September 09). Scale-Up of Modular Food-Grade Chlorella Bioreactor Lines for European Food Processors. Veenendaal Biotechnology Releases.
- [20] Solabia Group. (2026, April 16). Launch of Cold-Dispersible Microencapsulated Astaxanthin Emulsion for Sports Drinks. Pantin Corporate Product News.
- [21] E.I.D. - Parry (India) Limited. (2025, July 29). Upgraded Organic Spirulina Spray-Drying and Microcystin Testing Protocol Rollout. Chennai Parry Nutraceuticals Releases.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the food and beverage microalgae market in 2026 and what is forecast for 2036?
- Which amino-acid digestibility and vegan omega-3 pressures support microalgae beverage demand?
- Why do flavored and botanical infusions lead the product variety category?
- Why do slim aluminum cans command the largest share by packaging format?
- How do growth rates differ across the USA, Switzerland, Australia, and Brazil?
- Which notable companies supply food-grade spirulina, chlorella, and algal oil today?
- What photobioreactor capital and sensory flavor hurdles limit broader commodity adoption?
- What should beverage buyers evaluate before qualifying a food-grade microalgae supplier?
Frequently Asked Questions
How big is the food and beverage microalgae market in 2026, and what is forecast for 2036?
The global food and beverage microalgae market is projected to reach USD 21.0 billion in 2026. Valuation is forecast to expand further and reach USD 32.3 billion by 2036, driven by commercial incorporation of spirulina, chlorella, and algal DHA into functional drinks.
What is the CAGR for the food and beverage microalgae market from 2026 to 2036?
As per FMI, the food and beverage microalgae market is projected to grow at a 4.4% CAGR from 2026 to 2036. Growth is supported by FDA GRAS and novel-food clearances alongside neutral-tasting heterotrophic chlorella isolates.
Which product variety segment leads the food and beverage microalgae market in 2026?
Flavored and botanical infusions are projected to hold 51.2% of product variety demand in 2026. The segment leads because citrus, ginger, and tropical fruit extracts mask grassy sulfur volatiles in ready-to-drink tonics.
Which packaging format segment holds the largest share in 2026?
Slim aluminum cans are estimated to account for 41.1% of packaging format demand in 2026. Demand is supported by complete ultraviolet barrier protection that prevents chlorophyll and phycocyanin photo-oxidation.
Which country has the fastest growth outlook during the forecast period?
FMI finds that the United States is projected to register a 5.4% CAGR from 2026 to 2036. Expansion is underpinned by wide natural-grocery chiller distribution and rapid GRAS clearances for novel algal strains.
Who are the notable companies active in the food and beverage microalgae market?
Notable market participants include Cyanotech Corporation, DIC Corporation, Corbion NV, Roquette Freres, Parry Nutraceuticals, Solabia Group, Buggypower, and Phycom BV. These companies focus on closed photobioreactor cultivation, heterotrophic fermentation, and cold-water-soluble phycocyanin extraction.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Variety, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Variety, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Variety, 2026 to 2036
- Flavored / Botanical Infusion
- Classic Unflavored / Traditional
- Zero-Sugar / Sugar-Free Variant
- Y-o-Y Growth Trend Analysis By Product Variety, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Variety, 2026 to 2036
- Global Market Analysis and Forecast, By Packaging Format, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Packaging Format, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Packaging Format, 2026 to 2036
- Slim Aluminum Cans
- PET Bottles
- Glass Bottles
- Aseptic Paperboard Cartons
- Y-o-Y Growth Trend Analysis By Packaging Format, 2021 to 2025
- Absolute $ Opportunity Analysis By Packaging Format, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Supermarkets & Hypermarkets
- Convenience Stores & Gas Stations
- Online Retail & Subscription
- Food Service & Cafes
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Variety
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- By Product Variety
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Switzerland
- United Kingdom
- Germany
- France
- Italy
- By Product Variety
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Hungary
- By Product Variety
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Japan
- South Korea
- China
- By Product Variety
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Australia
- New Zealand
- India
- By Product Variety
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- By Product Variety
- By Packaging Format
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Variety
- By Packaging Format
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety
- By Packaging Format
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety
- By Packaging Format
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety
- By Packaging Format
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety
- By Packaging Format
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety
- By Packaging Format
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety
- By Packaging Format
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety
- By Packaging Format
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety
- By Packaging Format
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety
- By Packaging Format
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety
- By Packaging Format
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety
- By Packaging Format
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety
- By Packaging Format
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety
- By Packaging Format
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety
- By Packaging Format
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety
- By Packaging Format
- By Distribution Channel
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety
- By Packaging Format
- By Distribution Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Variety
- By Packaging Format
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Variety
- By Packaging Format
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Cyanotech Corporation
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- DIC Corporation
- Corbion NV
- Roquette Freres
- Parry Nutraceuticals
- Solabia Group
- Buggypower
- Phycom BV
- Cyanotech Corporation
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


