

- Market Size (2026)
- USD 661.5 Mn
- Forecast (2036)
- USD 2549.9 Mn
- CAGR (2026 to 2036)
- 14.0%
How big is Inactive Dried Yeast Market in 2026?
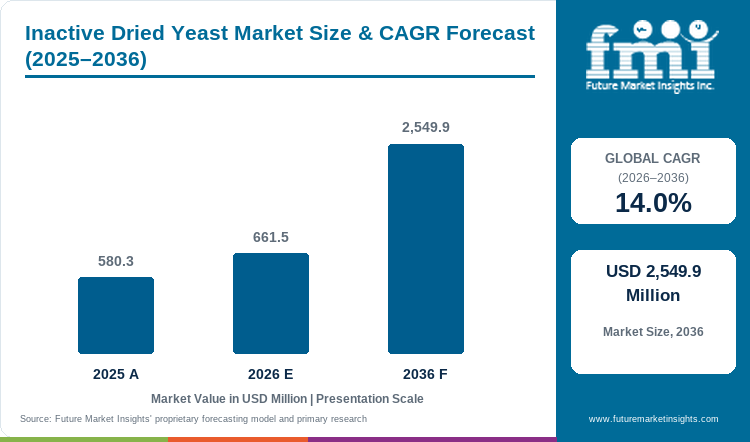
USD 661.5 million in 2026 and USD 2,549.9 million by 2036 at a 14.0% CAGR.
Sales of inactive dried yeast are estimated to grow at 14.0% from USD 661.5 million in 2026 to USD 2549.9 million by 2036. The market was valued at USD 580.3 million in 2025. Commercial demand is expanding as food manufacturers, nutrition brands and fermentation users specify deactivated whole-cell yeast for flavor, nutrient delivery and process support. Current supplier portfolios show that product form, nutrient standardization and application support increasingly sit beside price in purchasing decisions.
The growth mechanism differs by country. In food applications, the commercial overlap with the nutritional yeast market is strongest where flakes or powders can move from specialty use into routine meals, seasonings and plant-based formulations. Lallemand's current Engevita positioning and Lesaffre's 2025 consumer work both point to nutrition and culinary use as practical demand routes. In B2B accounts, repeat orders depend on a stable grade that performs consistently across production batches and fits the customer's labeling requirements.
Key Takeaways of Inactive Dried Yeast Market
- Whole-cell inactive yeast demand is expanding through food, nutrition and fermentation applications that require repeatable functional and nutrient specifications.
- B2B leads Sales Channel with a 68.0% share in 2026 as approved formulations translate into recurring ingredient purchases.
- Conventional leads Nature with a 96.0% share in 2026, while Organic serves customers that need a certified ingredient pathway.
- Application compatibility remains a key restraint because flavor, dispersibility and whole-cell behavior can change the finished recipe or fermentation process.
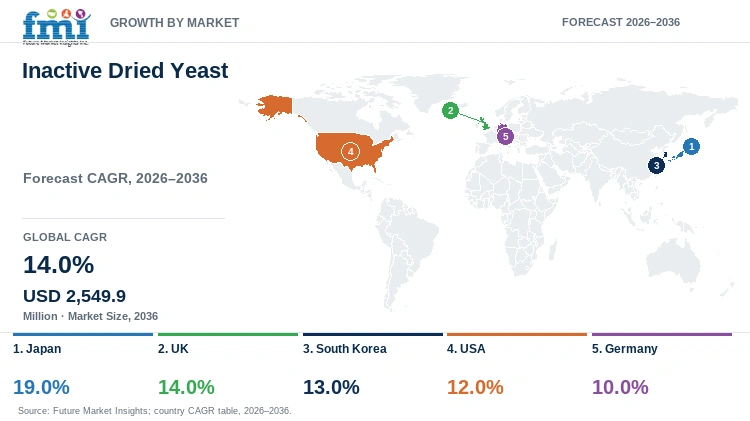
- Japan records the fastest profiled CAGR at 19.0% from 2026 to 2036, followed by the UK at 14.0%.
- Lallemand Inc., Angel Yeast Co. Ltd., Lesaffre Group, Leiber GmbH and Kothari Fermentation and Biochem Ltd. are notable companies serving the market.
Analyst Perspective
Inactive dried yeast creates durable value when the supplier can connect a defined whole-cell grade with the customer's actual food, nutrition or fermentation process. Buyers will continue to reward consistent specifications, application support and dependable replenishment rather than broad nutrition claims alone.
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Inactive Dried Yeast Market segmented?
The inactive dried yeast market is segmented by Sales Channel, Nature and Region.
Sales Channel comprises B2B and B2C. Nature comprises Conventional and Organic. Region coverage includes North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and the Middle East and Africa. The taxonomy covers dried inactivated whole-cell yeast sold as a finished ingredient rather than live yeast, separated yeast extract or isolated protein fractions.
Why does B2B lead demand within the Sales Channel category?
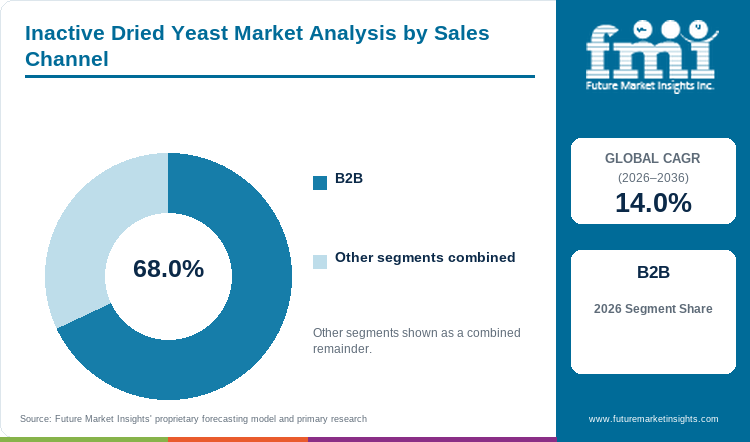
B2B purchasing connects inactive dried yeast to a formulation, process specification or foodservice program. Manufacturers typically evaluate sensory contribution, nutrient profile, handling behavior and batch consistency before approving a grade. Once the ingredient is embedded in the recipe or production process, replenishment can continue across repeated runs. B2C demand is more exposed to household trial, pack preference and retail visibility, which makes purchasing less concentrated around long production programs.
- B2B holds 68.0% of Sales Channel revenue in 2026, reflecting the weight of manufacturer, foodservice and process-driven ingredient purchasing.
- Supplier value rises when technical support shortens qualification and helps the customer reproduce the same result at commercial scale.
Why does Conventional lead demand within the Nature category?
Conventional inactive dried yeast serves recipes and processes that do not require certified organic sourcing, giving buyers a broader purchasing base and fewer certification constraints. The organic yeast market remains relevant where the finished product depends on an organic claim, but those programs require certified substrates, controlled handling and documentation through the supply chain. The commercial choice therefore turns on whether organic status creates enough downstream value to justify a separate sourcing program.
- Conventional accounts for 96.0% of Nature demand in 2026 and remains the default route for most industrial and culinary applications.
- Organic inactive yeast serves a narrower set of products where certification is part of the consumer proposition or customer specification.
What are the drivers, restraints and opportunities in the Inactive Dried Yeast Market?
Food formulation and nutrition demand support whole-cell yeast purchases, application incompatibility slows switching, and process-specific fermentation uses open additional B2B opportunities.
- Driver: Culinary and nutrition applications combine savory contribution with protein, fiber and micronutrient positioning.
- Restraint: Whole-cell behavior can change flavor, water interaction and process performance, so suppliers must qualify the actual grade.
- Opportunity: Fermentation and fortification programs can widen demand where inactive yeast is specified for a defined process or nutrient target.
Food and nutrition formulations broaden repeat use
Lallemand's 2026 nutritional-yeast material positions primary-grown inactive yeast across vegan, vegetarian and general food applications, while Lesaffre's September 2025 review links nutritional yeast with culinary use and dietary supplementation. This supports a demand mechanism based on formulation rather than simple supplement novelty. The adjacent fermented ingredients market also illustrates how food manufacturers increasingly use fermentation-derived inputs as functional components of mainstream recipes. Inactive dried yeast benefits when it earns a stable place in a repeatable product rather than relying on one-off consumer experimentation.
Application incompatibility makes supplier switching costly
Inactive whole-cell yeast can influence flavor, dispersibility, texture and nutrient delivery. A grade that performs well in a seasoning or plant-based recipe may not behave the same way in a fermentation nutrient program. This makes switching a technical exercise as well as a procurement decision. Buyers often need bench work, sensory review and process validation before replacing an established ingredient, which protects qualified incumbents but increases the value of application support for challengers.
Nutrient-standardized yeast opens higher-value specifications
Suppliers are also widening the category through vitamin- and mineral-standardized whole-cell yeasts. The commercial opportunity overlaps with fermented mineral ingredients when buyers want nutrients delivered through a fermentation-derived matrix rather than a conventional mineral salt. Standardized selenium, zinc or vitamin content can create higher-value specifications for supplements and fortified foods, provided the supplier can support identity, consistency and the intended product claim.
Which country CAGRs are profiled in the Inactive Dried Yeast Market?
The profiled country CAGRs cover 2026 to 2036.
| Country | CAGR |
|---|---|
| Japan | 19.0% |
| UK | 14.0% |
| South Korea | 13.0% |
| USA | 12.0% |
| Germany | 10.0% |
How do country-level CAGRs compare in the Inactive Dried Yeast Market?
Japan leads the profiled country forecasts at 19.0% CAGR from 2026 to 2036. The UK follows at 14.0%, South Korea at 13.0%, the USA at 12.0%, and Germany at 10.0%. The nine-percentage-point spread reflects different retail, certification, import and industrial supply conditions rather than a uniform route to market.
- Japan: Corporate investment in yeast processing and strong functional-food channels support specialized ingredient development.
- UK: Organic food and drink sales continued to expand in 2025, supporting certified ingredient programs alongside conventional nutrition products.
- South Korea: Imported food suppliers must align product identity, facility registration and Korean-language labeling before commercial delivery.
- USA: Culinary use of nutritional yeast gives suppliers a route into both retail food and B2B formulation programs.
- Germany: Leiber's manufacturing base and subsequent Asahi ownership highlight the country's role in European dried-yeast processing and distribution.
Country-wise Analysis
- Japan is forecast to grow at a 19.0% CAGR from 2026 to 2036. Asahi Group Foods moved deeper into yeast processing through the 2025 acquisition of Leiber, adding European dried-yeast and yeast-derivative capabilities to a Japanese group with long experience in yeast-based nutrition. For suppliers targeting Japan, the commercial opportunity is strongest in clearly specified nutrition and functional-food applications where product identity, nutrient content and technical support can be documented for the buyer.
- The UK is projected to expand at a 14.0% CAGR from 2026 to 2036. Soil Association Certification's Organic Market Report shows UK organic food and drink sales reached GBP 3.86 billion in 2025, up 4.2% from the prior year. That broader organic momentum supports a premium route for certified yeast alongside the much larger conventional category. Suppliers still need to keep the organic proposition tied to a product format and price point that can sustain repeat household or B2B use.
- South Korea carries a 13.0% CAGR from 2026 to 2036. USDA's 2025 FAIRS guidance describes foreign-facility registration and Korean-language labeling requirements for imported food. Inactive dried yeast suppliers therefore need importer-ready documentation before scaling a launch. The advantage belongs to companies that can provide consistent specifications and clear classification support without slowing the customer's commercialization schedule.
- The USA is forecast to grow at a 12.0% CAGR from 2026 to 2036. Gnosis by Lesaffre's May 2025 social-listening work found strong US discussion around nutritional yeast as a food and diet ingredient. This creates an opening for suppliers serving seasonings, plant-based foods, foodservice and nutrition formats. The purchasing challenge is to translate consumer familiarity into repeatable B2B recipes with a defined flavor and nutrient specification.
- Germany is projected at a 10.0% CAGR from 2026 to 2036. Asahi Group Foods' 2025 transaction brought Leiber's German dried-yeast processing platform into a larger international yeast business. The deal placed manufacturing sites, customer-development capability and a broad sales network under a group that is investing in microbial and yeast-derived ingredients. German suppliers can compete through production reliability and application support across European B2B accounts.
Who are the notable companies in the Inactive Dried Yeast Market?
Lallemand Inc., Angel Yeast Co. Ltd., Lesaffre Group, Leiber GmbH and Kothari Fermentation and Biochem Ltd. are the notable companies profiled in this market.
Competition spans primary-grown nutritional yeast, brewers' yeast recovery, standardized nutrient grades and process-specific whole-cell products. Lallemand, Angel Yeast and Lesaffre compete with broad food and nutrition portfolios. Leiber adds a brewers' yeast processing route with a growing European production footprint. Kothari Fermentation and Biochem lists nutritional yeast, identified as inactive dry yeast, within its current manufacturing portfolio. The category remains distinct from the yeast extract market, where soluble extracts are sold for different formulation and flavor functions.
- Primary-grown food and nutrition platforms: Lallemand Inc., Angel Yeast Co. Ltd. and Lesaffre Group.
- Brewers' yeast processing and dried-yeast recovery: Leiber GmbH.
- India-based yeast manufacturing: Kothari Fermentation and Biochem Ltd., with inactive dry yeast listed in its product portfolio.
Competitive Benchmarking: Inactive Dried Yeast Market
| Company | Whole-cell grade breadth | Nutrient-standardized yeasts | Application support | Geographic Reach |
|---|---|---|---|---|
| Lallemand Inc. | High | High | High | North America and Europe, with global food and nutrition channels. |
| Angel Yeast Co. Ltd. | High | Medium | Medium | China-based production with international food, nutrition and animal-nutrition channels. |
| Lesaffre Group | High | High | High | Global nutritional-yeast and culinary ingredient reach through Gnosis and Biospringer. |
| Leiber GmbH | Medium | Unscored | Medium | Germany-centered network with European sites, including a Romania production site acquired in August 2026 through the purchase of Agsira S.R.L. |
| Kothari Fermentation and Biochem Ltd. | Medium | Unscored | Medium | India-based manufacturing serving domestic and export yeast markets. |
Scoring basis: High indicates broad, current evidence across the named capability. Medium indicates a narrower but documented capability. Unscored is retained where the benchmark is not central to the company's current whole-cell positioning. Ratings describe operating capability and do not represent company market share.
Key Developments in the Inactive Dried Yeast Market
- In August 2026, Leiber completed the acquisition of the Agsira production site in Romania. The new location expands dry-yeast production capacity and strengthens the company's position in the Balkan and Central and Eastern European region.
- In September 2025, Angel Yeast presented AuraNutra at SPACE 2025, held September 16 to 18 at the Rennes Exhibition Centre, France, positioning it as a primary-fermented inactive yeast for animal nutrition in international B2B channels.
- In 2025, Asahi Group Foods added Leiber GmbH to its consolidated subsidiaries following the share acquisition announced in March, giving the Japanese group a European base in dried yeast and related yeast ingredients.
Key Players in the Inactive Dried Yeast Market
Primary-grown food and nutrition platforms
- Lallemand Inc.
- Angel Yeast Co. Ltd.
- Lesaffre Group
Brewers' yeast processing and recovery
- Leiber GmbH
India-based yeast manufacturing
- Kothari Fermentation and Biochem Ltd.
Inactive Dried Yeast Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By Sales Channel, Nature and Region. |
| Quantitative Units | Revenue in USD Million and CAGR in %. |
| Market Definition | Revenue covers dried inactivated whole-cell yeast sold through B2B or B2C channels in Conventional or Organic form. Live yeast, separated yeast extracts, isolated yeast proteins and downstream finished-product revenue are excluded. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | USA; UK; Germany; Japan; South Korea |
| Key Companies Profiled | Lallemand Inc.; Angel Yeast Co. Ltd.; Lesaffre Group; Leiber GmbH; Kothari Fermentation and Biochem Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with market triangulation. |
Inactive Dried Yeast Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, distributors, food developers, nutrition companies, fermentation users, procurement teams and subject-matter experts. Interviews examined product qualification, purchasing decisions, formulation requirements, switching barriers, pricing and technical support. |
| Desk Research | Desk research covered government statistics, regulatory publications, industry associations, technical literature, company filings, product information and official corporate announcements. |
| Market Sizing and Forecasting | The market model combined the baseline value with segment structure, pricing and volume indicators, adoption conditions, company participation and country-level demand factors. Forecast assumptions considered food and nutrition demand, organic certification, industrial use, product qualification and supply expansion. |
| Data Validation | Estimates were checked against independent market indicators, company activity, public data and primary research. Segment and country assumptions were reconciled against the defined whole-cell inactive dried yeast scope. |
Inactive Dried Yeast Market by Segments
Inactive Dried Yeast Market segmented by Sales Channel:
- B2B
- B2C
Inactive Dried Yeast Market segmented by Nature:
- Conventional
- Organic
Inactive Dried Yeast Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- Lallemand Inc. (2026). Nutritional Yeast.
- Lallemand Bio-Ingredients (2025, July 30). Savory Ingredients Featured on Taste of Science Stage at IFT First 2025.
- Gnosis by Lesaffre (2025, May 27). Infodemiology Offers a Fresh Lens on Nutritional Yeast.
- Lesaffre (2025, September 9). What is Nutritional Yeast?
- Angel Yeast Co. Ltd. (2025, September 17). Angel Yeast Leads Feed Revolution at SPACE 2025.
- Asahi Group Holdings (2025, March 10). Asahi Group Foods Acquires Shares in German Beer Yeast Products Company.
- Asahi Group Holdings (2025, March 10). Asahi Group Foods Acquires Shares in German Beer Yeast Products Company. [Press release confirming share transfer agreement signed March 5, 2025, with completion targeted by end of April 2025.]
- Leiber GmbH (2026, August 31). Company announcement on completion of the Agsira S.R.L. production-site acquisition in Romania.
- Kothari Fermentation and Biochem Ltd. (2025). Annual Report 2025.
- USDA Foreign Agricultural Service (2025, April 22). FAIRS Country Report Annual: Korea - Republic of.
- Department for Environment, Food & Rural Affairs, UK (2026). Food Statistics in Your Pocket, including 2025 organic food and drink sales.
- Soil Association Certification (2026). Organic Market Report 2026.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the inactive dried yeast market in 2025, 2026 and 2036?
- Which food, nutrition and fermentation applications support repeat purchasing?
- Why does B2B lead the Sales Channel category?
- Why does Conventional lead the Nature category?
- How do growth rates differ across the profiled countries?
- Which companies supply current whole-cell inactive dried yeast products?
- What can delay qualification or switching between inactive dried yeast grades?
- What should buyers evaluate before committing to recurring purchases?
Frequently Asked Questions
How big is the Inactive Dried Yeast Market in 2026, and what is forecast for 2036?
The inactive dried yeast market is valued at USD 661.5 million in 2026 and is forecast to reach USD 2,549.9 million by 2036. The market was valued at USD 580.3 million in 2025.
What is the Inactive Dried Yeast Market CAGR from 2026 to 2036?
The market is forecast to expand at a 14.0% CAGR from 2026 to 2036, supported by wider food, nutrition and process-specific B2B applications.
Which Sales Channel segment leads the Inactive Dried Yeast Market?
B2B leads Sales Channel with a 68.0% share in 2026. Manufacturer and foodservice programs can convert an approved yeast specification into recurring ingredient orders.
Which Nature segment leads the Inactive Dried Yeast Market?
Conventional leads Nature with a 96.0% share in 2026. Organic serves a narrower set of buyers that require certified sourcing and handling through the supply chain.
Which profiled countries have the highest growth rates?
Japan has the highest profiled CAGR at 19.0%, followed by the UK at 14.0% from 2026 to 2036. South Korea, the USA and Germany follow at 13.0%, 12.0% and 10.0%, respectively.
Which companies are profiled in the Inactive Dried Yeast Market?
The report profiles Lallemand Inc., Angel Yeast Co. Ltd., Lesaffre Group, Leiber GmbH and Kothari Fermentation and Biochem Ltd. Their roles span primary-grown nutritional yeast, nutrient-standardized yeast, brewers' yeast processing and industrial yeast manufacturing.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Sales Channel, 2026 to 2036
- B2B
- B2C
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Nature, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Nature, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Nature, 2026 to 2036
- Conventional
- Organic
- Y-o-Y Growth Trend Analysis By Nature, 2021 to 2025
- Absolute $ Opportunity Analysis By Nature, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Sales Channel
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Sales Channel
- By Nature
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Sales Channel
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Sales Channel
- By Nature
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Sales Channel
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Sales Channel
- By Nature
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Sales Channel
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Sales Channel
- By Nature
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Sales Channel
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Sales Channel
- By Nature
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Sales Channel
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Sales Channel
- By Nature
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Sales Channel
- By Nature
- By Country
- Market Attractiveness Analysis
- By Country
- By Sales Channel
- By Nature
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Sales Channel
- By Nature
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Sales Channel
- By Nature
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Lallemand Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Angel Yeast Co. Ltd.
- Lesaffre Group
- Leiber GmbH
- Kothari Fermentation and Biochem Ltd.
- Lallemand Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


