
- Market Size (2026)
- USD 1.7 Bn
- Forecast (2036)
- USD 20.9 Bn
- CAGR (2026 to 2036)
- 28.5%
How big is Hydrogen Combustion Engine Market in 2026?
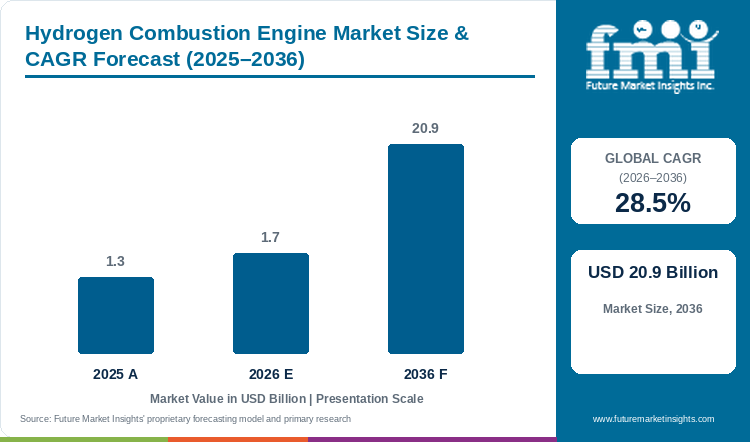
The hydrogen combustion engine market demonstrated steady progress from USD 1.3 billion in 2025 to USD 1.7 billion in 2026, building toward a targeted valuation of USD 20.9 billion by 2036 at a CAGR of 28.5%.
According to FMI, the global hydrogen combustion engine market size progressed from USD 1.3 billion in 2025 to USD 1.7 billion in 2026 and is projected to attain a valuation of USD 20.9 billion by 2036 at a 28.5% CAGR. This 28.5% annual growth rate far outpaces the 12.6% CAGR projected for portable hydrogen powered generator units because heavy-duty truck and construction equipment manufacturers are converting high-volume 6.7-liter to 15-liter diesel factory lines to meet binding 2030 zero-emission fleet rules. Commercial freight haulers and off-highway fleet buyers favor Direct Injection H2-ICE platforms (60.2% fuel-injection share) and Heavy-Duty Commercial Vehicles (57.1% vehicle-class share) because hydrogen engines retain over 70% of existing diesel spare parts and service tooling. The demand for direct-injection hydrogen engines is supported by engine calibration breakthroughs that match diesel efficiency while meeting strict nitrogen oxide exhaust rules. For instance, a February 2026 ACS Omega study demonstrated that a 120 kW direct-injection hydrogen engine achieved 43% brake thermal efficiency and kept tailpipe nitrogen oxides below 35 mg/km [1]. However, sparse 700-bar highway hydrogen refueling stations and dry-gas fuel injector wear remain major restraining factors for commercial fleet buyers. Even so, fleet orders continue to scale across return-to-base trucking corridors and construction sites served by mobile hydrogen fuel bowsers.
Key Market Trends & Insights
- By fuel injection: Direct injection H2-ICE captures 60.2% in 2026 by raising cylinder volumetric efficiency and preventing intake backfire.
- By application: Transportation and mobility commands 65.1% in 2026 while freight operators decarbonize long-haul truck and bus fleets.
- By vehicle class: Heavy-duty commercial vehicles account for 57.1% in 2026 under European and Asian zero-emission CO2 fleet regulations.
- By power output: Engines rated 200 kW to 500 kW hold 48.4% in 2026 across heavy trucks, excavators, and regional rail cars.
- By boosting architecture: Two-stage turbocharged lean-burn platforms lead OEM series production by maintaining torque density above lambda 2.4.
Regional Highlights
- Top national expansion: Japan leads national expansion at a 29.6% CAGR through 2036 under automotive OEM racing and commercial truck consortia.
- Broader country progression: Germany advances at a 29.2% CAGR ahead of South Korea at 28.4% and the United States at 27.8% through 2036.
Market Size & Forecast
Table 1: Market Size and Forecast for the Hydrogen Combustion Engine Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 1.3 billion |
| Estimated Market Size in 2026 | USD 1.7 billion |
| Projected Market Size by 2036 | USD 20.9 billion |
| CAGR, 2026 to 2036 | 28.5% |
| Added Value, 2026 to 2036 | USD 19.2 billion |
Heavy-duty truck and machinery builders are investing in hydrogen combustion engines because battery packs add excessive curb weight on long-haul routes. Adapting cast-iron diesel engine blocks to burn hydrogen lets manufacturers use current foundries and avoid fuel-cell stack re-tooling. Per an April 2026 ACS Omega study, 15 MPa direct hydrogen injectors boost thermal efficiency by 15% to 25% [2]. OEM powertrain teams therefore pair high-flow injectors with cold-rated hydrogen ICE ignition system platforms to prevent knocking.
Fleet Powertrain Production and H2 Consumption Sizing
Table 2: Powertrain Volume and Hydrogen Demand Sizing for the Hydrogen Combustion Engine Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 1.3 | 1.7 | 20.9 |
| Annual H2-ICE units shipped (thousand) | 28.0 to 34.0 | 37.0 to 45.0 | 480.0 to 560.0 |
| Peak brake thermal efficiency benchmark (%) | 41.0% to 43.0% | 42.0% to 45.8% | 46.0% to 49.0% |
| Direct injection pressure range (MPa) | 2.0 to 15.0 | 3.0 to 15.0 | 10.0 to 30.0 |
Operational note: Engine production and hydrogen consumption ranges align heavy-duty truck, off-highway machinery, and stationary genset rollouts with published efficiency test data.
Commercial fleet maintenance directors are increasingly choosing hydrogen combustion engines over proton-exchange membrane fuel cells for dusty construction sites and regional freight operations. Unlike delicate fuel-cell membranes that suffer permanent damage from trace air pollutants or industrial-grade hydrogen impurities, internal combustion cylinders tolerate standard commercial hydrogen and heavy vibration. Logistics operators evaluating zero-emission hydrogen trucks also save on mechanic retraining because engine block overhauls use standard diesel workshop tools.
OEM Engine Line & Refueling Corridor Sizing
Table 3: Fleet Deployment and Refueling Indicators for the Hydrogen Combustion Engine Market (USD), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Transportation & Mobility value (USD billion) | 0.85 | 1.11 | 13.61 |
| Direct Injection H2-ICE value (USD billion) | 0.78 | 1.02 | 12.58 |
| Heavy-Duty Commercial Vehicles value (USD billion) | 0.74 | 0.97 | 11.93 |
| 200 kW to 500 kW bracket value (USD billion) | 0.63 | 0.82 | 10.12 |
Table 4: Segment Allocation Indicators for the Hydrogen Combustion Engine Market (USD and percentages), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 1.7 billion | 2026 global market value baseline |
| Direct Injection H2-ICE value, 2026 | USD 1.02 billion | 60.2% fuel-injection segment allocation |
| Transportation and Mobility value, 2026 | USD 1.11 billion | 65.1% application segment allocation |
| Heavy-Duty Commercial Vehicles value, 2026 | USD 0.97 billion | 57.1% vehicle-class segment allocation |
Total cost of ownership math across regional trucking and off-highway equipment fleets favors hydrogen combustion engines whenever up-front vehicle purchase prices must stay close to diesel baselines. Fleet procurement managers weigh lower engine hardware costs against fuel consumption rates when comparing heavy-duty hydrogen engines with transport fuel cell powertrains across 500-mile freight corridors.
Analyst Perspective
"Commercial vehicle and off-highway OEMs favor direct-injection hydrogen combustion engines since shared diesel block architectures cut development capex and tolerate non-ultrapure hydrogen. Engine suppliers that integrate ultralean turbocharging with selective catalytic reduction aftertreatment will capture initial fleet decarbonization orders."
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the hydrogen combustion engine market segmented?
The hydrogen combustion engine market spans fuel injection, application, vehicle class, and power output. In 2026, direct injection H2-ICE captures 60.2%, transportation and mobility 65.1%, heavy-duty commercial vehicles 57.1%, and 200 kW to 500 kW engines 48.4%.
By fuel injection: Direct injection H2-ICE (60.2%) and port fuel injection H2-ICE cover high-pressure in-cylinder and manifold fueling.
By application: Transportation and mobility (65.1%) joins stationary power generation and off-highway construction and mining across OEM catalogs.
By vehicle class: Heavy-duty commercial vehicles (57.1%) join marine vessels and locomotives and light-duty fleet vehicles.
By power output: Engines rated 200 kW to 500 kW (48.4%) join above 500 kW and below 200 kW platforms.
By aspiration and combustion mode: Two-stage turbocharged ultralean spark-ignition and dual-fuel compression-ignition architectures govern series production.
Why does direct injection H2-ICE account for a notable share of fuel injection demand?
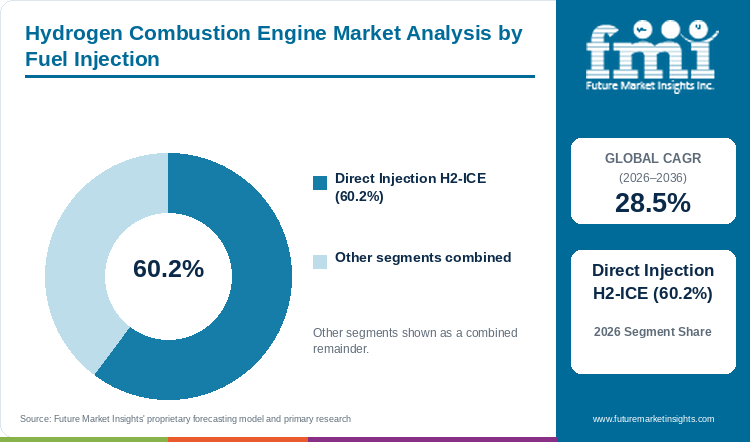
Based on fuel injection, direct injection H2-ICE is projected to account for 60.2% in 2026, driven by manifold backfire elimination.
Table 5: Fuel Injection Share for the Hydrogen Combustion Engine Market (percentage share), 2026
| Fuel Injection | Share (2026) |
|---|---|
| Direct Injection H2-ICE | 60.2% |
| Port Fuel Injection H2-ICE | 39.8%* |
| Total | 100.0% |
*Note: Direct injection and port fuel injection sum to 100.0% of 2026 engine shipments.
Table 6: Fuel Injection Leadership and Market Growth for the Hydrogen Combustion Engine Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 28.5% |
| Leading Segment | Direct Injection H2-ICE (60.2% in 2026) |
FMI's segment analysis indicates that Direct Injection H2-ICE leads fuel-injection sales because injecting hydrogen directly into the closed cylinder prevents intake manifold backfire and lifts power output by more than 20% over port injection. Expanding commercial hydrogen refueling station corridors dispensing 350-bar and 700-bar gas directly support fleet rollouts of direct-injection heavy trucks.
- Direct injection H2-ICE secures 60.2% of 2026 fuel injection demand by eliminating intake air displacement and knocking across heavy-duty cylinders.
- Per July 2025 Scientific Reports findings, a 4-cylinder direct-injection H2 engine reached 45.84% thermal efficiency and 0.03 g/kWh NOx [3].
What supports transportation and mobility as a preferred choice in the application category?
By application, transportation and mobility is estimated to hold 65.1% in 2026, owing to heavy-duty truck decarbonization mandates.
Transportation and Mobility accounts for the largest application share because commercial truck and rail operators face heavy financial penalties under 2030 European and Asian carbon rules. Engine builders equip on-road commercial fleets with high-pressure hydrogen ICE fuel injection systems to deliver fast highway refueling and full payload capacity.
- Transportation and mobility commands 65.1% of 2026 application market value as truck and bus OEMs commercialize multi-cylinder hydrogen engines.
- Per May 2025 Scientific Reports modeling, port water injection in spark-ignition H2 engines lowers peak combustion temperatures and NOx [4].
How are heavy-duty commercial vehicles gaining use across applications in vehicle class?
In 2026, heavy-duty commercial vehicles is expected to lead vehicle class with 57.1% share, supported by long-haul payload retention.
Heavy-Duty Commercial Vehicles generate the bulk of vehicle-class demand because long-haul Class 8 tractors and vocational dump trucks require continuous high-torque pulling power that quickly drains battery packs. Freight depots pair on-site hydrogen generator electrolyzers with 13-liter to 15-liter hydrogen trucks to keep fleets running on predictable 800-kilometer daily schedules.
- Heavy-duty commercial vehicles hold 57.1% of 2026 vehicle class demand since 13-liter to 15-liter H2-ICE blocks match diesel payload capacity.
- Cummins and Project Brunel partners validated 6.7-liter and 15-liter H2-ICE blocks in March 2025 and cut carbon emissions over 99% [5].
Why are buyers selecting 200 kW to 500 kW engines within power output?
Within power output, 200 kW to 500 kW is forecast to represent 48.4% in 2026, underpinned by heavy truck demand.
Engines rated between 200 kW and 500 kW capture the leading power-output share because this 270 to 675 horsepower bracket powers standard highway freight tractors, regional passenger trains, and large construction excavators. Machinery manufacturers are actively converting off-highway vehicle engines in this power range to burn zero-carbon hydrogen on urban building sites.
- The 200 kW to 500 kW bracket accounts for 48.4% of 2026 power output value across heavy commercial trucks and rail propulsion.
- A February 2025 Scientific Reports UK rail study showed a 390 kW H2 engine on Class 195 trains cut CO2e 92.5% [6].
Which market conditions keep large-bore dual-fuel engines relevant within stationary and marine power?
Above 500 kW and dual-fuel H2-ICE platforms are likely to capture growing stationary share in 2026, linked to maritime propulsion.
Demand for engines above 500 kW is expanding across coastal cargo vessels, mine haul trucks, and utility peak-power plants that require multi-megawatt output and rapid load ramping. Independent power producers install hydrogen-ready high-speed engine generator sets that can burn either pure hydrogen or hydrogen-biodiesel blends as local fuel supplies develop.
- High-output and dual-fuel hydrogen engines expand across stationary peaking plants and coastal ferries where fuel flexibility protects fleet running rates.
- A June 2026 Scientific Reports study found 2.5 to 7.5 L/min hydrogen supplementation raised peak cylinder pressure to 47 bar and cut CO2 [7].
What are the drivers, restraints, and opportunities in the hydrogen combustion engine market?
In the hydrogen combustion engine market, zero-emission fleet laws and shared diesel tooling expand OEM orders whereas sparse 700-bar refueling stations restrain rollouts and dual-fuel off-highway retrofits create growth opportunities.
- Driver: Zero-emission heavy-duty vehicle classification under EU and Asian CO2 regulations and shared diesel tooling economics accelerate OEM H2-ICE production.
- Restraint: Sparse heavy-duty 700-bar hydrogen refueling corridors and dry-gas injector lubrication wear restrict immediate fleet-wide commercial adoption.
- Opportunity: Hydrogen-biodiesel dual-fuel compression-ignition retrofits and off-highway mining and construction excavators generate near-term commercial engine orders.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Heavy-duty truck and maritime engine builders commercialize hydrogen combustion engines to meet zero-emission fleet rules while retaining existing foundry and machining lines. Since gaseous hydrogen burns across a wide flammability range, ultralean operation above lambda 2.4 keeps combustion temperatures low and limits thermal NOx formation. An FMI analyst notes that coastal shipping operators also evaluate hydrogen dual-fuel retrofits across marine reciprocating engine fleets to avoid vessel stranding. Per a July 2025 Scientific Reports study, 40% hydrogen induction in low-temperature engines reached 32.04% efficiency and cut hydrocarbons 65% [8]. Commercial OEMs therefore lock in multi-year fleet supply agreements by offering fuel-agnostic engine blocks compatible with diesel, natural gas, and hydrogen cylinder heads.
Risk Assessment of the Hydrogen Combustion Engine Market: Injector Wear and Refueling Gaps
Dry gaseous hydrogen lubrication deficiency and sparse public heavy-duty refueling infrastructure constitute the main barriers that limit commercial fleet deliveries. Unlike diesel fuel that lubricates injector needles automatically, low-viscosity hydrogen gas causes metallic fretting wear and sealing leakage across high-pressure direct injectors. Crankcase oil droplets entering the combustion chamber can also trigger stochastic pre-ignition and damaging pressure spikes under high turbocharger boost pressures. A June 2026 PLoS One study showed 12% hydrogen enrichment at full engine load raises peak cylinder pressure 6.9% and requires precise timing control [9]. Commercial freight operators therefore delay volume tractor orders until OEMs warrant 15,000-hour injector durability and highway 700-bar dispensing prices decline.
Commercial Opportunity Analysis: Dual-Fuel Compression-Ignition and Off-Highway Retrofits
Industrial and agricultural engine economics reward manufacturers that offer hydrogen-biodiesel dual-fuel compression-ignition kits for existing off-highway and stationary diesel engines. Construction sites and rural microgrids lack pure hydrogen pipelines, yet operators can induct gaseous hydrogen into intake manifolds with pilot biodiesel injection. A February 2026 Scientific Reports paper showed 8 LPM hydrogen induction lifted common-rail thermal efficiency to 37% and cut fuel use 20% [10]. Dual-fuel manifold conversion allows mining and agricultural contractors to cut carbon intensity immediately without waiting for greenfield pipeline networks across remote work sites. Suppliers that package bolt-on hydrogen rail hardware and electronic control unit calibration kits capture high-margin retrofit demand across heavy equipment fleets.
Hydrogen Combustion Engine Market by Country (2026 to 2036)
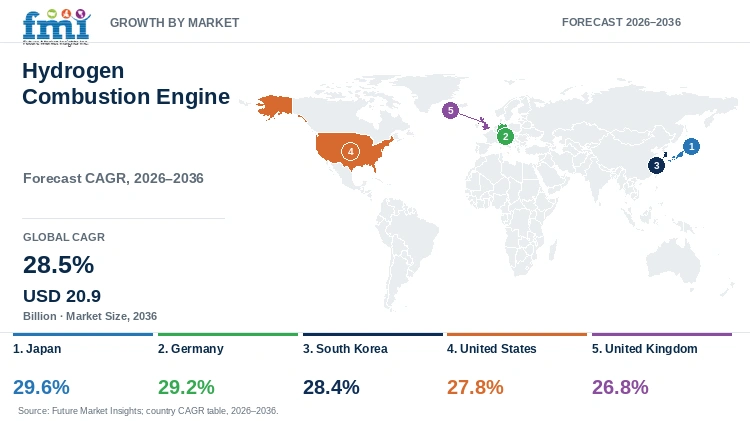
As per FMI, Japan leads national hydrogen combustion engine growth at a 29.6% CAGR through 2036, while the UK expands 26.8%. Commercial deployment across East Asian automotive alliances and European heavy-duty freight corridors depends on hydrogen station grants and zero-emission tailpipe laws.
Table 7: Country CAGR and Primary Growth Levers for the Hydrogen Combustion Engine Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Japan | 29.6% | Automotive OEM endurance racing validation and Green Transformation commercial hydrogen truck consortia |
| Germany | 29.2% | Federal NOW heavy-duty refueling network grants and series production of 7.8-liter to 15-liter H2-ICE blocks |
| South Korea | 28.4% | National Hydrogen Economy Roadmap subsidies and 11-liter truck, bus, and excavator engine commercialization |
| United States | 27.8% | Fuel-agnostic 15-liter heavy-duty engine platforms and regional clean air agency fleet demonstration grants |
| United Kingdom | 26.8% | Off-highway construction excavator rollouts and Darlington heavy-duty hydrogen powertrain testing |
Source: Future Market Insights analysis
Japan Hydrogen Combustion Engine Market Outlook (2026 to 2036)
Per a November 2025 Toyota disclosure, Super Taikyu endurance racing validated liquid and gaseous hydrogen engine durability and direct injector sealing [11]. Those high-speed track trials also verified twin-scroll turbocharging and crankcase ventilation across multi-hour commercial duty cycles in Japanese race cars. Japan leads global hydrogen combustion engineering through joint heavy-truck and industrial R&D programs linking Toyota and Kawasaki with Isuzu and DENSO. Adoption of hydrogen combustion engines in Japan is estimated to expand at 29.6% CAGR through 2036, supported by Green Transformation sovereign transition bonds. High domestic landed costs for imported liquid hydrogen still inflate fleet operating budgets, so Japanese OEMs engineer dual-pressure direct injection and cryogenic fuel pumps.
Key takeaway: In Japan, OEM consortium development and Green Transformation freight subsidies anchor series commercialization of direct-injection hydrogen engines.
Germany Hydrogen Combustion Engine Market Outlook (2026 to 2036)
European Union heavy-duty CO2 standards classify hydrogen combustion engines with sub-1 g CO2/tkm tailpipe output as zero-emission commercial vehicles. That statutory classification positions Germany as the continental manufacturing hub for stationary and off-highway H2-ICE blocks across central Europe. In June 2025, MAN Energy Solutions formally rebranded as Everllence SE while expanding its Augsburg hydrogen and dual-fuel reciprocating engine development programs [12]. Sales of hydrogen combustion engines in Germany are forecast to expand at a 29.2% CAGR by 2036, driven by zero-emission motorway toll exemptions. Delays in completing the 9,000-kilometer national hydrogen core pipeline still limit rural fuel access, so German OEMs target captive truck depots. Fleet logistics directors establish dedicated on-site hydrogen dispensing stations to maintain scheduled regional delivery routes.
Key takeaway: In Germany, federal heavy-duty refueling network grants and commercial production of 7.8-liter to 15-liter H2-ICE blocks drive fleet adoption.
South Korea Hydrogen Combustion Engine Market Outlook (2026 to 2036)
South Korea pairs industrial engine manufacturing scale in Ulsan and Incheon with statutory clean hydrogen power generation auctions under the Hydrogen Economy Roadmap. A March 2026 iScience policy assessment of South Korea's 11th Basic Electricity Plan documented targets to raise power generation 21% to 704 TWh [13]. That national plan also lifts renewable share to 33% by 2038 while introducing clean hydrogen co-firing across utility power plants. By 2036, South Korea is projected to grow at 28.4% CAGR, underpinned by domestic 11-liter truck and excavator engine commercialization. Reliance on byproduct petrochemical hydrogen still creates carbon-intensity compliance hurdles, so Korean engine builders certify generator sets on imported green hydrogen.
Key takeaway: In South Korea, clean hydrogen power auctions and domestic 11-liter heavy-duty truck and excavator engine programs sustain rapid market expansion.
United States Hydrogen Combustion Engine Market Outlook (2026 to 2036)
Per the March 2026 South Coast AQMD Clean Fuels report, regional agencies executed 16 clean-fuel powertrain contracts and 18 technology assessments in 2025 [14]. United States commercial demand centers on fuel-agnostic 15-liter Class 8 truck platforms and regional clean hydrogen hubs across California, Texas, and the Midwest. Between 2026 and 2036, the United States market is expected to progress at 27.8% CAGR, reinforced by federal Clean Hydrogen Production tax credits. Port drayage decarbonization mandates in Southern California and Gulf Coast petrochemical clusters further support heavy-duty fleet trials. Slow permitting for 700-bar highway dispensing stations still restricts cross-country trucking, so U.S. engine OEMs prioritize regional return-to-base freight corridors and peaking gensets.
Key takeaway: In the United States, fuel-agnostic 15-liter truck engine platforms and regional clean air demonstration grants drive commercial fleet trials.
United Kingdom Hydrogen Combustion Engine Market Outlook (2026 to 2036)
Off-highway construction sites and rural agricultural estates across the United Kingdom lack high-voltage grid connections needed to fast-charge heavy battery-electric excavators and telehandlers. Per the June 2026 UK Climate Change Committee report to Parliament, national greenhouse gas emissions fell to 407 MtCO2e in 2025 [15]. That parliamentary report noted emissions reached 50% below 1990 levels while off-highway machinery requires rapid zero-carbon fuel switching. Hydrogen combustion engine demand in the United Kingdom is forecast to rise at 26.8% CAGR over the forecast period, aided by JCB excavator type-approval. Limited public hydrogen filling stations still constrain on-road vans, so UK equipment rental fleets deploy mobile pressurized gas bowsers to building sites.
Key takeaway: In the United Kingdom, off-highway construction excavator rollouts and Darlington heavy-duty powertrain manufacturing anchor national H2-ICE growth.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the hydrogen combustion engine market?
Cummins Inc. and MAN Energy Solutions SE (Everllence SE) join DEUTZ AG, Toyota Motor Corporation, JCB Inc., and Wartsila Corporation as notable companies.
In the FMI report, market participation across hydrogen combustion engines is consolidated among heavy-duty diesel and gas engine OEMs with global dealer networks. On-road and construction OEMs develop 5-liter to 15-liter spark-ignited direct-injection hydrogen engines built on fuel-agnostic cast-iron blocks. Maritime and power generation leaders engineer medium-speed four-stroke dual-fuel engines capable of burning hydrogen blends across utility microgrids and vessels.
- Commercial Truck & Multi-Application Engine Leaders: Cummins Inc. and DEUTZ AG develop 6.7-liter to 15-liter direct-injection hydrogen engines for heavy trucks and stationary gensets.
- Automotive & Off-Highway Machinery Pioneers: Toyota Motor Corporation and JCB Inc. commercialize high-speed direct-injection hydrogen engines for commercial vans, heavy trucks, and construction excavators.
- Marine & Stationary Large-Bore Power Platforms: MAN Energy Solutions SE and Wartsila Corporation supply medium-speed hydrogen and dual-fuel reciprocating engines for vessels and power plants.
Competitive Benchmarking: Hydrogen Combustion Engine Market
Table 8: Competitive Benchmarking for the Hydrogen Combustion Engine Market (qualitative capability ratings), 2026
| Company | Direct-Injection H2 Breadth | Thermal & NOx Control Depth | Truck / Off-Highway Access | Geographic Reach |
|---|---|---|---|---|
| Cummins Inc. | High | High | High | High |
| MAN Energy Solutions SE | High | High | Medium | High |
| DEUTZ AG | High | High | High | High |
| Toyota Motor Corporation | High | High | High | High |
| JCB Inc. | Medium | High | High | Medium |
| Wartsila Corporation | Medium | High | Medium | High |
Scoring basis: Capability tiers evaluate documented direct-injection H2-ICE thermal efficiency, NOx aftertreatment integration, and shared diesel block manufacturing readiness. Application breadth and geographic ratings reflect verified on-road truck, off-highway excavator, and stationary power customer trials.
Key Developments in the Hydrogen Combustion Engine Market
- In September 2026, Toyota Motor Corporation and European partners highlighted over 70 high-capacity stations and 800 heavy-duty hydrogen trucks [16].
- In March 2026, DEUTZ AG reported 2025 new orders up 13.7% and revenue up 12.7% while commercializing TCG 7.8 H2 engines [17].
- In February 2026, Everllence SE commissioned its single-cylinder 35/44DF H2 test engine running on 100% hydrogen at Augsburg [18].
Key Players in the Hydrogen Combustion Engine Market
Commercial Truck & Multi-Application Engine Leaders
- Cummins Inc.
- DEUTZ AG
Automotive & Off-Highway Machinery Pioneers
- Toyota Motor Corporation
- JCB Inc.
Marine & Stationary Large-Bore Power Platforms
- MAN Energy Solutions SE (Everllence SE)
- Wartsila Corporation
Hydrogen Combustion Engine Market - Report Scope
Table 9: Report Scope for the Hydrogen Combustion Engine Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Fuel Injection, Application, Vehicle Class, and Power Output |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial supplier value from spark-ignited and dual-fuel hydrogen internal combustion engines (direct injection and port fuel injection) across transportation, off-highway, marine, and stationary power applications. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa |
| Countries Covered | Japan, Germany, South Korea, United States, United Kingdom, and additional countries in the full report |
| Key Companies Covered | Cummins Inc., MAN Energy Solutions SE (Everllence SE), DEUTZ AG, Toyota Motor Corporation, JCB Inc., and Wartsila Corporation |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Hydrogen Combustion Engine Market - Research Methodology
Table 10: Research Methodology for the Hydrogen Combustion Engine Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with engine OEMs, fuel-injection suppliers, commercial fleet operators, off-highway machinery builders, and powertrain experts across the value chain to validate H2-ICE trends, thermal efficiency benchmarks, demand dynamics, and purchasing decisions. |
| Secondary Research | Secondary research included company annual reports, investor presentations, regulatory publications, industry associations, technical papers, trade journals, company websites, product literature, and other publicly available sources relevant to the hydrogen combustion engine market. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 forecast period were developed using top-down and bottom-up approaches to assess engine unit volume demand, block price points, and fleet adoption trends. |
| Data Triangulation and Validation | Data is validated against macro-economic indicators, heavy-duty zero-emission fleet drivers, regulatory CO2 standards, and historical trend analysis to maintain accuracy without double counting adjacent fuel-cell categories. |
Hydrogen Combustion Engine Market by Segments
Hydrogen Combustion Engine Market segmented by Fuel Injection:
- Direct Injection H2-ICE (60.2%)
- Port Fuel Injection H2-ICE
- High-Pressure In-Cylinder Jet Ignition
- Dual-Fuel Manifold Induction Systems
Hydrogen Combustion Engine Market segmented by Application:
- Transportation and Mobility (65.1%)
- Stationary Power Generation
- Off-Highway Construction and Mining
Hydrogen Combustion Engine Market segmented by Vehicle Class:
- Heavy-Duty Commercial Vehicles (57.1%)
- Marine Vessels and Locomotives
- Light-Duty Fleet Vehicles
Hydrogen Combustion Engine Market segmented by Power Output:
- 200 kW to 500 kW (48.4%)
- Above 500 kW
- Below 200 kW
- Megawatt-Scale Stationary & Marine Blocks
Hydrogen Combustion Engine Market segmented by Boosting & Combustion Architecture:
- Two-Stage Turbocharged Lean-Burn SI
- Water-Injected Spark-Ignition H2-ICE
- Hydrogen-Biodiesel Dual-Fuel CI
- Coordinated Urea-SCR Aftertreatment Packages
- Fuel-Agnostic Modular Engine Blocks
Hydrogen Combustion Engine Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Jiang, J., Yang, J., & Cheng, Y. (2026, February 13). NOx/N2O Formation and Coordinated Urea-SCR Control in an Ultra-Lean Hydrogen-Fueled Automotive SI Engine: Engine Mapping and WLTC Strategy Evaluation. ACS Omega, 11(7), 12788 to 12798 (PMCID PMC12947045).
- [2] Sang, H., Ye, Y., Lei, Y., Zhu, Z., Kou, C., Liu, X., & Qiu, T. (2026, April 13). Effect of the Injector Pressure-Building Process on Dynamic Gas Flow Characteristics of a Highly Turbulent Underexpanded Hydrogen Jet from a Single-Hole Cylindrical Injector. ACS Omega, 11(16), 24028 to 24040 (PMCID PMC13129861).
- [3] Huang, Z., Zhu, T., Wang, L., Wang, L., Ali, A. S., Nassef, M. G. A., Wang, T., & Ahmed, R. H. (2025, July 2). Synergistic optimization of combustion chamber design and hydrogen injection strategies for ultra-lean combustion in hydrogen engines. Scientific Reports, 15, 23073 (PMCID PMC12216848).
- [4] Saied, O. M., & Abdelwahab, M. (2025, May 17). 1D hydrogen engine modeling to investigate air-fuel ratio, spark timing, and water injection effects on performance and emissions. Scientific Reports, 15(1), 17184 (PubMed PMID 40382394).
- [5] Cummins Inc. (2025, March 6). Cummins and partners celebrate successful hydrogen engine project. Cummins Newsroom.
- [6] Marjani, S. R., Motaman, S., Varasteh, H., Yang, Z., & Clementson, J. (2025, February 22). Assessing hydrogen as an alternative fuel for rail transport: a case study. Scientific Reports, 15, 6449 (PMCID PMC11846835).
- [7] Sathasivam, K., Colak, I., Arunprasad, J., Rajkumar, S., Subbiah, M., Mizher, R. M., & Thirusuthan, V. (2026, June 23). Hydrogen-assisted Nannochloropsis sp. microalgae biodiesel to operate cleaner diesel engines. Scientific Reports (PubMed PMID 42331904).
- [8] Ramalingam, K., Abdullah, M. Z., Elumalai, P. V., Reddy, M. V., Yafang, Y., Prabhakar, S., & Priya, K. K. (2025, July 17). Production and utilization of hydrogen enriched fifth generation biofuel in LTC engines with reformed EGR. Scientific Reports, 15, 25922 (PMCID PMC12271319).
- [9] Naidu, B. V. V., Musthafa, B., Raja, M., Sivalakshmi, S., Srinivasan, S. A., Saravanan, B., & Jelila, Y. D. (2026, June 5). Numerical and experimental assessment of hydrogen enrichment effects on CI engine characteristics fuelled with dual biodiesel blends: A comprehensive study. PLoS One, 21(6), e0351152 (PubMed PMID 42247391).
- [10] Selvam, M., Nagarajan, P., Harish, K. A., Dhivya, V., Srinivasan, R. G., Samal, S. P., & Agrawal, A. (2026, February 18). Hydrogen enhanced biodiesel production from Botryococcus braunii algal oil for sustainable fuel development. Scientific Reports, 16(1), 9783 (PubMed PMID 41708947).
- [11] Toyota Motor Corporation. (2025, November 14). Pushing Hydrogen Engine Technology to New Heights in the Super Taikyu Series. Toyota Global Newsroom.
- [12] Everllence SE. (2025, June 4). MAN Energy Solutions becomes Everllence. Everllence Press Releases.
- [13] Ahn, J., Park, S., Kim, S. H., McJeon, H., & Eom, J. (2026, March 12). Assessing the consistency of simultaneous tripling of nuclear and renewable energy capacity in Korea: Evidence from the IPCC AR6 scenarios. iScience, 29(4), 115305 (PMCID PMC13049626).
- [14] South Coast Air Quality Management District. (2026, March 6). Approve and Adopt Technology Advancement Office Clean Fuels Program 2025 Annual Report and 2026 Plan Update. South Coast AQMD.
- [15] Climate Change Committee. (2026, June 24). Progress in reducing emissions 2026 report to Parliament. UK Climate Change Committee.
- [16] Toyota Motor Corporation. (2026, September 15). Industry Leaders scale Full Value Chain for Hydrogen Mobility across Europe. Toyota Global Newsroom.
- [17] DEUTZ AG. (2026, March 26). DEUTZ generates growth and achieves one of the highest profits in its recent history despite challenging market conditions in 2025. DEUTZ Press Releases.
- [18] Everllence SE (formerly MAN Energy Solutions SE). (2026, February 26). R&D Project Takes Step Towards CO2-Neutral Propulsion. Everllence Press Releases.
- [19] Cummins Inc. (2026, February 5). Cummins Reports Strong Fourth Quarter and Full-Year 2025 Results, Records Charges Associated with Electrolyzer Business Strategic Review. Cummins Newsroom.
- [20] Wartsila Corporation. (2026, January 7). Wartsila Investor Relations Roadshow Presentation. Wartsila Corporation.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the hydrogen combustion engine market in 2026 and what is forecast for 2036?
- Which fleet decarbonization and tooling factors support demand for hydrogen combustion engines?
- Why does Direct Injection H2-ICE lead the fuel injection category?
- Why does Transportation and Mobility lead the application category globally?
- How do growth rates differ across Japan, Germany, South Korea, and the USA?
- Which leading companies supply commercial hydrogen internal combustion engines today?
- What limits adoption or fleet scaling in the hydrogen combustion engine market?
- What should buyers evaluate before procuring a hydrogen combustion engine?
Table of Content
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Fuel Injection, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Fuel Injection, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Fuel Injection, 2026 to 2036
- Direct Injection H2-ICE (60.2%)
- Port Fuel Injection H2-ICE
- High-Pressure In-Cylinder Jet Ignition
- Dual-Fuel Manifold Induction Systems
- Y-o-Y Growth Trend Analysis By Fuel Injection, 2021 to 2025
- Absolute $ Opportunity Analysis By Fuel Injection, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Transportation and Mobility (65.1%)
- Stationary Power Generation
- Off-Highway Construction and Mining
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Vehicle Class, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Vehicle Class, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Vehicle Class, 2026 to 2036
- Heavy-Duty Commercial Vehicles (57.1%)
- Marine Vessels and Locomotives
- Light-Duty Fleet Vehicles
- Y-o-Y Growth Trend Analysis By Vehicle Class, 2021 to 2025
- Absolute $ Opportunity Analysis By Vehicle Class, 2026 to 2036
- Global Market Analysis and Forecast, By Power Output, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Power Output, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Power Output, 2026 to 2036
- 200 kW to 500 kW (48.4%)
- Above 500 kW
- Below 200 kW
- Megawatt-Scale Stationary & Marine Blocks
- Y-o-Y Growth Trend Analysis By Power Output, 2021 to 2025
- Absolute $ Opportunity Analysis By Power Output, 2026 to 2036
- Global Market Analysis and Forecast, By Boosting & Combustion Architecture, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Boosting & Combustion Architecture, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Boosting & Combustion Architecture, 2026 to 2036
- Two-Stage Turbocharged Lean-Burn SI
- Water-Injected Spark-Ignition H2-ICE
- Hydrogen-Biodiesel Dual-Fuel CI
- Coordinated Urea-SCR Aftertreatment Packages
- Fuel-Agnostic Modular Engine Blocks
- Y-o-Y Growth Trend Analysis By Boosting & Combustion Architecture, 2021 to 2025
- Absolute $ Opportunity Analysis By Boosting & Combustion Architecture, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- By Country
- Market Attractiveness Analysis
- By Country
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- By Country
- Market Attractiveness Analysis
- By Country
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- By Country
- Market Attractiveness Analysis
- By Country
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- By Country
- Market Attractiveness Analysis
- By Country
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- By Country
- Market Attractiveness Analysis
- By Country
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- By Country
- Market Attractiveness Analysis
- By Country
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- By Country
- Market Attractiveness Analysis
- By Country
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Fuel Injection
- By Application
- By Vehicle Class
- By Power Output
- By Boosting & Combustion Architecture
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Cummins Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- MAN Energy Solutions SE
- DEUTZ AG
- Toyota Motor Corporation
- JCB Inc.
- Wartsila Corporation
- MAN Energy Solutions SE (Everllence SE)
- Cummins Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Fuel Injection, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Vehicle Class, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Power Output, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Boosting & Combustion Architecture, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Fuel Injection, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Vehicle Class, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Power Output, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Boosting & Combustion Architecture, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Fuel Injection, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Vehicle Class, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Power Output, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Boosting & Combustion Architecture, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Fuel Injection, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Vehicle Class, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Power Output, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Boosting & Combustion Architecture, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Fuel Injection, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Vehicle Class, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Power Output, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Boosting & Combustion Architecture, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Fuel Injection, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Vehicle Class, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Power Output, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Boosting & Combustion Architecture, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Fuel Injection, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Vehicle Class, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Power Output, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Boosting & Combustion Architecture, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Fuel Injection, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Application, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Vehicle Class, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Power Output, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Boosting & Combustion Architecture, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Fuel Injection, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Fuel Injection, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Fuel Injection
- Figure 6: Global Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Application
- Figure 9: Global Market Value Share and BPS Analysis by Vehicle Class, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Vehicle Class, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Vehicle Class
- Figure 12: Global Market Value Share and BPS Analysis by Power Output, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Power Output, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Power Output
- Figure 15: Global Market Value Share and BPS Analysis by Boosting & Combustion Architecture, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Boosting & Combustion Architecture, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Boosting & Combustion Architecture
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Fuel Injection, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Fuel Injection, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Fuel Injection
- Figure 32: North America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Application
- Figure 35: North America Market Value Share and BPS Analysis by Vehicle Class, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Vehicle Class, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Vehicle Class
- Figure 38: North America Market Value Share and BPS Analysis by Power Output, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Power Output, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Power Output
- Figure 41: North America Market Value Share and BPS Analysis by Boosting & Combustion Architecture, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Boosting & Combustion Architecture, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Boosting & Combustion Architecture
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Fuel Injection, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Fuel Injection, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Fuel Injection
- Figure 48: Latin America Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Application
- Figure 51: Latin America Market Value Share and BPS Analysis by Vehicle Class, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Vehicle Class, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Vehicle Class
- Figure 54: Latin America Market Value Share and BPS Analysis by Power Output, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Power Output, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Power Output
- Figure 57: Latin America Market Value Share and BPS Analysis by Boosting & Combustion Architecture, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Boosting & Combustion Architecture, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Boosting & Combustion Architecture
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Fuel Injection, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Fuel Injection, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Fuel Injection
- Figure 64: Western Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Application
- Figure 67: Western Europe Market Value Share and BPS Analysis by Vehicle Class, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Vehicle Class, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Vehicle Class
- Figure 70: Western Europe Market Value Share and BPS Analysis by Power Output, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Power Output, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Power Output
- Figure 73: Western Europe Market Value Share and BPS Analysis by Boosting & Combustion Architecture, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Boosting & Combustion Architecture, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Boosting & Combustion Architecture
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Fuel Injection, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Fuel Injection, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Fuel Injection
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Application
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Vehicle Class, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Vehicle Class, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Vehicle Class
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Power Output, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Power Output, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Power Output
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Boosting & Combustion Architecture, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Boosting & Combustion Architecture, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Boosting & Combustion Architecture
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Fuel Injection, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Fuel Injection, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Fuel Injection
- Figure 96: East Asia Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Application
- Figure 99: East Asia Market Value Share and BPS Analysis by Vehicle Class, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Vehicle Class, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Vehicle Class
- Figure 102: East Asia Market Value Share and BPS Analysis by Power Output, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Power Output, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Power Output
- Figure 105: East Asia Market Value Share and BPS Analysis by Boosting & Combustion Architecture, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Boosting & Combustion Architecture, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Boosting & Combustion Architecture
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Fuel Injection, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Fuel Injection, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Fuel Injection
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Application
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Vehicle Class, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Vehicle Class, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Vehicle Class
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Power Output, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Power Output, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Power Output
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Boosting & Combustion Architecture, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Boosting & Combustion Architecture, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Boosting & Combustion Architecture
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Fuel Injection, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Fuel Injection, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Fuel Injection
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Application, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Application, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Application
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Vehicle Class, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Vehicle Class, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Vehicle Class
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Power Output, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Power Output, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Power Output
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Boosting & Combustion Architecture, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Boosting & Combustion Architecture, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Boosting & Combustion Architecture
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the hydrogen combustion engine market in 2026, and what is forecast for 2036?
FMI research indicates that global hydrogen combustion engine market size reaches USD 1.7 billion in 2026 from USD 1.3 billion in 2025. Powertrain demand is anticipated to reach USD 20.9 billion by 2036 across commercial applications.
What is the CAGR for the hydrogen combustion engine market from 2026 to 2036?
FMI data suggests a 28.5% compound annual growth rate over 2026 to 2036 for hydrogen combustion engines. That ten-year climb adds USD 19.2 billion in incremental annual market value.
Which fuel injection segment leads the hydrogen combustion engine market?
Direct injection H2-ICE captures 60.2% of fuel injection demand in 2026 since in-cylinder injection prevents manifold backfire and boosts thermal efficiency.
Which application segment leads the hydrogen combustion engine market?
Transportation and mobility secures 65.1% of the application category in 2026 as commercial freight fleets deploy heavy-duty hydrogen trucks.
Which country has a notable growth outlook during the assessment period?
Japan tops national H2-ICE growth at a 29.6% CAGR through 2036 under automotive OEM racing validation and commercial truck consortia.
Who are the key players in the market?
Cummins Inc. and MAN Energy Solutions SE head commercial engine development while DEUTZ AG and Toyota Motor Corporation expand vehicle platforms. JCB Inc. and Wartsila Corporation also compete across off-highway construction and stationary power markets.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
