

- Market Size (2026)
- USD 29.0 Bn
- Forecast (2036)
- USD 58.7 Bn
- CAGR (2026 to 2036)
- 7.3%
How big is Hunting Equipment and Accessories Market in 2026?
Hunting equipment and accessories market size stood at USD 27.0 billion in 2025, reaches USD 29.0 billion in 2026 and is projected at USD 58.7 billion by 2036. Demand for hunting equipment and accessories is set to expand at a 7.3% CAGR from 2026 to 2036 as license holders replace ammunition and upgrade optics each season.
Sales of hunting gear still run mostly through physical stores, even as online retail gains ground across outdoor categories. Hunting licenses generated USD 841 million for U.S. state wildlife agencies, the Congressional Sportsmen's Foundation reported in a National ASCF Fact Sheet dated July 2025 [1]. More than 52.7 million people took part in sport and target shooting in the United States in 2024, the National Shooting Sports Foundation found in a March 2025 study [2]. Due to this large licensed and shooting base, specialty stores keep 35.8% of distribution channel sales, as rifle fitting and shooting simulators are services an online cart cannot offer.
E-commerce still took only 17.1% of total U.S. retail sales in the second quarter of 2026, the U.S. Census Bureau reported in August 2026 [3]. Specialty retail is expected to keep most ammunition and firearm sales through 2036. Optics, apparel and small accessories are shifting further online as hunters price-check gear already tried in store. FMI puts ammunition in the lead with a 27.4% share of product type sales in 2026, as every season of hunting needs fresh rounds. Replacement ammunition purchases paired with specialty-store service are anticipated to keep sales of hunting equipment and accessories rising over the forecast period.
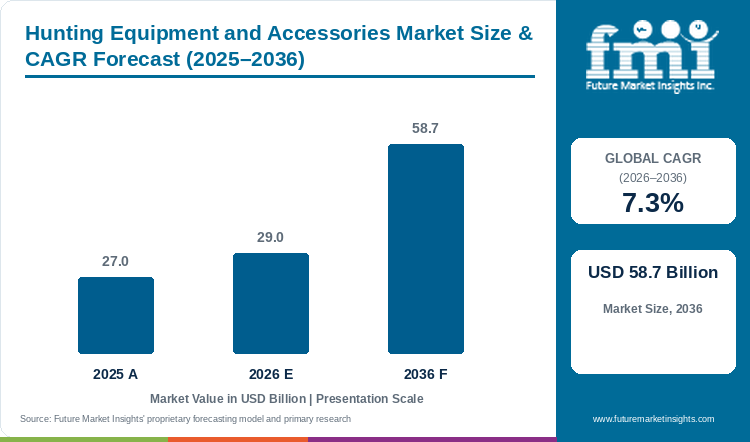
Key Market Trends & Insights
- By product type, ammunition leads with 27.4% of 2026 sales, as hunters buy fresh rounds every season instead of reusing old stock.
- By distribution channel, specialty stores hold 35.8% of 2026 sales. More than 52.7 million sport and target shooters visit U.S. ranges and stores each year, supporting in-store fitting and trial services, the National Shooting Sports Foundation reported in March 2025 [2].
- By region, FMI projects Oceania to post the fastest regional CAGR, at 10.3% through the forecast period, supported by Australia's established, regulated hunting and recreational shooting culture.
Regional Highlights
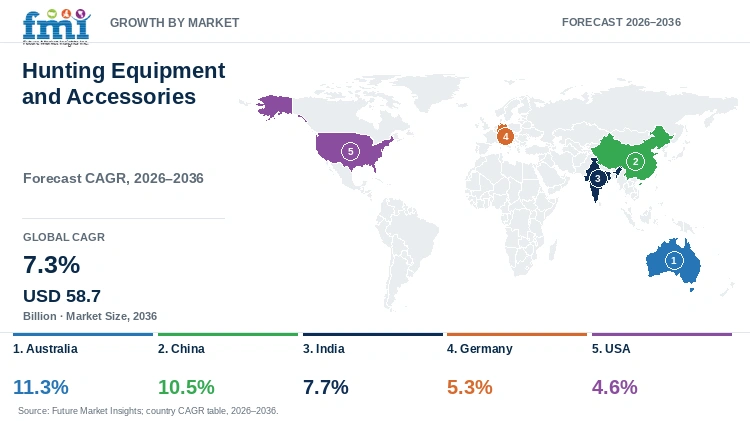
- Australia leads growth among the profiled countries at 11.3% CAGR from 2026 to 2036.
- China and India follow at 10.5% and 7.7% respectively, and the USA records the slowest profiled pace at 4.6% through 2036.
- More than 400 million people took part in outdoor sports in China in 2024, the General Administration of Sport of China reported in a national outdoor sports industry report; this broad outdoor-sports figure is a directional proxy rather than a hunting-specific participation count, since China's hunting regime remains tightly restricted.
Market Size & Forecast
Table 1: Market Size and Forecast for the Hunting Equipment and Accessories Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 27.0 billion |
| Estimated Market Size in 2026 | USD 29.0 billion |
| Projected Market Size by 2036 | USD 58.7 billion |
| CAGR, 2026 to 2036 | 7.3% |
| Added Sales, 2026 to 2036 | USD 29.7 billion |
| Market Expansion Multiple | 2.0x |
Licensed hunters replacing ammunition and upgrading optics each season still generate most hunting equipment orders. Lower cost per shot and better accuracy are the main reasons a hunter approves a new scope or crossbow. Specialty retail still keeps the advice and fitting services that online stores cannot match, a reason specialty stores hold 35.8% of distribution channel sales. E-commerce, at 17.1% of total U.S. retail sales in the second quarter of 2026 [3], is still a smaller channel for ammunition and firearms than for accessories and apparel. Firearm ownership restrictions in markets such as Japan keep hunting equipment sales per person low there. Replacement of ammunition and optics by returning hunters is anticipated to drive most orders through 2036.
Specialty Retail and Participation Base
Sales of hunting equipment track the size of the licensed hunting and shooting base closely. Hunting licenses generated USD 841 million for state wildlife agencies, the Congressional Sportsmen's Foundation reported in July 2025, drawing on data with roughly a two-year reporting lag [1]. More than 52.7 million people took part in sport and target shooting in the United States in 2024, the National Shooting Sports Foundation found in a March 2025 study [2]. This large base of repeat buyers keeps specialty stores ahead in distribution channel sales, since rifle fitting, shooting simulators and brand-exclusive deals are hard to replicate online. Ammunition replacement and optics upgrades are anticipated to take most specialty-store orders in the early forecast years, as hunters trial new gear before buying.
E-commerce is still gaining share of total retail sales only slowly, so online channels can take share from specialty hunting stores only gradually. E-commerce accounted for 17.1% of total U.S. retail sales in the second quarter of 2026 on a seasonally adjusted basis, the U.S. Census Bureau reported in August 2026 [3]. Outdoor participation growth outside the United States is adding new buyers for both channels. More than 400 million people took part in outdoor sports in China in 2024, the General Administration of Sport of China reported in a report released in November 2025. Rising middle-class participation in China and India is expected to widen the specialty retail network as digital brands compete for apparel and accessory sales. Specialty retail is set to keep the lead in ammunition and firearm sales through 2036, with online channels gaining mainly in optics, apparel and small accessories.
Table 2: Participation and Channel Benchmarks for the Hunting Equipment and Accessories Market (percentage and population figures), mixed reporting years 2024 to 2026
| Indicator | Data Point | Market Relevance | Source |
|---|---|---|---|
| Hunting license revenue, 2023 data (reported 2025) | USD 841 million to state wildlife agencies | A large licensed base supports steady replacement ammunition demand. | [1] |
| U.S. sport and target shooting participants, 2024 | More than 52.7 million people | A broad shooting base keeps specialty stores busy with fitting and trials. | [2] |
| U.S. e-commerce share of total retail sales, Q2 2026 | 17.1% of total sales (seasonally adjusted) | Online retail still runs well behind specialty stores for ammunition and firearms. | [3] |
| China outdoor sports participants, 2024 | More than 400 million people | A widening outdoor base is lifting demand for hunting optics and apparel. | — |
Analyst Perspective
“Hunters will keep buying ammunition and optics through specialty stores that offer fitting and trial services. Apparel and small accessories will shift further online. Brands that pair in-store advice with a strong digital catalogue will take most replacement orders through 2036.”
- Rahul Pandita, Principal Consultant, Future Market Insights.
How is the Hunting Equipment and Accessories Market segmented?
The hunting equipment and accessories market is studied across two commercial segments plus region, namely product type and distribution channel. FMI data show ammunition holding 27.4% of product type sales and specialty stores holding 35.8% of distribution channel sales in 2026.
By product type: ammunition, and accessories and other hunting equipment.
By distribution channel: specialty stores, and other channels including e-commerce, sporting goods chains, and direct sales.
By region: North America, Latin America, East Asia, South Asia and Pacific, Western Europe, Eastern Europe, and Middle East and Africa.
Why does ammunition lead product type sales?
Ammunition will hold 27.4% of product type sales in 2026, as hunters replace rounds every season.
Table 4: Product Type Share for the Hunting Equipment and Accessories Market (percentage share), 2026
| Product Type | Share (2026) |
|---|---|
| Ammunition | 27.4% |
| Accessories and other hunting equipment | 72.6% |
| Total | 100% |
Table 5: Product Type Leadership and Market Growth for the Hunting Equipment and Accessories Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.3% |
| Leading Segment | Ammunition |
Demand for ammunition comes first in every hunting season, as hunters and sport shooters replace fired rounds each outing, even though handloaders can recharge spent cases with new primers, powder and bullets. FMI finds that ammunition accounts for 27.4% of product type sales in 2026.
- Ammunition holds 27.4% of product type sales in 2026, since every season of hunting needs fresh rounds that cannot be reused.
- Hunters comparing ammunition should check game-specific bullet design and local eco-friendly load rules, as these factors set repeat purchase cost.
Why do specialty stores lead distribution channel sales?
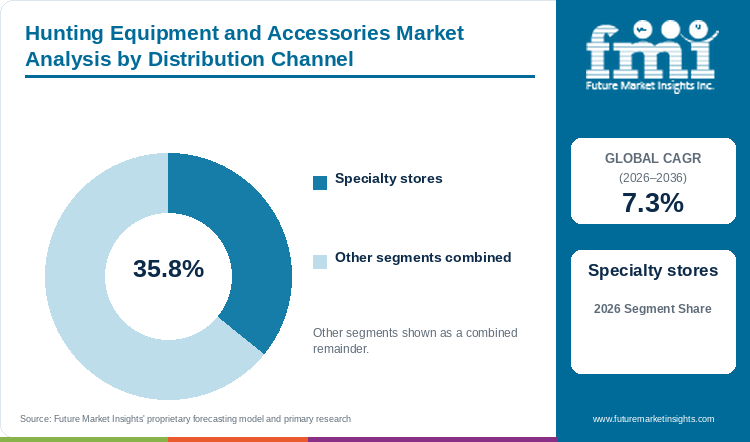
Specialty stores will hold 35.8% of distribution channel sales in 2026, with the remaining demand split across e-commerce, sporting goods chains, and direct sales.
Hunters buy most ammunition and firearms through specialty stores, as expert advice and in-store trials matter more for regulated gear than for general sporting goods. FMI estimates that specialty stores capture 35.8% of distribution channel sales in 2026. Other channels, including e-commerce and general sporting goods chains, carry more of the apparel and small accessory trade. Online retail remains a smaller channel for ammunition and firearms than specialty stores, a gap the U.S. Census Bureau's Q2 2026 retail data confirm [3]. Rifle-fitting workshops and shooting simulators are expected to keep specialty retail as the main buyers' channel through 2036.
- Specialty stores capture 35.8% of distribution channel sales in 2026, supported by expert advice and in-store rifle-fitting services.
- General sporting goods chains and online retailers often take apparel and accessory sales, as these items need less in-store fitting.
What are the drivers, restraints, and opportunities in the Hunting Equipment and Accessories Market?
A large licensed hunting and shooting base drives replacement ammunition demand, firearm ownership restrictions slow sales in some markets, and rising outdoor participation in China and India opens the main opportunity for both specialty and digital channels.
- Driver: Key drivers of the hunting equipment and accessories market include a large licensed hunting and target-shooting base that replaces ammunition and upgrades optics every season.
- Restraint: Firearm ownership restrictions in markets such as Japan keep per capita hunting equipment revenue low and slow sales of hunting equipment and accessories in those markets.
- Opportunity: Rising outdoor participation in China and India opens growth for both specialty retail and digital channels in the hunting equipment and accessories market.
Large Shooting Base Supports Replacement Demand
A large base of licensed hunters and sport shooters keeps replacement demand steady for ammunition and optics. This large licensed shooting base keeps specialty retailers investing in fitting services and shooting simulators to hold onto repeat buyers. Sales of ammunition and precision accessories are anticipated to stay the largest product type through 2036.
Ownership Restrictions Limit Some Markets
Firearm ownership restrictions limit hunting equipment sales in some developed markets. Japan's strict firearm licensing rules keep Japan's hunting equipment revenue per person below that of the United States, Australia, Germany and the United Kingdom, consistent with the report's country benchmarking. Every new hunter in such markets needs lengthy licensing and safety training before a first purchase, adding time before equipment sales follow. High licensing barriers may continue to slow equipment sales growth in these markets through the forecast period.
Outdoor Participation Growth Opens New Channels
Rising outdoor sports participation in Asia is opening new demand for hunting optics, apparel and accessories. More than 400 million people took part in outdoor sports in China in 2024, the General Administration of Sport of China reported in a report released in November 2025. Affordable entry-level gear and digital catalogues matter here, as new participants in China and India compare brands online before a specialty-store visit. Brands building both specialty retail presence and strong digital catalogues stand to gain new orders through 2036.
Which country CAGRs are profiled in the Hunting Equipment and Accessories Market?
Sales of hunting equipment and accessories in Australia grow fastest among the five profiled countries, at an 11.3% CAGR between 2026 and 2036, supported by an established and regulated hunting and recreational shooting culture. The USA posts the slowest rate at 4.6% through 2036.
Table 6: Country CAGRs and Primary Growth Levers for the Hunting Equipment and Accessories Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026–2036) | Primary Growth Lever |
|---|---|---|
| Australia | 11.3% | Established, regulated hunting and recreational shooting culture |
| China | 10.5% | Broad outdoor-sports participation proxy (hunting-specific data limited) |
| India | 7.7% | Licensed sport and target shooting; wildlife hunting restricted |
| Germany | 5.3% | Licensed hunters renewing ammunition and optics |
| USA | 4.6% | Replacement ammunition in a large, mature shooting base |
Source: Future Market Insights
Australia Hunting Equipment and Accessories Market Outlook (2026–2036)
Australia's established hunting and recreational shooting culture, supported by regulated state licensing systems, underpins the fastest profiled growth rate. FMI projects hunting equipment and accessories sales in Australia to expand at an 11.3% CAGR through 2036 as licensed hunters and sport shooters upgrade ammunition and optics.
Key takeaway: Regional specialty stores serving an established, licensed hunter base will keep most Australian ammunition and optics sales.
China Hunting Equipment and Accessories Market Outlook (2026–2036)
China's outdoor sports base passed 400 million participants in 2024, the General Administration of Sport of China reported in a national industry report released in November 2025; this is a broad outdoor-recreation figure, not a hunting-specific count, and China's hunting regime remains tightly restricted. FMI treats this as a directional indicator of rising demand for optics, apparel and accessories tied to outdoor and sport-shooting activity rather than wildlife hunting.
Key takeaway: Brands reaching China's broader outdoor-sports participant base through digital channels will capture early share in optics, apparel and accessories, more than in hunting-specific gear.
India Hunting Equipment and Accessories Market Outlook (2026–2036)
India's licensed hunting of wild animals is prohibited under the Wildlife Protection Act, 1972, so equipment demand in the country is tied to licensed sport and target shooting rather than wildlife hunting. FMI projects hunting equipment and accessories sales in India to expand at a 7.7% CAGR through 2036, supported by a small but growing base of target-shooting and airgun enthusiasts.
Key takeaway: Growth in India will track licensed sport-shooting and airgun participation rather than wildlife hunting, which remains legally restricted.
Germany Hunting Equipment and Accessories Market Outlook (2026–2036)
Germany is projected to add hunting equipment and accessories sales at a 5.3% CAGR through 2036, the fourth-fastest rate among profiled countries. German hunting law requires a licensing exam before a first firearm purchase, which keeps the buyer base smaller but steady. Specialty hunting retailers remain the main channel for licensed German hunters buying ammunition and optics. Demand for precision optics among trained hunters is expected to support steady replacement sales through 2036.
Key takeaway: Licensed hunters renewing ammunition and optics through specialty retailers will anchor German sales.
USA Hunting Equipment and Accessories Market Outlook (2026–2036)
The United States has the largest profiled hunting and shooting sports base, with more than 52.7 million sport and target shooters recorded in 2024 by the National Shooting Sports Foundation in a March 2025 study [2]. Hunting licenses generated USD 841 million for state wildlife agencies, the Congressional Sportsmen's Foundation reported in July 2025 [1]. U.S. sales are projected at a 4.6% CAGR for 2026 to 2036, the slowest rate among profiled countries, as the market is already large and mature. Specialty stores are expected to keep the lead in ammunition and firearm sales. E-commerce, still only 17.1% of total U.S. retail sales in the second quarter of 2026 [3], gains mainly in apparel and accessories.
Key takeaway: A large, mature shooting base will keep replacement ammunition sales steady even as growth slows.
Who are the notable companies in the Hunting Equipment and Accessories Market?
Federal Ammunition, Sturm Ruger & Co., Beretta, Leupold & Stevens, Vortex Optics, Tactacam, Mossy Oak, and Sitka Gear are the leading companies profiled in this market.
FMI profiles major suppliers ranging from large ammunition and firearm makers to specialised optics, apparel and electronics brands. Federal Ammunition (part of the Kinetic Group, acquired by Czechoslovak Group in November 2024 after Vista Outdoor divested its ammunition business), Olin Corporation (Winchester), Hornady, Sturm Ruger & Co., SIG Sauer, Browning (FN Group) and Beretta concentrate on firearms and ammunition. Leupold & Stevens, Vortex Optics, Bushnell, Swarovski Optik, Zeiss and Tactacam supply optics and field electronics; Mossy Oak and Sitka Gear supply camouflage apparel and field accessories.
- Firearms and ammunition specialists: Federal Ammunition (Kinetic Group/Czechoslovak Group), Olin Corporation (Winchester), Hornady, Sturm Ruger & Co., SIG Sauer, Browning (FN Group), and Beretta supply the rifles, shotguns and rounds hunters replace each season.
- Optics and technology providers: Leupold & Stevens, Vortex Optics, Bushnell, Swarovski Optik and Zeiss supply riflescopes and optics, and Tactacam adds field cameras and digital ballistics tools.
- Apparel and accessories makers: Mossy Oak and Sitka Gear supply camouflage apparel and field accessories.
Competitive Benchmarking: Hunting Equipment and Accessories Market
Table 7: Competitive Benchmarking for the Hunting Equipment and Accessories Market (qualitative capability ratings), 2025
| Company | Ammunition/Firearms | Optics | Specialty Retail | Reach |
|---|---|---|---|---|
| Olin Corporation (Winchester) | High | Medium | High | High |
| Federal Ammunition | High | Low | High | High |
| Sturm Ruger & Co. | High | Low | Medium | High |
| SIG Sauer | High | Low | Medium | Medium |
| Beretta | High | Medium | High | High |
| Leupold & Stevens | Low | High | Medium | Medium |
| Vortex Optics | Low | High | Medium | Medium |
| Tactacam | Low | Medium | Low | Medium |
| Mossy Oak | Low | Low | Medium | High |
| Sitka Gear | Low | Low | Low | Medium |
Key Developments in the Hunting Equipment and Accessories Market
- In July 2025, the Congressional Sportsmen's Foundation reported that hunting licenses generated USD 841 million for state wildlife agencies in a National ASCF Fact Sheet [1].
- In March 2025, the National Shooting Sports Foundation reported that more than 52.7 million people took part in sport and target shooting in the United States in 2024 [2].
- In November 2025, the General Administration of Sport of China reported that more than 400 million people took part in outdoor sports in China in 2024.
- In August 2026, the U.S. Census Bureau reported that e-commerce accounted for 17.1% of total U.S. retail sales in the second quarter of 2026 [3].
Key Players in the Hunting Equipment and Accessories Market
Firearms and Ammunition Specialists
- Federal Ammunition (Kinetic Group / Czechoslovak Group)
- Olin Corporation (Winchester)
- Sturm Ruger & Co.
- SIG Sauer
- Beretta
Optics and Technology Providers
- Leupold & Stevens
- Vortex Optics
- Bushnell
Apparel and Accessories Makers
- Mossy Oak
- Sitka Gear
Hunting Equipment and Accessories Market - Report Scope
Table 8: Report Scope for the Hunting Equipment and Accessories Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Product type; distribution channel; region |
| Quantitative units | USD billion |
| Market definition | Sales from the first sale of ammunition, firearms, optics, apparel and related hunting accessories through specialty stores and other distribution channels. Hunting licenses, land leases and services unconnected to equipment sale are excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | India; China; Australia; Germany; USA |
| Key companies profiled | Federal Ammunition (Kinetic Group), Olin Corporation (Winchester), Sturm Ruger & Co., SIG Sauer, Beretta, Leupold & Stevens, Vortex Optics, Bushnell, Tactacam, Mossy Oak, Sitka Gear |
| Forecast period | 2026 to 2036 |
| Approach | A hybrid bottom-up and top-down model, built to reconcile licensed hunter counts, replacement cycles, specialty retail activity and country participation data, checked against trade body and government data and primary interviews. |
Hunting Equipment and Accessories Market - Research Methodology
Table 9: Research Methodology for the Hunting Equipment and Accessories Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary research includes interviews with equipment suppliers, specialty retailers, and hunter and shooting sports associations. Interviews cover replacement cycles, channel preferences and product pricing. |
| Desk Research | Desk research draws on supplier filings, government wildlife agency data, participation studies and trade body statistics. |
| Market Sizing and Forecasting | Sizing starts from the 2025 market value and adds licensed hunter counts, replacement cycles, average equipment price, segment splits and participation growth in each country. |
| Data Validation | Each estimate is tested against supplier disclosures, participation data and primary interviews. |
Hunting Equipment and Accessories Market by Segments
Hunting Equipment and Accessories Market segmented by Product Type:
- Ammunition
- Accessories and other hunting equipment
Hunting Equipment and Accessories Market segmented by Distribution Channel:
- Specialty stores
- Other channels (e-commerce, sporting goods chains, direct sales)
Hunting Equipment and Accessories Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Asia and Pacific
- India
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Congressional Sportsmen's Foundation. (2025, July). National ASCF Fact Sheet 2025.https://congressionalsportsmen.org/wp-content/uploads/2025/07/National-ASCF-Fact-Sheet_2025.pdf
- [2] National Shooting Sports Foundation. (2025, March). Firearm Ownership and Sport Shooting Participation in the U.S. in 2024 (2025 Edition).https://www.nssf.org/research/nsga-participation-reports/
- [3] U.S. Census Bureau. (2026, August 18). Quarterly Retail E-Commerce Sales, 2nd Quarter 2026.https://www.census.gov/retail/ecommerce.html
This Report Answers
- What value will hunting equipment and accessory sales reach in 2026?
- By 2036, what market value will hunting equipment and accessories reach?
- Which product type takes the largest share of sales?
- Which distribution channel do hunters favor for ammunition and firearms?
- Which profiled countries show the fastest growth in hunting equipment sales?
- Which companies lead the supply of hunting equipment and accessories?
Frequently Asked Questions
What is the hunting equipment and accessories market worth in 2026?
Hunting equipment and accessory sales are valued at USD 29.0 billion in 2026, according to FMI. The market will reach USD 58.7 billion by 2036 as hunters replace ammunition and upgrade optics each season.
What CAGR is projected for the hunting equipment and accessories market through 2036?
FMI projects a 7.3% CAGR for the hunting equipment and accessories market from 2026 to 2036. A large licensed hunting base and rising outdoor participation in Asia will support much of this growth.
Which product type holds a notable share in 2026?
Ammunition holds 27.4% of product type sales in 2026. Hunters buy fresh rounds every season instead of reusing old stock.
Which distribution channel holds a notable share in 2026?
Specialty stores account for 35.8% of distribution channel sales in 2026. Hunters select this channel for expert advice and in-store rifle fitting.
Which country has a notable growth outlook through 2036?
Australia leads the profiled countries with an 11.3% CAGR for hunting equipment and accessory sales over 2026 to 2036. An established, regulated hunting and recreational shooting culture supports this pace.
Who are the key companies in the hunting equipment and accessories market?
Key companies include Federal Ammunition (Kinetic Group/Czechoslovak Group), Olin Corporation (Winchester), Hornady, Sturm Ruger & Co., SIG Sauer, Browning (FN Group), Beretta, Leupold & Stevens, Vortex Optics, Bushnell, Swarovski Optik, Zeiss, Tactacam, Mossy Oak, and Sitka Gear. These suppliers compete on product range, specialty retail reach and digital catalogues.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Ammunition
- Accessories and other hunting equipment
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Specialty stores
- Other channels (e-commerce, sporting goods chains, direct sales)
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Product Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- By Product Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- Australia and New Zealand
- By Product Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Olin Corporation (Winchester)
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Federal Ammunition
- Sturm Ruger & Co.
- SIG Sauer
- Beretta
- Leupold & Stevens
- Vortex Optics
- Tactacam
- Mossy Oak
- Sitka Gear
- Federal Ammunition (Kinetic Group / Czechoslovak Group)
- Bushnell
- Olin Corporation (Winchester)
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


