

- Market Size (2026)
- USD 1193.9 Mn
- Forecast (2036)
- USD 9159.4 Mn
- CAGR (2026 to 2036)
- 22.6%
How big is Headless CMS Software Market in 2026?
The global headless CMS software market is estimated at USD 973.8 million in 2025 and is expected to reach USD 1,193.9 million in 2026. By 2036, the market is projected to reach USD 9,159.4 million, expanding at a CAGR of 22.6% from 2026. Large enterprises will hold the largest share of enterprise size sales in 2026, at 56.7%, as per FMI analysis.
Sales of headless CMS software are rising as companies move content into cloud services that feed websites, apps and AI assistants from one source. Evidence of this comes from Eurostat, as 52.7% of EU enterprises paid for cloud services in 2025, up 7.4 percentage points from 2023 [1]. Consequently, fewer buyers need new infrastructure before switching to API-first platforms. Demand for content platforms among large brands is also growing with online audiences, which reached about 6 billion people in 2025, up from a revised 5.8 billion in 2024 [2]. Large software groups are responding, as Salesforce agreed on 1 June 2026 to acquire Contentful, a composable content platform used by more than 4,800 brands, and completed the deal on 1 September 2026 [3]. Adoption of headless content inside CRM suites is therefore likely to reach many more enterprise buyers. FMI analysis expects such deals to keep pulling large companies toward API-first content tools.
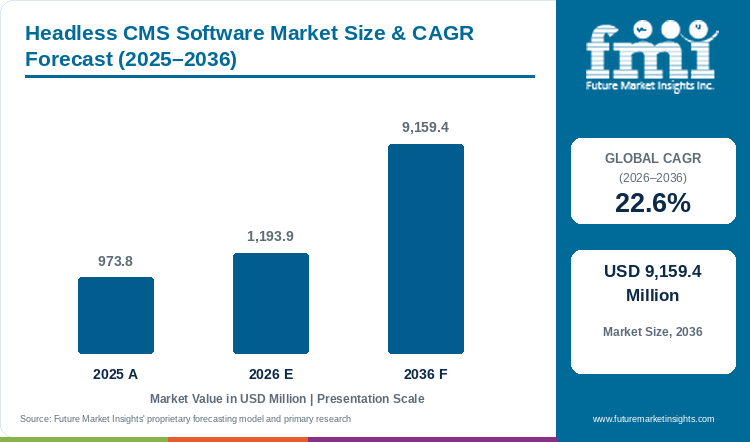
Table 1: Headless CMS Software Market Size and Forecast (USD million), 2025 to 2036
| Market size and forecast | Value |
|---|---|
| 2025 market size | USD 973.8 million |
| Estimated market size in 2026 | USD 1,193.9 million |
| Projected market size by 2036 | USD 9,159.4 million |
| CAGR (2026 to 2036) | 22.6% |
| Added sales, 2026 to 2036 | USD 7,965.5 million |
Key Market Trends & Insights
- By solution: Headless CMS software tools are likely to account for 64.2% of 2026 sales, as every project starts with the content store, editor and APIs, and services such as migration come later.
- By enterprise size: Large enterprises will hold 56.7% of 2026 sales, as big brands run dozens of sites and apps in many languages from one controlled content store.
- By deployment: With an estimated 68.4% share in 2026, cloud-based deployment leads the category, as hosted plans remove server upkeep and let marketing teams publish without waiting on developers.
Regional Highlights
- Fastest-growing country: India is projected to grow at a CAGR of 26.1% between 2026 and 2036, the fastest among profiled countries, as IT services teams build modular websites for clients at home and abroad.
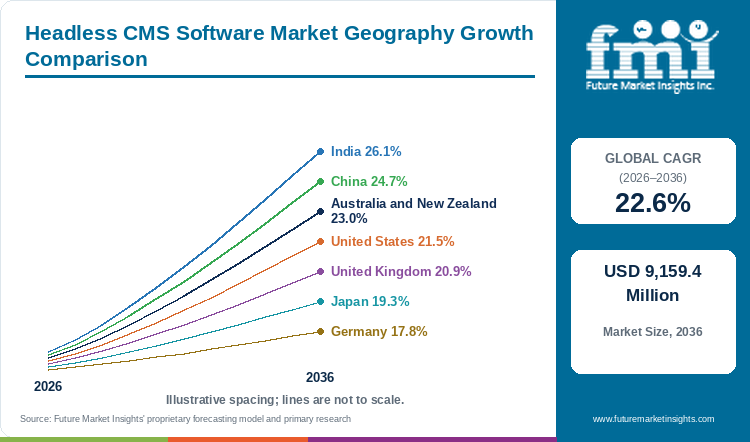
- Growth across other countries: China at 24.7% and Australia and New Zealand at 23% also run ahead of the 22.6% global pace. The United States (21.5%), the United Kingdom (20.9%) and Japan (19.3%) grow more slowly, as many large suites are already in use there. Germany is expected to grow slowest, at a CAGR of 17.8%, as in-house servers and strict hosting rules slow the move to the cloud.
Most new content projects now sit on cloud hosting, which speeds up headless rollouts. Among EU enterprises buying cloud services in 2025, 45.5% used the cloud to host the company database and 26.1% used platforms for developing, testing or deploying applications [1]. Hence, many companies already have the hosted databases and build tools that a headless setup needs. Supply of front-end tools is expanding in parallel, and Vercel raised a USD 300 million Series F at a USD 9.3 billion valuation in September 2025. The company also said Next.js was downloaded over 500 million times in the prior 12 months [4]. Consequently, developers have proven website tools that pull content through APIs. Mature tools of this kind lower the cost of building headless sites.
Large software vendors are moving deeper into content and search, and deals are reshaping the supplier field. Adobe reported Digital Experience segment sales of USD 5.86 billion for fiscal 2025, up 9% year over year [5]. Steady growth in a mature business shows that large buyers keep paying for website and marketing software. In addition, Adobe agreed in November 2025 to acquire Semrush for a total equity value of about USD 1.9 billion, at USD 12.00 per share in cash [6]. As a result, software suites now combine content tools with tools that help brands appear in AI search results. Stand-alone headless vendors therefore need stronger analytics and search features to compete.
Popularity of AI agents is moving headless platforms toward tools that put content together automatically. Contentstack introduced an Agentic Experience Platform in June 2026, with general availability of Agent OS, an autonomous agent layer for content, data and real-time personalisation [7]. Thus, well-organised content is becoming a data source that agents read, which favours vendors with structured content stores. Regulation gives retailers selling into Europe a further reason to reorganise content. Under the European Accessibility Act, products and services such as e-commerce websites and mobile apps need to be accessible after 28 June 2025 [8]. Accordingly, retailers selling into the EU need content that works with screen readers and other assistive tools. Keeping content separate from page design makes such fixes faster to roll out on every channel.
Table 2: Supporting Industry Indicators for the Headless CMS Software Market, 2024 to 2026
| Indicator | Data point | Why it matters | Source |
|---|---|---|---|
| Paid cloud adoption | 52.7% of EU enterprises paid for cloud services in 2025, up 7.4 percentage points from 2023 | A cloud-ready base shortens the switch to SaaS content platforms | [1] |
| Cloud database hosting | 45.5% of EU enterprises buying cloud services hosted the company database in the cloud in 2025 | Decoupled content stacks rely on hosted data layers | [1] |
| Internet users | About 6 billion people online in 2025, up from a revised 5.8 billion in 2024 | More users widen the channels that brand content needs to reach | [2] |
| US e-commerce sales | USD 340.2 billion in the second quarter of 2026, up 12.2% year on year and 17.1% of total retail sales | Online retail is a core buyer of fast, multi-channel content | [9] |
| Experience software sales | Adobe Digital Experience segment sales of USD 5.86 billion in fiscal 2025, up 9% | Gauge of enterprise budgets for experience software | [5] |
| Suite consolidation | Adobe agreed to acquire Semrush for about USD 1.9 billion in November 2025 | Suites are adding AI search visibility to content tools | [6] |
| CRM and content consolidation | Salesforce agreed on 1 June 2026 to acquire Contentful, used by more than 4,800 brands, and completed the deal on 1 September 2026 | Headless content moves inside CRM suites | [3] |
| Venture funding | Sanity raised a USD 85 million Series C in May 2025; annual recurring revenue exceeded USD 40 million in 2024 | Investors keep backing independent API-first vendors | [10] |
| Front-end framework use | Next.js downloaded over 500 million times in the 12 months to September 2025; Vercel raised USD 300 million | Front-end frameworks pull content through APIs | [4] |
| Agentic content platforms | Contentstack made Agent OS generally available in June 2026 | AI agents read structured content directly | [7] |
| Accessibility regulation | European Accessibility Act requirements apply to e-commerce websites and apps after 28 June 2025 | Compliance projects favour decoupled front ends | [8] |
Demand Intensity Analysis
Adobe's marketing software business gives a clear outside measure for sizing headless content tools. Adobe reported Digital Experience segment sales of USD 5.86 billion in fiscal 2025 [5]. The market is estimated at USD 973.8 million in 2025, equal to about 16.6% of that single segment, or roughly one-sixth. The two figures cover different products, since the Adobe segment also covers analytics, commerce, workflow and customer data products. Even so, the ratio shows that headless tools are still a small part of large firms' website budgets. The small share leaves wide room for headless tools to grow over the decade.
The large enterprise segment allows a closer comparison with Adobe. At a 56.7% share of the USD 1,193.9 million estimated for 2026, the large enterprise segment comes to about USD 676.9 million. That equals 11.6% of Adobe Digital Experience sales for fiscal 2025 [5]. Large buyers already pay at that scale for marketing suites. Moving even a small part of those budgets to API-first content tools would add heavily to segment sales. Large enterprise demand will therefore come mainly from buyers moving budgets away from marketing suites.
Cloud use among companies gives a volume check on the forecast. Eurostat put paid cloud use at 52.7% of EU enterprises in 2025, up 7.4 percentage points from 2023 [1]. That implies a 2023 share of 45.3% and a CAGR of about 7.9% in the number of cloud users. Set against the 22.6% CAGR for 2026 to 2036, the gap implies about 13.7% annual growth in value per cloud user. The Eurostat series counts any paid cloud service in the EU, so the comparison is indicative only. The forecast therefore assumes that existing users add seats, channels and higher-priced plans over the decade.
Audience size gives another way to judge the estimate. ITU counted roughly 6 billion Internet users in 2025 [2]. At USD 973.8 million, the market is estimated at about USD 0.16 per internet user in 2025. US online retail gives a commerce comparison, with e-commerce sales of USD 340.2 billion in the second quarter of 2026, up 12.2% year on year [9]. The 22.6% CAGR runs well ahead of that 12.2% sales growth. The outlook thus rests on more content per channel and more channels per brand, on top of retail volume.
Table 3: Demand Intensity Metrics for the Headless CMS Software Market, 2023 to 2026 Data Against 2025 and 2026 Market Values
| Demand intensity metric | Value | Basis |
|---|---|---|
| Adobe Digital Experience segment sales, fiscal 2025 | USD 5.86 billion | Adobe, fiscal 2025 results |
| Market value as a share of Adobe Digital Experience sales | 16.6% | Calculated from Adobe fiscal 2025 results and the 2025 market value |
| Large enterprise segment as a share of Adobe Digital Experience sales | 11.6% | Calculated from Adobe fiscal 2025 results and the 2026 large enterprise share |
| EU enterprises paying for cloud services, 2025 | 52.7% | Eurostat, 2025 data on EU enterprises |
| EU enterprises paying for cloud services, 2023 | 45.3% | Calculated from the Eurostat 2025 share and the 7.4 percentage point rise |
| Annual growth in paid cloud adoption, 2023 to 2025 | 7.9% | Calculated from Eurostat 2023 and 2025 shares |
| Implied annual value growth per adopting enterprise | 13.7% | Calculated from the 22.6% CAGR and Eurostat adoption growth |
| Internet users, 2025 | About 6 billion | International Telecommunication Union, 2025 estimate |
| Market value per internet user, 2025 | USD 0.16 | Calculated from ITU 2025 users and the 2025 market value |
| US e-commerce sales growth, second quarter 2026 | 12.2% | U.S. Census Bureau, quarterly e-commerce estimate |
Analyst Perspective
“Content is turning into core infrastructure, and large firms now want one structured store that feeds websites, apps and AI agents. The big suites are buying API-first vendors to supply that layer. Independent platforms will keep securing projects led by developers, though large buyers will more often get headless content as part of a CRM or marketing suite.”
- Sudip saha, Principal Consultant, Future Market Insights.
How is the headless CMS software market segmented?
The market is segmented into solution, enterprise size, deployment, end use, and region. Large enterprises are expected to lead enterprise size with 56.7% share in 2026, and cloud-based deployment leads deployment with an estimated 68.4%.
By solution: headless CMS software tools and headless CMS software services.
By enterprise size: large enterprises and SMEs.
By deployment: cloud-based and on-premise.
By end use: IT and telecom, retail and e-commerce, BFSI, media and entertainment, healthcare, government, travel and hospitality, and others.
By region: editorial teams, front-end developers and marketing departments spread over North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do headless CMS software tools lead by solution?
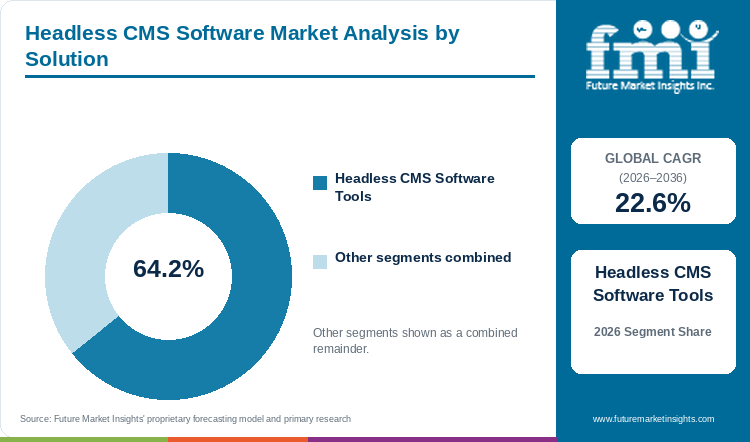
Headless CMS software tools are expected to lead solution sales with 64.2% share in 2026, ahead of headless CMS software services at an estimated 35.8%.
Table 4: Solution Share for the Headless CMS Software Market (percentage share), 2026
| Solution | Estimated Share (2026) |
|---|---|
| Headless CMS Software Tools | 64.2% |
| Headless CMS Software Services | 35.8% |
| Total | 100.0% |
Table 5: Solution Leadership and Market Growth for the Headless CMS Software Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 22.6% |
| Leading Segment | Headless CMS Software Tools |
Sales of software tools make up the larger share, since every project starts with a subscription to the content store, editor and APIs. FMI places tools at 64.2% of 2026 sales, against 35.8% for services such as migration, integration and support. Use of services grows with project size, as large sites need content planning and links to commerce and CRM systems. Funding for tool vendors remains strong, and Sanity raised a USD 85 million Series C in May 2025 after annual recurring revenue exceeded USD 40 million in 2024 [10]. New money of this size pays for product features, which keeps subscription tools ahead of services. The wider web content management market is projected to expand at a 16.2% CAGR from 2024 to 2034, slower than headless tools. Services will still gain as AI agent projects add integration work through 2036.
- Content repositories, visual editors, delivery APIs and software development kits make up the tools segment.
- Developer communities influence which tools are chosen for new websites, and Sanity counted more than 30,000 organizations on the platform at the May 2025 round [10]. A broad base of small teams gives vendors a path to sell paid enterprise plans later.
Why do large enterprises lead by enterprise size?
Large enterprises are expected to lead enterprise size sales with 56.7% share in 2026, ahead of SMEs at an estimated 43.3%.
Table 6: Enterprise Size Share for the Headless CMS Software Market (percentage share), 2026
| Enterprise Size | Estimated Share (2026) |
|---|---|
| Large Enterprises | 56.7% |
| SMEs | 43.3% |
| Total | 100.0% |
Large enterprises account for 56.7% of 2026 sales, as global brands run dozens of regional sites, apps and campaign pages from one controlled content source. Buyer preference for lower-cost plans and open-source tools keeps SMEs at an estimated 43.3%, as a small team can run such tools. Large accounts also buy through CRM and suite vendors. Salesforce described Contentful as trusted by over 4,800 of the world's leading brands when announcing the acquisition in June 2026 [3]. Hence, large buyers can now add headless content through an existing CRM contract, which shortens buying cycles. SMEs are likely to gain share slowly as starter plans and templates make setup easier. Large enterprises will still hold the lead through 2036, given the larger volume of content that big companies manage.
- Global consumer brands, banks, publishers and multi-site retailers form the large enterprise group.
- Suite vendors are widening the offer to large accounts, and Adobe agreed to buy Semrush in November 2025 to help marketers remain discoverable in AI search [6]. Large buyers can therefore get content and search tools from one supplier, which raises the cost of switching to stand-alone vendors.
Why does cloud-based deployment lead by deployment?
Cloud-based deployment is expected to lead deployment sales with 68.4% share in 2026, ahead of on-premise deployment at an estimated 31.6%.
Table 7: Deployment Share for the Headless CMS Software Market (percentage share), 2026
| Deployment | Estimated Share (2026) |
|---|---|
| Cloud-based | 68.4% |
| On-premise | 31.6% |
| Total | 100.0% |
Adoption of cloud-based deployment is widest, with an estimated 68.4% of 2026 sales, as SaaS plans remove server upkeep and scale automatically during traffic peaks. Buyer preference for in-house servers keeps on-premise deployment near 31.6%, mainly in banks, public agencies and companies with strict data-residency rules. Broader cloud use supports the lead, as Eurostat reported that 52.7% of EU enterprises paid for cloud services in 2025, with Finland at 79.2% and Italy at 75.6% [1]. High adoption in such countries makes SaaS the default choice for new content projects. Delivery networks grow alongside, and the content delivery network market is forecast to rise from USD 18.84 billion in 2026 to USD 80.3 billion by 2036. On-premise share is expected to fall gradually as regulated buyers adopt sovereign cloud regions.
- Multi-tenant SaaS, single-tenant private cloud and hybrid set-ups make up cloud-based deployment.
- Front-end hosting is moving to the same cloud model, and Vercel raised USD 300 million in a Series F co-led by Accel and GIC in September 2025 [4]. Cloud-hosted websites work well with SaaS content APIs, which strengthens cloud deployment on new projects.
Why does IT and telecom lead by end use?
IT and telecom is expected to lead end use sales with 22.4% share in 2026, ahead of retail and e-commerce at an estimated 18.6% and BFSI near 15.2%.
Table 8: End Use Share for the Headless CMS Software Market (percentage share), 2026
| End Use | Estimated Share (2026) |
|---|---|
| IT and Telecom | 22.4% |
| Retail and E-commerce | 18.6% |
| BFSI | 15.2% |
| Media and Entertainment | 13.1% |
| Healthcare | 10.3% |
| Government | 8.2% |
| Travel and Hospitality | 6.5% |
| Others | 5.7% |
| Total | 100.0% |
IT and telecom companies lead end use with 22.4% of 2026 sales, as software companies and telecom operators run developer portals, self-service apps and product sites that change weekly. Retail and e-commerce, near 18.6%, needs product pages that update fast on websites, apps and marketplaces. BFSI, at about 15.2%, values tightly controlled content for regulated product details, and media and entertainment holds 13.1%. Healthcare at 10.3%, government at 8.2%, travel and hospitality at 6.5% and others at 5.7% complete the mix. Retail demand rests on steady online sales growth, and US e-commerce sales reached USD 340.2 billion in the second quarter of 2026, or 17.1% of total retail sales [9]. A growing online share pushes retailers to publish product content faster, which supports headless tools in commerce. Storefront software is expanding too, with the e-commerce platform market projected at a 20.2% CAGR from 2025 to 2035. FMI expects retail and e-commerce to narrow the gap with IT and telecom over the decade.
- Software vendors, telecom operators, IT services providers and cloud companies form the IT and telecom group.
- Retail compliance work is adding to headless projects, since the European Accessibility Act covers e-commerce, defined as websites or mobile apps through which companies sell products or services online [8]. Retailers rebuilding websites for accessibility often separate content from design at the same time, which adds demand in commerce.
What are the drivers, restraints, and opportunities in the headless CMS software market?
Key drivers of the headless CMS software market include publishing to many channels and wider cloud use. Migration work and scarce developer time slow smaller buyers. AI agents that read structured content open new projects for vendors.
- Driver: Brands publish to websites, apps, kiosks and AI assistants, so a single structured repository saves editing effort and keeps messages consistent across channels.
- Restraint: Moving content out of older suites needs restructuring, new websites and developer time, which delays projects at companies with small technical teams.
- Opportunity: AI agents that build pages from structured content create demand for better-organised content, approval controls and APIs that agents can use.
Multi-Channel Delivery Pushes Content Out of Page Templates
Each new channel beyond the website raises demand for headless CMS software. Consumption of online content keeps widening, and more than 240 million people joined the online population in 2025 [2]. Most new users arrive on mobile devices, which increases the number of formats a content team serves. Commerce adds a second push, as US e-commerce sales grew 12.2% from the second quarter of 2025 to the second quarter of 2026 [9]. Faster online sales growth keeps product content under constant change, which suits API-first content stores. FMI views multi-channel delivery as the main driver through 2036.
Migration Effort Holds Back Smaller Buyers
Migration remains the main brake on growth, since moving pages out of an all-in-one suite needs new content structures and a separate website layer. A lack of clear ownership adds to the delay, and Contentstack cited a finding that 42% of organizations say the lack of a clear internal owner has delayed agentic AI initiatives [7]. Unclear ownership slows content projects as well, since the same teams usually run both. Older content stores are large, and the enterprise content management market is estimated at USD 19.6 billion in 2025 with an 8.7% CAGR to 2035. Vendors with migration services and ready templates will convert hesitant buyers faster. Smaller companies will move later in the forecast period.
AI Agents Open New Content Projects
AI agents that query content directly are set to drive more of the growth of the headless CMS software market. Salesforce said Contentful's structured content would be accessible to Agentforce, which could query and assemble content without manual publishing steps [3]. Agent access turns the content store into a live data source, which raises the value of well-organised content. Contentstack is moving in the same direction and reported that an internal agent project cut manual effort by 95% [7]. Gains of this size encourage buyers to pay for reorganising content. Vendors with agent-ready APIs will secure the next wave of enterprise projects.
Which country CAGRs are profiled in the headless CMS software market?
Table 9: Country CAGR Comparison for the Headless CMS Software Market (CAGR percentage), 2026 to 2036
| Country | CAGR |
|---|---|
| India | 26.1% |
| China | 24.7% |
| Australia and New Zealand | 23% |
| United States | 21.5% |
| United Kingdom | 20.9% |
| Japan | 19.3% |
| Germany | 17.8% |
How do country-level CAGRs compare in the headless CMS software market?
FMI projects India at the top with a 26.1% CAGR, 3.5 points above the 22.6% global rate, as IT exporters build modular websites for clients abroad. China comes next at 24.7%, and Australia and New Zealand are close behind at 23%. The United States is projected at 21.5%, slightly below the global pace, given the many large suites already in use. The United Kingdom at 20.9% and Japan at 19.3% grow more slowly, and Germany is lowest at 17.8%. The 8.3-point spread shows how far each country has already moved content to the cloud.
- Indian IT services companies build headless front ends for overseas clients, and those teams later serve domestic retailers and banks. Vendors with partner programmes gain a low-cost route to scale.
- In China, super-apps and mini-programs multiply the places brands publish, which favours domestic API-first vendors that host data locally.
- In Australia and New Zealand, high cloud use and English-language content let global SaaS vendors sell with little local adaptation.
- In the United States, many companies already run large marketing suites, which slows full migrations, although commerce and media brands adopt headless tools first. Suppliers gain most by replacing suite modules one channel at a time.
- Public digital services in the United Kingdom favour open standards, which supports API-first content tools in government and charity projects.
- Japanese companies move slowly away from in-house systems, and growth comes mainly from consumer brands rebuilding apps. Vendors with strong local partners benefit most from that shift.
- A preference for in-house hosting and strict data rules slows SaaS use in Germany, so vendors offering EU or self-hosted options hold an edge.
Full report country CAGRs cover: seven profiled rates running from 17.8% in Germany to 26.1% in India, plus regional tables for every other standard country.
Country-wise Analysis
India Headless CMS Software Market Outlook (2026 to 2036)
Indian IT services companies build modular websites for global clients, and that experience now flows into local banking, retail and media projects. Rising internet use adds audiences in many regional languages, which multiplies content variants per brand. Indian headless CMS adoption is set to expand at a 26.1% CAGR, the fastest rate in the table.
Key takeaway: Adoption of headless CMS software in India will lead the table, as IT services teams reuse export skills for brands serving many languages.
China Headless CMS Software Market Outlook (2026 to 2036)
Chinese brands publish across apps, mini-programs and online stores, so a single content source cuts a lot of repeated work. Data localisation rules steer buyers toward domestic vendors and local cloud hosting. China is expected to grow at a 24.7% CAGR through 2036, well above the global rate.
Key takeaway: Chinese brands publishing to super-apps and mini-programs will buy mostly from local API-first vendors that host content data inside China.
Australia and New Zealand Headless CMS Software Market Outlook (2026 to 2036)
Retailers, universities and public agencies in Australia and New Zealand already run most website work on SaaS. Global vendors can therefore sell API-first content tools with little adaptation. Demand in Australia and New Zealand is set to rise at a 23% CAGR, slightly ahead of the global figure.
Key takeaway: Retailers and universities in Australia and New Zealand already use SaaS widely, so global headless vendors can sign new clients with little local change.
United States Headless CMS Software Market Outlook (2026 to 2036)
Online retail in the United States keeps adding channels for brands to serve. American online stores sold USD 340.2 billion of goods in the second quarter of 2026, a 12.2% gain on a year earlier [9]. Faster commerce growth pushes retailers toward content that feeds web, app and marketplace listings from one place. Many large companies already run marketing suites, which slows full replacements, so the United States is projected to grow at a 21.5% CAGR. Purchases made through CRM and marketing suites from Salesforce and Adobe will account for much of the demand.
Key takeaway: Online retail growth will drive headless CMS sales in the United States, though large existing marketing suites will slow the pace of change.
United Kingdom Headless CMS Software Market Outlook (2026 to 2036)
Government services, charities and online retailers in the United Kingdom favour open standards and reusable content blocks. Publishers add steady demand as news and broadcast brands rebuild apps around structured content. FMI expects British headless CMS sales to rise at a 20.9% CAGR, under the world figure.
Key takeaway: UK public bodies, charities and publishers prefer open standards, which keeps purchases of API-first content tools close to the global pace.
Japan Headless CMS Software Market Outlook (2026 to 2036)
In Japan, in-house content systems remain common, as companies replace older platforms slowly. Consumer electronics, retail and travel brands lead the move to headless tools as app traffic grows. Japanese adoption is set for 19.3% annual growth, behind the global average.
Key takeaway: Japanese companies replace in-house content systems slowly, so most new headless sales will come from consumer brands rebuilding mobile apps.
Germany Headless CMS Software Market Outlook (2026 to 2036)
Growth of the headless CMS software market in Germany is supported by accessibility rules for online retailers. The European Accessibility Act requires covered e-commerce websites and apps to be accessible after 28 June 2025 [8]. Compliance projects often include a website rebuild, which opens a door for headless tools. Buyer preference for in-house hosting still slows SaaS use. Germany is expected to grow at a 17.8% CAGR, the slowest profiled rate. Vendors that keep data inside the EU will gain the most from this work.
Key takeaway: German retailers will buy headless tools for accessibility rebuilds, but a strong preference for in-house hosting leaves Germany growing the slowest.
Who are the notable companies in the headless CMS software market?
Content platform vendors covered here are Contentful, Contentstack, Storyblok, Sanity, Hygraph, Kontent.ai, Adobe, Sitecore, Optimizely, Bloomreach, Magnolia, Crownpeak, Strapi, Directus, Craft CMS, Ghost, DatoCMS, ButterCMS and Agility CMS.
Companies at the top of the headless CMS software market split into API-first specialists, suite vendors adding headless options and open-source projects with paid cloud plans. FMI sees consolidation as the defining trend, as CRM and marketing suite vendors buy content platforms. Salesforce completed the Contentful acquisition on 1 September 2026, three months after signing the agreement [3]. The move gives Salesforce a built-in content layer for Agentforce, which pushes independent vendors to deepen links with CRM systems. Independent vendors still attract capital, and Sanity raised a USD 85 million Series C led by Bullhound Capital [10]. Funding of this kind keeps specialists competitive on developer experience. Specialists will therefore compete on flexible content structures and open standards.
- API-first content platform vendors: Contentful, Contentstack, Storyblok, Sanity, Hygraph and Kontent.ai.
- Suite vendors with headless modules: Adobe, Sitecore, Optimizely, Bloomreach, Magnolia and Crownpeak.
- Open-source and developer-led tools: Strapi, Directus, Craft CMS, Ghost, DatoCMS, ButterCMS and Agility CMS.
Competitive Benchmarking: Headless CMS Software Market
Table 10: Competitive Benchmarking for the Headless CMS Software Market (qualitative ratings), 2026
| Company | API-first Architecture | Enterprise Suite Reach | AI Agent Features | Recent Activity |
|---|---|---|---|---|
| Contentful | High | High | High | High |
| Contentstack | High | Medium | High | High |
| Sanity | High | Medium | Medium | High |
| Storyblok | High | Low | Medium | Medium |
| Adobe | Medium | High | High | High |
| Sitecore | Medium | High | Medium | Medium |
| Strapi | High | Low | Low | Low |
Ratings compare the companies on API-first architecture, enterprise suite reach, AI agent features and recent activity.
Key Developments in the Headless CMS Software Market
- Salesforce completed the acquisition of Contentful on 1 September 2026, adding a headless content layer to the Salesforce stack [3]. Buyers who start from CRM gain a single route to content, data and agents.
- In June 2026, Contentstack made Agent OS generally available within a new Agentic Experience Platform [7]. Content that AI agents can use is becoming a selling point in enterprise tenders.
- Adobe agreed on 19 November 2025 to acquire Semrush for about USD 1.9 billion in cash [6]. Content suites now reach into AI search visibility, which gives buyers more features to compare.
- On 10 December 2025, Adobe reported fiscal 2025 Digital Experience segment sales of USD 5.86 billion, up 9% [5]. Steady suite sales confirm that large firms keep paying for marketing software.
- Vercel secured USD 300 million in Series F funding at a USD 9.3 billion valuation in September 2025 [4]. Investment in website hosting strengthens the website tools that deliver headless content.
- A USD 85 million Series C for Sanity, announced in May 2025, was led by Bullhound Capital [10]. Fresh capital keeps independent API-first vendors in contention against suite owners.
- European Accessibility Act requirements began to apply to e-commerce websites and apps on 28 June 2025 [8]. Retailers in the EU face website work that often includes separating content from design.
- Eurostat reported on 3 February 2026 that 52.7% of EU enterprises paid for cloud services in 2025 [1]. Wider cloud use lowers the setup barriers for SaaS content platforms.
Key Players in the Headless CMS Software Market
API-first Platforms
- Contentful
- Contentstack
- Storyblok
- Sanity
- Hygraph
- Kontent.ai
Suite Vendors with Headless Modules
- Adobe
- Sitecore
- Optimizely
- Bloomreach
- Magnolia
- Crownpeak
Open-source and Developer-led Tools
- Strapi
- Directus
- Craft CMS
- Ghost
- DatoCMS
- ButterCMS
- Agility CMS
Headless CMS Software Market - Report Scope
Table 11: Report Scope for the Headless CMS Software Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Solution; enterprise size; deployment; end use; region |
| Quantitative units | USD million |
| Market definition | API-first content management software that stores structured content apart from presentation and delivers the content to websites, apps and other channels, with related implementation and managed services. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | India; China; Australia and New Zealand; United States; United Kingdom; Japan; Germany |
| Key companies profiled | Contentful, Contentstack, Storyblok, Sanity, Hygraph, Kontent.ai, Adobe, Sitecore, Optimizely, Bloomreach, Magnolia, Crownpeak, Strapi, Directus, Craft CMS, Ghost, DatoCMS, ButterCMS, Agility CMS |
| Forecast period | 2026 to 2036 |
Headless CMS Software Market - Research Methodology
Table 12: Research Methodology for the Headless CMS Software Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Data Sources | Company results, industry associations, government statistics and trade publications. |
| Desk Research | Coverage spans content architecture, cloud adoption, digital commerce, accessibility rules and platform consolidation. |
| Market Sizing | Market value combines software subscriptions and related services across segments and regions. |
| Data Validation | Figures are cross-checked across company, industry and government sources. |
Headless CMS Software Market by Segments
Headless CMS Software Market segmented by Solution:
- Headless CMS Software Tools
- Headless CMS Software Services
Headless CMS Software Market segmented by Enterprise Size:
- Large Enterprises
- SMEs
Headless CMS Software Market segmented by Deployment:
- Cloud-based
- On-premise
Headless CMS Software Market segmented by End Use:
- IT and Telecom
- Retail and E-commerce
- BFSI
- Media and Entertainment
- Healthcare
- Government
- Travel and Hospitality
- Others
Headless CMS Software Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Eurostat. (2026, February 3). 53% EU enterprises used paid cloud services in 2025. https://ec.europa.eu/eurostat/web/products-eurostat-news/w/ddn-20260203-1
- [2] International Telecommunication Union. (2025, November 17). Global number of Internet users increases, but disparities deepen key digital divides. https://www.itu.int/en/mediacentre/Pages/PR-2025-11-17-Facts-and-Figures.aspx
- [3] Salesforce. (2026, June 1). Salesforce Signs Definitive Agreement to Acquire Contentful. https://www.salesforce.com/news/press-releases/2026/01/22/salesforce-signs-definitive-agreement-to-acquire-contentful/
- [4] Vercel. (2025, September 30). Towards the AI Cloud: Our Series F. https://vercel.com/blog/series-f
- [5] Adobe Inc. (2025, December 10). Adobe Reports Record Q4 and FY2025 Revenue. https://www.sec.gov/Archives/edgar/data/796343/000079634325000135/adbeex991q425.htm
- [6] Adobe Inc. (2025, November 19). Adobe to Acquire Semrush. https://news.adobe.com/news/2025/11/adobe-to-acquire-semrush
- [7] Contentstack. (2026, June 9). Contentstack Introduces Its Agentic Experience Platform (AXP) With Agent OS and Agent Accelerator to Remove Roadblocks to Enterprise AI ROI and Adoption. https://www.contentstack.com/company/press/contentstack-introduces-its-agentic-experience-platform-axp-with-agent-os-and-agent-accelerator-to-remove-roadblocks-to-enterprise-ai-roi-and-adoption
- [8] European Disability Forum. (2025, June 27). European Accessibility Act: products and services required to be accessible! https://www.edf-feph.org/?p=27393
- [9] U.S. Census Bureau. (2026, August 18). Quarterly Retail E-Commerce Sales, 2nd Quarter 2026. https://www.census.gov/retail/ecommerce.html
- [10] CMSWire. (2025, May 8). Sanity Raises $85 Million for Alternative to the CMS. https://www.cmswire.com/the-wire/sanity-raises-85-million-for-alternative-to-the-cms/
This bibliography is provided for reader reference. The full report contains the complete reference list and detailed citations.
This Report Answers
- How big is the headless CMS software market during 2026?
- What market size is projected by 2036?
- Which solution holds notable share?
- Which enterprise size holds notable share?
- Which countries have notable growth?
- Which companies are notable in the market?
Frequently Asked Questions
How large is the headless CMS software market expected in 2026?
The market is expected to reach USD 1,193.9 million in 2026 on FMI estimates, up from USD 973.8 million in 2025, as brands move content into cloud repositories that serve many channels.
What CAGR is projected for the headless CMS software market through 2036?
Through 2036, a 22.6% CAGR is projected, with sales of headless CMS software reaching USD 9,159.4 million, since AI agents and new channels raise the need for structured content.
Which solution holds a notable market share in 2026?
Headless CMS software tools are expected to hold 64.2% share in 2026, as every project begins with a repository subscription. Services account for an estimated 35.8%.
Which enterprise size holds a notable market share in 2026?
Large enterprises are expected to hold 56.7%, as companies with many brands need controlled content. SMEs make up about 43.3%.
Which country has a notable expansion outlook through 2036?
India leads the FMI country outlook at a 26.1% CAGR, supported by IT services teams that build composable platforms for global clients. China is next at 24.7%.
Who are the key companies in the headless CMS software market?
Contentful, now part of Salesforce, leads the API-first group with Contentstack, Sanity, Storyblok and Hygraph, and Adobe, Sitecore and Optimizely lead the suite vendors. Strapi and Directus lead the open-source group, competing on self-hosting and flexibility.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Solution, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Solution, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Solution, 2026 to 2036
- Headless CMS Software Tools
- Headless CMS Software Services
- Y-o-Y Growth Trend Analysis By Solution, 2021 to 2025
- Absolute $ Opportunity Analysis By Solution, 2026 to 2036
- Global Market Analysis and Forecast, By Enterprise Size, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Enterprise Size, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Enterprise Size, 2026 to 2036
- Large Enterprises
- SMEs
- Y-o-Y Growth Trend Analysis By Enterprise Size, 2021 to 2025
- Absolute $ Opportunity Analysis By Enterprise Size, 2026 to 2036
- Global Market Analysis and Forecast, By Deployment, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Deployment, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Deployment, 2026 to 2036
- Cloud-based
- On-premise
- Y-o-Y Growth Trend Analysis By Deployment, 2021 to 2025
- Absolute $ Opportunity Analysis By Deployment, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By End Use, 2026 to 2036
- IT and Telecom
- Retail and E-commerce
- BFSI
- Media and Entertainment
- Healthcare
- Government
- Travel and Hospitality
- Others
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- By Country
- Market Attractiveness Analysis
- By Country
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Solution
- By Enterprise Size
- By Deployment
- By End Use
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Contentful
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Contentstack
- Sanity
- Storyblok
- Adobe
- Sitecore
- Strapi
- Hygraph
- Kontent.ai
- Optimizely
- Bloomreach
- Magnolia
- Crownpeak
- Directus
- Craft CMS
- Ghost
- DatoCMS
- ButterCMS
- Agility CMS
- Contentful
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


