

- Market Size (2026)
- USD 51.1 Bn
- Forecast (2036)
- USD 93.9 Bn
- CAGR (2026 to 2036)
- 6.3%
How big is Food Service Equipment Market in 2026?
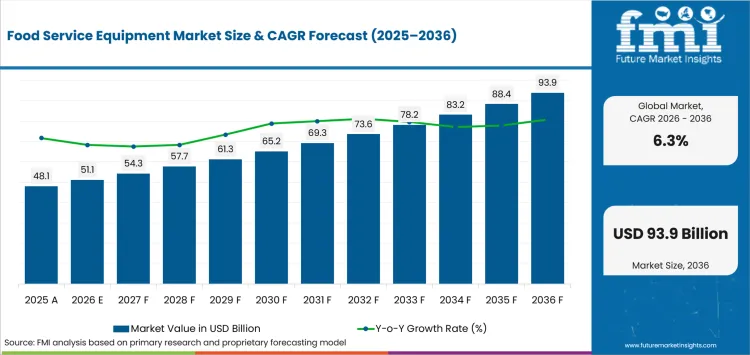
USD 51.1 billion in 2026 and USD 93.9 billion by 2036 at a 6.3% CAGR.
Demand for food service equipment is projected to expand at a 6.3% CAGR between 2026 and 2036, increasing valuation from USD 51.1 billion in 2026 to USD 93.9 billion by 2036. Replacement and upgrade activity remain important demand drivers as restaurant operators seek to improve kitchen productivity and reduce operating costs. The National Restaurant Association reported in July 2025 that 55% of operators planned capital spending on equipment or remodeling during the following six months. The planning rate indicates an active replacement pipeline despite ongoing pressure on restaurant margins. Equipment purchases convert more readily into orders when the proposed upgrade reduces labor requirements or utility consumption without introducing significant installation complexity at the site.
National operating conditions determine how quickly planned equipment spending becomes installed equipment in each major market. USA Census Bureau data released in June 2026 put food services and drinking places sales 2.7% above May 2025, confirming active operator revenue without proving the same capital conditions elsewhere. UK labor costs and weaker German hospitality turnover impose tighter replacement tests than the current USA revenue backdrop.
Key Takeaways of Food Service Equipment Market
- Replacement demand is strongest for equipment upgrades that improve throughput or lower operating expense without increasing installation risk.
- Cooking equipment is projected to hold 25.4% share in 2026 owing to direct control over peak-service meal output.
- By end-use, hotels are forecast to represent 21.1% in 2026 driven by several foodservice formats sharing one property’s equipment base.
- Online is likely to capture 40.8% share in 2026 attributable to operators comparing dimensions and capacity ahead of dealer-supported installation.
- Upfront capital and retrofit work can delay replacement if ventilation or utility changes raise installed cost beyond the approved payback.
- Key players in the food service equipment market include The Middleby Corporation, Ali Group, Illinois Tool Works Inc., HOSHIZAKI CORPORATION, Electrolux Professional Group, RATIONAL AG, Alto-Shaam, Inc., and Hatco Corporation.
Analyst Perspective
"Commercial kitchens should compare replacement equipment against peak-hour output and the utility load removed over the asset life. A higher-priced system earns its place when installation planning and local field service preserve those operating gains after commissioning."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights
How is the Food Service Equipment Market segmented?
The market is segmented by equipment type, end-use, sales channel and region.
Equipment types cover cooking, food preparation, drink preparation, heating and holding, refrigerators and chillers, merchandisers, other foodservice equipment and food blenders. End uses cover hotels, fine and casual dining restaurants, institutional canteens and catering, commercial kitchens, fast food and quick service restaurants, bakery and travel retail for airways, ships and railways. Sales channels cover online, offline, multi-brand, specialty or company and hypermarket or supermarket formats.
Why do Hotels lead the End-use category?

Hotels run multiple foodservice formats within one property, so restaurant equipment planning extends beyond the main dining room into banqueting and room service. Breakfast operations depend on food holding equipment that preserves serving temperature through a service peak ahead of lunch preparation.
- Hotels are set to lead the end-use category with 21.1% share in 2026 due to several foodservice formats sharing one installed equipment base.
- Hotel refurbishment gives equipment manufacturers a replacement route that varies by property age and service mix. Statistics Netherlands documented a 0.4% year-on-year increase in hotel turnover during the first quarter of 2026, keeping refurbishment decisions tied to active accommodation operations.
What makes Cooking equipment central to the Equipment type category?
Hot-line capacity makes commercial cooking equipment a direct throughput decision in restaurants and institutional kitchens. Operators compare commercial ovens on recovery speed and usable footprint during capital approval for replacement. Electrolux Professional Group’s November 2025 Investor Day identified the newly launched e-XP range as part of its effort to strengthen horizontal cooking in Europe.
- By equipment type, cooking equipment is projected to account for 25.4% in 2026 due to hot-line capacity directly limiting peak kitchen output.
- Electrolux Professional Group targeted horizontal cooking for restaurants that need higher output from equipment fitting existing back-of-house space and utility connections.
How does Online lead the Sales channel category?
Online comparison lets operators narrow dimensions, capacity and utility requirements ahead of a dealer or technician site survey that confirms installation work.
- In 2026, online is expected to lead the sales channel category with 40.8% share because operators can compare dimensions and utilities during early specification work with dealer-supported installation handled later. Alto-Shaam expanded its Factory-Authorized Installation Program in March 2026 and placed updated program options in AutoQuotes.
- Operators can shortlist commercial refrigeration systems and narrow technical choices ahead of dealer review. Beverage dispensers still require site-specific utility checks and commissioning support during final installation planning at each site.
What are the drivers, restraints and opportunities in the Food Service Equipment Market?
Productivity gains strengthen replacement economics, installation work delays capital approval and food-tech investment gives manufacturers a defined automation route.
- Driver: Measurable productivity gains make replacement easier to justify after equipment changes the labor or throughput equation.
- Restraint: Capital approval weakens if retrofit work or operating pressure extends payback beyond the operator’s investment threshold.
- Opportunity: Food-robot testing infrastructure gives cooking-equipment manufacturers a defined route for pilots and local validation.
Operator productivity strengthens the replacement case
Restaurants approve equipment more readily once projected labor savings or faster production can be tested against the actual kitchen schedule. The National Restaurant Association said in February 2025 that 28% of operators planned technology investments for efficiency and related operating tasks. A commercial dishwasher or programmable cooking system has a stronger capital case when the proposal quantifies labor hours saved and throughput gained at the site.
Retrofit cost keeps attractive projects from converting
Installation can stop a replacement even after the operator accepts the expected energy or labor savings. The UK Office for National Statistics found in April 2026 that 86% of accommodation and food service businesses faced at least one turnover challenge. Electrical upgrades and kitchen ventilation systems then require a payback case that covers site work and local maintenance without extending closure beyond the planned refit window.
Food-robot infrastructure gives automation a practical entry route
Operators need a place to test automation against real kitchen tasks before committing to a broader rollout. In July 2025, South Korea’s agriculture ministry broke ground on a Pohang food-robot research center that includes a shared test kitchen and is scheduled for completion in 2026. The center gives cooking-equipment manufacturers a route to prove workflow fit alongside commercial refrigeration equipment and other installed kitchen systems ahead of chain deployment.
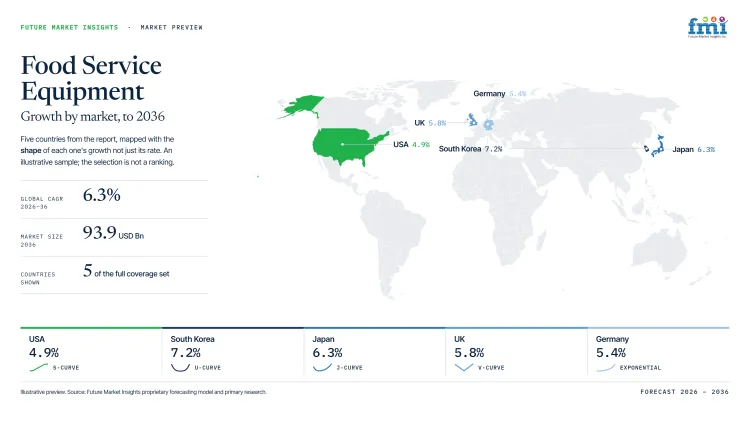
Which country CAGRs are profiled in the Food Service Equipment Market?
| Country | CAGR |
|---|---|
| Mexico | 8.1% |
| Netherlands | 7.7% |
| South Korea | 7.2% |
| Japan | 6.3% |
| UK | 5.8% |
| Germany | 5.4% |
| USA | 4.9% |
How do country-level CAGRs compare in the Food Service Equipment Market?
The country range spans 3.2 percentage points from Mexico at 8.1% to the USA at 4.9%. Mexico and the Netherlands lead because large operating bases combine with active replacement or refurbishment cycles. South Korea through the USA then step down as installation economics and local service coverage tighten capital approval.
- Mexico’s large restaurant base widens replacement volume while fragmented operators raise dealer-service and financing requirements.
- Dutch hospitality growth rewards equipment that cuts energy or labor costs without extending commissioning in compact kitchens.
- MAFRA’s 2026 plan expands food-tech training to ten universities, widening automation-support capacity.
- Japan Tourism Agency data show May guest nights fell 3.2%, tempering hotel volumes.
- ONS put UK hospitality energy-price concern at 86%, strengthening efficient-equipment economics.
- Eurostat shows foreign guests supplied 18.5% of German accommodation nights, keeping demand domestic.
- NRA found 42% of USA operators unprofitable in 2025, keeping payback central.
CAGR guides market timing, but service coverage determines how quickly forecast demand becomes installed equipment. The full report provides country-level CAGR analysis across North America, Latin America, Europe, East Asia, South Asia, Oceania and the Middle East and Africa.
Country-wise Analysis
- Mexico's foodservice equipment outlook reflects a large restaurant base where small operators replace equipment differently from national chains. INEGI's 2024 Economic Census counted 721.6 thousand establishments in food and beverage preparation services in its preliminary national results nationwide. That installed base broadens replacement demand but also fragments purchasing across kitchens with different financing and service requirements at purchase. Mexican food service equipment demand is projected to rise at 8.1% CAGR through 2036 as operators formalize capacity and workflow upgrades. Suppliers convert more orders when dealer networks can install standard equipment without forcing expensive ventilation changes or added utility work on site.
- Netherlands foodservice operators renew equipment within a dense hospitality base where throughput and energy cost are visible at unit level. CBS reported in March 2026 that hospitality turnover rose 3.9% during 2025 while eating and drinking establishments increased 4.8%. That revenue expansion gives operators more room to approve replacements when new equipment lowers utility use or protects peak-service capacity. Food service equipment demand in the Netherlands is projected to grow at 7.7% CAGR through 2036 as refurbishment cycles remain active. Installation still depends on service coverage because compact kitchens cannot absorb long commissioning delays or unplanned utility modifications during operating hours.
- South Korean restaurant groups can test cooking automation through a government-backed food-tech network that links universities with equipment developers and regional operating partners ahead of chain-wide rollout. Food service equipment demand in South Korea is forecast to rise at 7.2% CAGR over the forecast period because standardized quick-service tasks give robotic cooking systems a practical route into repeatable commercial use during peak periods. MAFRA stated in July 2026 that Food Tech Research Support Centres will increase from seven to ten by 2030, but smaller operators still need local integration teams that can install and maintain robotic systems without disrupting meal service at busy sites.
- In dense Japanese cities, commercial kitchens prioritize compact footprints since hotel and restaurant sites cannot absorb long service interruptions during equipment replacement at older properties with service work concentrated into narrow shutdown windows. Japan Tourism Agency data published in July 2026 put national hotel room occupancy at 61.0% in May and confirm a sizable installed base operating under active accommodation demand. Adoption of food service equipment in Japan is estimated to expand at 6.3% CAGR through 2036 aided by high-output systems that conserve kitchen space, though parts availability and technician access can delay replacement at heavily used sites during busy travel periods.
- Refit timing shapes UK replacement decisions since restaurants and hotels cannot easily interrupt trading for electrical or ventilation work during a kitchen refit in older city-center properties with constrained back-of-house access. The UK food service equipment sector is projected to record 5.8% CAGR during the assessment period tied to programmable workflows, with ONS data from May 2026 showing labor costs affected turnover for 50% of accommodation and food service businesses. Compact retrofits and dealer finance can improve order conversion, but each proposal needs a credible local maintenance response and a payback that survives tight operating margins without extending closure time during installation.
- Major kitchen alterations are expensive for many German operators, so restaurants often extend equipment life until an upgrade lowers operating cost or resolves a compliance requirement in independently operated hotels and restaurants. Eurostat published in September 2025 that Germany’s tourism accommodation nights increased 0.2% during the first half of 2025, giving equipment manufacturers a restrained demand backdrop for discretionary upgrades. Germany’s food service equipment outlook is anticipated to advance at 5.4% CAGR over the assessment period given efficient cooking and lower-GWP refrigeration use cases, yet retrofit compatibility can lengthen specification work and keep near-term orders concentrated in compliance or end-of-life replacement.
- A national dealer and service network gives United States multi-unit operators several installation routes over widely dispersed operating territories without rebuilding local channels state by state in regional markets. USA is estimated to post 4.9% CAGR over the forecast period helped by mainstream technology adoption among restaurant operators and a mature installed base that keeps replacement demand commercially relevant. National Restaurant Association data released in February 2026 found that 60% of operators considered their restaurants part of the technology mainstream, so manufacturers with national service coverage can convert practical upgrades even though technician availability and site work can lengthen shutdown windows.
Who are the notable companies in the Food Service Equipment Market?
The Middleby Corporation, Ali Group, Illinois Tool Works Inc., HOSHIZAKI CORPORATION, Electrolux Professional Group, RATIONAL AG, Alto-Shaam, Inc., and Hatco Corporation are the notable companies serving this market.

The competitive field includes diversified equipment groups and specialists concentrated in cooking or holding functions. Installation planning and trained service raise entry barriers because commercial kitchens cannot tolerate long equipment outages. HOSHIZAKI CORPORATION also supplies commercial ice equipment for beverage-led sites. Broad portfolios carry more weight if one service network can support several kitchen functions without extending downtime.
- The Middleby Corporation, Ali Group, Illinois Tool Works Inc., HOSHIZAKI CORPORATION and Electrolux Professional Group cover multiple equipment categories through networks.
- RATIONAL AG and Alto-Shaam, Inc. concentrate more heavily on cooking systems that depend on workflow control and field support during replacement decisions.
- Hatco Corporation spans warming, holding, cooking and merchandising equipment through a smaller corporate platform than the diversified global groups.
Competitive Benchmarking: Food Service Equipment Market
| Company | Equipment Category Breadth | Installed-Service Coverage | Kitchen-System Integration | Geographic Reach |
|---|---|---|---|---|
| The Middleby Corporation | High | High | High | Global |
| Ali Group | High | High | High | Global |
| Illinois Tool Works Inc. | High | High | High | Global |
| HOSHIZAKI CORPORATION | High | High | Medium | Global |
| Electrolux Professional Group | High | High | High | More than 110 countries |
| RATIONAL AG | Low | High | Medium | Global |
| Alto-Shaam, Inc. | Medium | Medium | Medium | International |
| Hatco Corporation | High | Medium | Medium | International |
Scoring basis: High equipment-category breadth requires four or more verified categories, Medium requires two or three and Low identifies one specialist route. High installed-service coverage requires documented support in at least three major regions, Medium covers one or two regions and Low identifies limited direct coverage. High kitchen-system integration requires coordinated equipment categories plus installation or service evidence, while Medium covers complementary categories without broader system evidence and Low identifies a standalone specialist route.
Key Developments in the Food Service Equipment Market
- In October 2025, RATIONAL AG expanded RATIONAL USA’s partnership with PMR Foodservice Equipment Reps to include MAFSI Region 12, strengthening representative coverage across Alabama, Georgia, the Florida Panhandle, and Tennessee.
- In January 2025, Ali Group completed its acquisition of Czech commercial-cooking equipment manufacturer JIPA for its global foodservice portfolio.
- In January 2025, HOSHIZAKI CORPORATION acquired Cannon Marketing’s foodservice equipment distribution business to strengthen sales and maintenance coverage in the southeastern United States.
Key Players in the Food Service Equipment Market
Diversified global foodservice equipment groups
- The Middleby Corporation
- Ali Group
- Illinois Tool Works Inc.
- HOSHIZAKI CORPORATION
- Electrolux Professional Group
Cooking and workflow specialists
- RATIONAL AG
- Alto-Shaam, Inc.
Holding and multi-category equipment specialist
- Hatco Corporation
Food Service Equipment Market - Report Scope
| Coverage field | Report scope |
|---|---|
| Market breakdown | By equipment type, end-use, sales channel and region. |
| Quantitative Units | USD Billion. |
| Market Definition | Commercial equipment used to prepare, cook, hold, refrigerate, merchandise, dispense or otherwise support food and beverage service in professional operating environments. |
| Regions Covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa. |
| Countries Covered | Mexico, Netherlands, South Korea, Japan, UK, Germany, and USA, and 20+ countries included in the full report. |
| Key Companies Profiled | The Middleby Corporation, Ali Group, Illinois Tool Works Inc., HOSHIZAKI CORPORATION, Electrolux Professional Group, RATIONAL AG, Alto-Shaam, Inc., Hatco Corporation. |
| Forecast Period | 2026 to 2036. |
| Approach | Primary and secondary research with market triangulation. |
Food Service Equipment Market - Research Methodology
| Method | Approach |
|---|---|
| Primary Research | FMI analysts gathered input from manufacturers, service providers, technology developers, distributors, end users, procurement teams, and subject-matter experts. Interviews examined purchasing decisions, product or service evaluation, adoption barriers, approval requirements, pricing considerations, and expectations for technical or commercial support. Respondents were also asked what evidence is required before a trial, pilot, or initial order develops into regular purchasing. |
| Desk Research | Desk research covered government statistics, regulatory publications, trade data, industry associations, technical literature, standards, company filings, product information, and official corporate announcements. Sources were reviewed for relevance, publication date, geographic coverage, and consistency with the defined market scope. Claims relating to performance, applications, approvals, capacity, investment, and commercial activity were retained only when supported by credible public evidence. |
| Market Sizing and Forecasting | The market model combined the baseline value with historical performance, segment structure, pricing and volume indicators, adoption levels, company participation, and country-level demand conditions. Forecast assumptions considered economic activity, investment trends, regulatory developments, technology adoption, purchasing cycles, supply availability, and barriers to wider market use. Segment and regional estimates were reconciled before the final market total was calculated. |
| Data Validation | Estimates were checked against multiple independent indicators, including public data, company activity, trade patterns, industry developments, and findings from primary interviews. Validation also tested whether products, services, applications, and company revenues fell within the defined market boundaries. Adjacent categories, unsupported claims, overlapping revenues, and activities without direct market relevance were excluded to reduce double counting and maintain consistency across segments and countries. |
Food Service Equipment Market by Segments
Food Service Equipment Market segmented by Equipment Type:
- Cooking Equipment
- Food Preparation Equipment
- Drink Preparation Equipment
- Heating And Holding Equipment
- Refrigerators And Chillers
- Merchandisers
- Other Food and Beverage Service Equipment
- Food Blenders
Food Service Equipment Market Segmented By End-Use:
- Hotels
- Fine Dining Restaurants
- Casual Dining Restaurants
- Institutional Canteens and Catering
- Commercial Kitchens
- Fast Food and Quick Service Restaurants
- Bakery
- Travel Retail Services (Airways, Ships and Railways)
Food Service Equipment Market Segmented by Sales Channel:
- Online
- Offline
- Multi-Brand Outlets
- Specialty Or Company Outlets
- Hypermarket Or Supermarket
Food Service Equipment Market by Region:
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Chile
- Rest of Latin America
- Western Europe
- Germany
- United Kingdom
- Italy
- Spain
- France
- Nordics
- Benelux
- Rest of Western Europe
- Eastern Europe
- Russia
- Poland
- Hungary
- Balkan and Baltic States
- Rest of Eastern Europe
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Rest of South Asia and Pacific
- Middle East and Africa
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union Countries
- Rest of Middle East and Africa
Research Sources and Bibliography
- National Restaurant Association. (2025, July). Restaurant Performance Index: July 2025.
- USA Census Bureau. (2026, June 17). Advance monthly sales for retail and food services, May 2026.
- Electrolux Professional Group. (2025, November 6). Electrolux Professional Group Investor Day 2025.
- Statistics Netherlands. (2026, June 1). Turnover in accommodation and food services sector up by 2.2 percent in Q1.
- Alto-Shaam, Inc. (2026, March 16). Alto-Shaam expands factory install program.
- National Restaurant Association. (2025, February 6). The 2025 State of the Industry shows cautious optimism.
- Office for National Statistics. (2026, April 23). Business insights and impact on the UK economy: 23 April 2026.
- Ministry of Agriculture, Food and Rural Affairs, Republic of Korea. (2026, July 20). S. Korea Unveils Master Plan to Integrate Advanced Technologies into the Food Sector.
- Japan Tourism Agency. (2026, July 31).
- Office for National Statistics. (2026, May 21). Business insights and impact on the UK economy: 21 May 2026.
- Eurostat. (2025, September 25). EU tourism nights up by 2.3% in first half of 2025.
- National Restaurant Association. (2026, February 11). State of the restaurant industry 2026.
- RATIONAL AG. (2025, October 16). RATIONAL USA expands partnership with PMR to include MAFSI Region 12.
- Ali Group. (2025, January 22). Ali Group expands global reach with acquisition of JIPA.
- HOSHIZAKI CORPORATION. (2025, January 6). Hoshizaki acquires business from USA distributor.
- USA Securities and Exchange Commission. (2026, March 4). The Middleby Corporation Form 10-K.
- USA Securities and Exchange Commission. (2026, February 13). Illinois Tool Works Inc. Form 10-K.
- HOSHIZAKI CORPORATION. (2025, June 13). Hoshizaki to acquire major USA food display case manufacturer.
- Electrolux Professional Group. (2026, January 9). Electrolux Professional Group has completed the acquisition of the assets of Royal Range.
- Ali Group. (2026, March 12). Ali Group announced it has completed the acquisition of BUNN.
- RATIONAL AG. (2025, June 11). RATIONAL USA expands partnership with Alliance Foodservice Equipment for MAFSI Region 7.
- Alto-Shaam, Inc. (2025, September 9). Alto-Shaam provides carbon data for customers through ImpactLoop partnership.
- Hatco Corporation. (2026, May 12). Hatco launches Flav-R-Savor heated display merchandiser for boosting grab-and-go sales.
- Illinois Tool Works Inc. (2026). Food Equipment. Retrieved August 28, 2026.
- MKN Maschinenfabrik Kurt Neubauer GmbH & Co. KG. (2026). Company. Retrieved August 28, 2026.
- Ali Group. (2026). Ali Worldwide. Retrieved August 28, 2026.
- HOSHIZAKI CORPORATION. (2026). Global Network. Retrieved August 28, 2026.
- Electrolux Professional Group. (2026). Sales & Customers. Retrieved August 28, 2026.
- RATIONAL AG. (2026). Company. Retrieved August 28, 2026.
- Alto-Shaam, Inc. (2026). About Us. Retrieved August 28, 2026.
- Alto-Shaam, Inc. (2026). Technical Service. Retrieved August 28, 2026.
- Hatco Corporation. (2025). Hatco Corporation unveils new logos in celebration of 75th anniversary. Retrieved August 28, 2026.
- Hatco Corporation. (2026). Support. Retrieved August 28, 2026.
- NSF. (2026, August 27). NSF Product and Service Listings: HOSHIZAKI.
- NSF. (2026, August 27). NSF Product and Service Listings: Hobart.
- NSF. (2026, August 24). NSF Product and Service Listings: Electrolux Professional.
- NSF. (2026, August 24). NSF Product and Service Listings: Hatco Corporation.
- Instituto Nacional de Estadística y Geografía. (2025). Censos Económicos 2024: Resumen de resultados oportunos.
- Statistics Netherlands. (2026, March 2). Omzet horeca groeit in vierde kwartaal met ruim 3 procent.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations
This Report Answers
- What are the global Food Service Equipment market values in 2026 and 2036?
- What factors are supporting equipment replacement and upgrade spending across food service establishments?
- Why does cooking equipment hold the largest share of the market in 2026?
- Why do hotels account for the leading share of end-use demand for food service equipment?
- How does online purchasing influence equipment selection, installation, and after-sales support requirements?
- How do market growth rates and opportunities compare across the countries profiled in the report?
- Which companies offer the broadest food service equipment portfolios across cooking, refrigeration, warewashing, and food preparation categories?
- Which operational, financial, and supply chain frictions can delay food service equipment replacement decisions?
- How have recent product launches, acquisitions, partnerships, and distribution expansions affected portfolio breadth and sales coverage in the market?
Frequently Asked Questions
How big is the food service equipment market in 2026?
The food service equipment market is valued at USD 51.1 billion in 2026 and is projected to reach USD 93.9 billion by 2036. Replacement demand depends on equipment that improves kitchen throughput while reducing labor or utility cost over the asset life.
What is the CAGR of the food service equipment market from 2026 to 2036?
The food service equipment market is projected to grow at a CAGR of 6.3% between 2026 and 2036. Replacement cycles and productivity investment support efficient refrigeration and automated cooking equipment that can lower operating expense.
Which equipment type leads the food service equipment market?
The cooking equipment segment is expected to hold 25.4% of the food service equipment market in 2026, driven by hot-line capacity. Recovery speed and usable equipment footprint determine how much meal output a kitchen can sustain during peak service.
Which countries are projected to record the highest growth in the food service equipment market?
Mexico is projected to grow at 8.1% CAGR followed by the Netherlands at 7.7% and South Korea at 7.2% through 2036. Replacement depth and service coverage differ across these markets as operators convert refurbishment budgets into installed equipment.
Which companies are active in the food service equipment market?
Key companies operating in the market include The Middleby Corporation, Ali Group, Illinois Tool Works Inc., HOSHIZAKI CORPORATION, Electrolux Professional Group, RATIONAL AG, Alto-Shaam, Inc., and Hatco Corporation. Their differentiation comes from equipment breadth and field-service coverage that can support several kitchen functions after installation.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Equipment Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Equipment Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Equipment Type, 2026 to 2036
- Cooking Equipment
- Food Preparation Equipment
- Drink Preparation Equipment
- Heating & Holding Equipment
- Refrigerators & Chillers
- Merchandisers
- Other F&B Service Equipment
- Food Blenders
- Cooking Equipment
- Y-o-Y Growth Trend Analysis By Equipment Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Equipment Type, 2026 to 2036
- Global Market Analysis and Forecast, By End-Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End-Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End-Use, 2026 to 2036
- Hotels
- Fine Dine Restaurants
- Casual Dining Restaurants
- Institutional Canteens & Catering
- Commercial Kitchens
- Fast Food & Quick Service Restaurants
- Bakery
- Travel Retail Services (Airways, Ships, Railways)
- Hotels
- Y-o-Y Growth Trend Analysis By End-Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End-Use, 2026 to 2036
- Global Market Analysis and Forecast, By Sales Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sales Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sales Channel, 2026 to 2036
- Online
- Offline
- Multi-Brand Outlets
- Specialty / Company Outlets
- Hypermarket / Supermarket
- Online
- Y-o-Y Growth Trend Analysis By Sales Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Sales Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Equipment Type
- By End-Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Equipment Type
- By End-Use
- By Sales Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Equipment Type
- By End-Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Equipment Type
- By End-Use
- By Sales Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Equipment Type
- By End-Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Equipment Type
- By End-Use
- By Sales Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Equipment Type
- By End-Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Equipment Type
- By End-Use
- By Sales Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Equipment Type
- By End-Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Equipment Type
- By End-Use
- By Sales Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Equipment Type
- By End-Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Equipment Type
- By End-Use
- By Sales Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Equipment Type
- By End-Use
- By Sales Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Equipment Type
- By End-Use
- By Sales Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Equipment Type
- By End-Use
- By Sales Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Equipment Type
- By End-Use
- By Sales Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Angel Yeast Co., Ltd.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Chr. Hansen Holding A/S
- Lesaffre
- Glanbia plc
- Olam International Limited
- AAK AB
- Tate & Lyle PLC
- Symrise AG
- Angel Yeast Co., Ltd.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


