
- Market Size (2026)
- USD 540.0 Bn
- Forecast (2036)
- USD 863.0 Bn
- CAGR (2026 to 2036)
- 4.8%
How big is the Dairy Products Market in 2026?
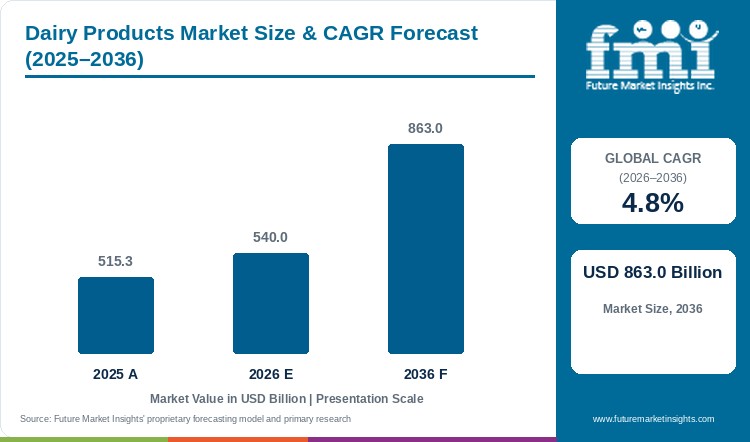
Demand for milk and cheese is expected to carry the Dairy Products Market to USD 863.0 billion by 2036. FMI values the 2026 market at USD 540.0 billion and forecasts a 4.8% CAGR for 2026 to 2036. The market was valued at USD 515.3 billion in 2025. Convenience Stores hold 66.6% by distribution channel in 2026. Milk accounts for 42.3% by product type, and Cow Milk represents 81.0% by source in FMI's 2026 assessment.
Rising milk supply in the main producing regions feeds the outlook. The US Department of Agriculture forecasts 2026 US milk output at 236.9 billion pounds, rising to 238.4 billion pounds in 2027. The European Commission expects EU milk supply to rise 1.8% in 2026. China's National Bureau of Statistics reported milk output of 40.9 million tons in 2025, up 0.3%. Processors are turning that extra milk into cheese, powders and protein-rich yogurt.
Low farmgate prices restrain supply. The FAO Dairy Price Index stood 19.1% below its year-earlier level in September 2026. The European Commission recorded an EU raw milk price of EUR 42.0 per 100 kg in July 2026, down 20.4% in a year. Farmers facing those prices cut herds. Fonterra provides a qualified example of portfolio change. It completed the sale of its Mainland Group consumer business to Lactalis on 31 March 2026. One transaction shifts brand ownership and does not prove a wider wave of dairy consolidation.
Key Market Trends & Insights
- Protein-rich dairy lines are outgrowing the wider category. Arla reported first-half 2026 growth of 39.6% for Arla Skyr and 34.4% for Arla Protein. Danone said its high-protein yogurt grew at a double-digit rate in every region and is adding yogurt production lines through 2026. Processors move milk solids into these lines because they earn more per litre than plain milk.
- US processing capacity is being rebuilt. The International Dairy Foods Association counted more than 85 projects worth over USD 15.0 billion planned or under way through 2030 across 23 states. Milk and cream plants account for USD 5.6 billion of that total, cheese USD 3.8 billion and yogurt and cultured dairy USD 3.1 billion. New plants need milk commitments, which keeps dairy herds growing even when prices are weak.
- Powder and cheese prices are moving in opposite directions. Skim milk powder quotations stood 33.1% above their year-earlier level in September 2026, while cheese and butter prices were substantially lower. EU exports of skim milk powder rose 11.0% and butter exports rose 36.0% in January to May 2026. Exporters switch milk between products as each price moves, so product mix changes faster than total volume.
Regional Highlights
- In Europe, surplus milk is pushing cooperatives to combine. EU milk collection rose 3.4% in January to June 2026. Butter output rose 9.2% and skim milk powder rose 11.1% over the same months. Arla Foods and DMK merged on 1 June 2026 to form a cooperative with about 11,200 farmer owners and a milk pool of roughly 20.0 billion kg. Scale lets processors run surplus milk through lower-cost plants.
- In Asia Pacific, exporters supply demand that North Asian herds cannot meet. New Zealand expected a 5.0% rise in dairy export revenue to NZD 28.6 billion in the year to June 2026. Mengniu's fresh milk business grew more than 30.0% over January to June 2026. J-Milk expects Japanese raw milk output to fall 0.9% in fiscal 2026. Importers in the region buy powders, butter and cheese to fill the difference.
Dairy Products Market Size and Forecast
Table 1: Dairy Products Market Size and Forecast
| Market size and forecast | Value |
|---|---|
| Market size in 2025 | USD 515.3 billion |
| Estimated market size in 2026 | USD 540.0 billion |
| Projected market size by 2036 | USD 863.0 billion |
| CAGR from 2026 to 2036 | 4.8% |
Source: Future Market Insights analysis of the dairy products market, 2026.
Analyst Perspective
“Shoppers buy milk and yogurt several times a week and judge them on price per litre, freshness date and the store closest to home. Processors win listings by securing a steady milk supply and by moving that milk into protein, cheese and powder lines that earn more than plain fluid milk. The qualification risk is concentrated on the farm because a processor whose suppliers cut herds after a price fall cannot keep its chilled shelves full when retail demand returns.”
- Nandini Roy Choudhury, Principal Consultant, FMI
How is the Dairy Products Market segmented?
- By product type: Milk, Cheese, Yogurt, Butter, Cream, Milk Powder, Ice Cream, and Others.
- By distribution channel: Convenience Stores, Supermarkets and Hypermarkets, Specialty Stores, Online Retail, Food Service, and Others.
- By source: Cow Milk, Buffalo Milk, Goat Milk, Sheep Milk, and Camel and Other Milk.
- By product form: Slices, Shreds and Blocks, Drinkable Liquids and Shakes, Set Tubs and Cups, and Spreads and Dips.
- By flavour: Plain and Unsweetened, Fruit-Flavoured and Indulgent, and Savoury and Herbed.
- By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why do Convenience Stores lead by Distribution Channel in the Dairy Products Market in 2026?
Convenience Stores hold 66.6% of the Dairy Products Market by distribution channel in 2026.
Milk, yogurt drinks and cheese snacks are bought often and in small quantities. A store close to home or work with long opening hours captures those top-up trips. The United States alone had 151,975 convenience stores at the start of 2026. Their in-store sales reached USD 341.2 billion in 2025, up 1.7%. Packaged beverages made up 18.7% of those in-store sales and ranked second only to prepared food. Chilled milk drinks and single-serve yogurts belong to that beverage and snack basket.
The channel sets strict delivery terms. Each store holds little back-room stock, so processors must deliver chilled product in small drops several times a week. Suppliers with their own cold-chain fleets or strong wholesaler links win the listings. Mengniu reported growth of more than 30.0% in its fresh milk business for the six months to June 2026. Short-dated fresh milk depends on exactly this kind of frequent, local replenishment.
The other channels together account for the remaining 33.4%. These are Supermarkets and Hypermarkets, Specialty Stores, Online Retail, Food Service and Others. Large-format grocers still carry the bulk of family packs in some markets. Dairy Australia reports that about 62.0% of domestic dairy spread sales went through supermarkets. Supermarket milk sales there reached about AUD 3.0 billion in the year to July 2025. FMI carries the convenience store share as given in its channel assessment.
Table 2: Distribution Channel, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Convenience Stores | 66.6% |
| All Other Segments Combined Share | 33.4% |
Source: Future Market Insights analysis of the dairy products market, 2026.
Why does Milk lead by Product Type in the Dairy Products Market in 2026?
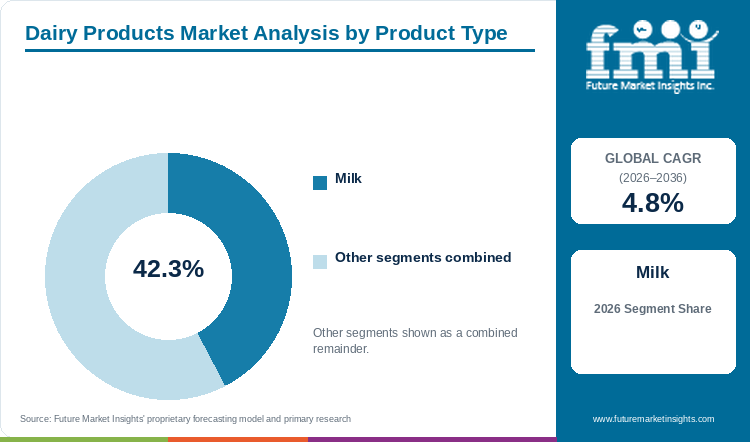
Milk accounts for 42.3% of the Dairy Products Market by product type in 2026.
Fluid milk accounts for a large part of raw milk use in the profiled markets. J-Milk expects 3,790 thousand tonnes of Japan's 7,331 thousand tonnes of raw milk in fiscal 2026 to go to drinking-milk processing. In Australia, drinking milk used 32.0% of milk produced in 2024-25 and cheese 40.0%. Milk is bought daily by households and cafes, so its sales move with population and price more than with fashion.
Price is set close to the farm. The US all-milk price is forecast at USD 19.9 per hundredweight for 2026 and USD 20.5 for 2027. When farmgate prices fall, retail milk prices follow with a lag and volumes rarely rise much. Processors therefore add value through fortified and high-protein milk. FMI tracks that segment in the fortified dairy products market.
The other product types together hold the remaining 57.7%. They are Cheese, Yogurt, Butter, Cream, Milk Powder, Ice Cream and Others. Cheese is the strongest of these lines in trade. Italian cheese exports reached EUR 6,085.8 million in 2025, up 12.8% in value. US processors plan USD 3.8 billion of new cheese capacity through 2030. Yogurt and powders grow with protein demand and export orders.
Table 3: Product Type, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Milk | 42.3% |
| All Other Segments Combined Share | 57.7% |
Source: Future Market Insights analysis of the dairy products market, 2026.
Why does Cow Milk lead by Source in the Dairy Products Market in 2026?
Cow Milk represents 81.0% of the Dairy Products Market by source in FMI's 2026 assessment.
The share follows the animals that supply the world's milk. FAO reports that cattle produce 81.0% of world milk and buffaloes 15.0%. Goats supply 2.0%, sheep 1.0% and camels 0.4%. The large exporting regions are built on cow herds. The United States had 9.7 million milk cows in August 2026. Germany counted 3.6 million dairy cows in November 2025. Processing plants and pricing formulas in these regions are all built around cow milk.
Cow milk also suits industrial processing. Its composition is predictable across large herds, which allows standardised cheese and powder lines. US exports on a skim-solids basis are forecast at 49.1 billion pounds in 2026. Almost all of that volume comes from cow milk.
The other sources together account for the remaining 19.0%. They are Buffalo Milk, Goat Milk, Sheep Milk and Camel and Other Milk. Buffalo milk is concentrated in South Asia and feeds mainly local fresh markets. Goat and sheep milk support regional cheeses in Southern Europe. Plant-based substitutes fall outside this classification and are covered in the dairy alternatives market.
Table 4: Source, 2026 Share
| Leading Share | 2026 market share |
|---|---|
| Cow Milk | 81.0% |
| All Other Segments Combined Share | 19.0% |
Source: Future Market Insights analysis of the dairy products market, 2026.
What are the key drivers restraints and opportunities?
Dairy product sales depend on how much milk farmers deliver and on what processors make from it. The same low prices that lift consumer demand squeeze the farms that supply the raw milk.
Driver
Milk supply is growing in the United States, the EU and New Zealand at the same time. US milk production rose 3.1% in the first quarter of 2026 and 2.6% in the second quarter. The EU expects a 1.8% rise in milk supply for 2026. Fonterra expects to collect slightly more than 1.6 billion kgMS in its 2026/27 season. More milk at lower cost lets processors fill new cheese and powder plants and keep retail prices competitive. Protein demand gives that milk a destination. Arla raised its 2026 guidance for strategic branded volume-driven revenue growth to 4.0% to 6.0% after Skyr and protein lines grew strongly.
Restraint
Farm economics and animal disease limit how long supply growth can last. FrieslandCampina paid its members a guaranteed price of EUR 40.5 per 100 kg for January to June 2026, against EUR 55.6 a year earlier. The GB milking herd shrank to a record low of 1.6 million head in July 2026. In the United States, APHIS reported two newly infected dairy herds in Washington in October 2026 and said cattle in 19 states have been infected since March 2024. Infected herds lose output and face movement limits, which raises the cost of supplying chilled products on time.
Opportunity
Product and channel expansion offers the clearest path to higher value per litre. Danone is adding yogurt production lines through 2026 to serve high-protein demand. Mengniu's cheese business grew more than 30.0% in first-half 2026. US processors have USD 3.1 billion of yogurt and cultured dairy projects planned or under way through 2030. Fortified lines add vitamins and minerals to standard milk and yogurt, and the ingredients behind them are covered in the food fortification market. Each new line must earn its shelf space, so processors should test demand in one channel before a wide launch.
How do milk pricing rules and disease controls affect dairy product costs?
Regulated and cooperative milk prices set the cost base for processors. In the United States, the Class III price for cheese milk is forecast at USD 15.8 per hundredweight for 2026. The Class IV price for butter and powder milk is forecast at USD 18.9. That difference changes which plants pay more for the same milk. Fonterra set its 2026/27 forecast Farmgate Milk Price at NZD 9.3 per kgMS in July 2026 and cited softer demand at a time of strong global supply. Its final price for 2025/26 was NZD 9.7 per kgMS.
Disease controls add testing and movement rules. APHIS announced HPAI detections in two Washington dairy herds in October 2026 after the herds had tested negative under routine National Milk Testing Strategy surveillance. Processors in affected states must plan for short interruptions to local supply. Buyers should check which plants draw milk from regions with active detections.
What limits reliable dairy supply and product quality?
Herd size and weather set the supply limit in mature markets. AHDB expects the 2026/27 GB milk year to deliver 12,737 million litres, 2.2% less than the year before. Five heatwaves between May and August 2026 cut yields and forage. South Korea's dairy cow count fell 3.0% to 362,000 head in the third quarter of 2026. J-Milk expects Japanese raw milk output of 7,331 thousand tonnes in fiscal 2026, down 0.9%. Fewer cows mean processors in these markets import more powders and cheese to hold product ranges.
Quality depends on the cold chain. Fresh milk and yogurt must stay chilled from plant to shelf, which limits how far they travel. Ambient products extend reach into regions with weak chilled distribution, and FMI covers that segment in the UHT dairy products market. Processors that cannot guarantee temperature control lose listings with convenience chains that deliver several times a week.
Where can processors win additional business?
Processors win business by matching milk to the product with the best return at that moment. In September 2026, skim milk powder quotations were 33.1% above a year earlier while cheese prices fell. EU butter exports rose 36.0% in January to May 2026 as plants used surplus milk for fat. Branded protein lines offer a steadier return. Arla's strategic branded volume-driven revenue grew 6.7% in the first half of 2026, against a 1.5% decline a year earlier. Export channels add a third route. New Zealand dairy export revenue was forecast to reach NZD 28.6 billion for the year to June 2026, a record. Each route needs a different plant set-up, so processors should decide early which mix of commodity and branded output their milk pool can support.
Dairy Products Market by Country (2026 to 2036)
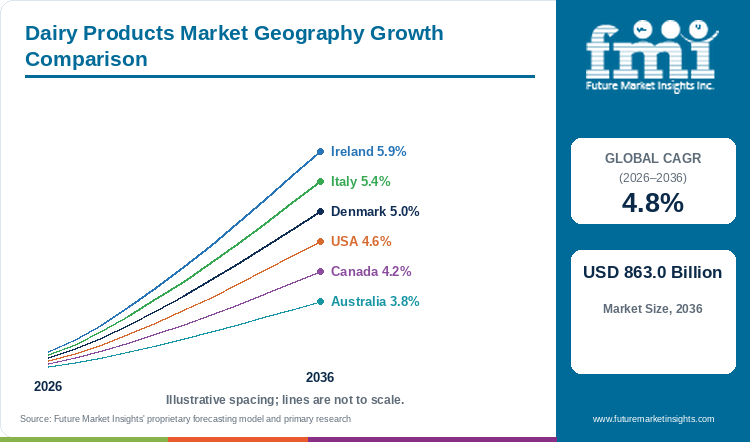
Table 5: Dairy Products Market Country Growth Forecast
| Country | CAGR, 2026 to 2036 |
|---|---|
| China | 6.4% |
| South Korea | 5.2% |
| United States | 4.8% |
| New Zealand | 4.5% |
| Australia | 4.0% |
| United Kingdom | 3.6% |
| Germany | 3.5% |
| France | 3.2% |
| Italy | 3.1% |
| Japan | 2.9% |
Source: Future Market Insights analysis of the dairy products market, 2026.
China
Chinese dairy demand is recovering on fresh milk and cheese. Mengniu's first-half 2026 revenue rose 7.8% to CNY 44.8 billion. Its fresh milk business and its cheese business each grew more than 30.0%. The company pointed to a rebalancing of milk supply and demand and more stable milk prices as the background to that growth. Raw milk output reached 40.9 million tons in 2025, up only 0.3%. The recovery is therefore coming from product mix and price instead of more milk.
Consumer spending supports the shift towards chilled and value-added lines. Retail sales of consumer goods rose 3.7% in 2025 to CNY 50,120.2 billion. Per capita consumption spending grew 4.4% in nominal terms. Households in large cities are adding short-dated fresh milk and protein yogurt to a basket long dominated by ambient milk. Chilled lines need the convenience and fresh-format stores that have spread across those cities.
A 6.4% CAGR for China over 2026 to 2036 is the fastest in the profiled group, and it rests on this move from basic ambient milk to higher-value products. Processors that run their own farms can control raw milk cost and quality during that shift. Mengniu reported profit attributable to owners of CNY 2.4 billion for the first half of 2026, up 15.9%. Slow growth in raw milk output remains the main constraint. If herd investment lags, importers will supply more of the powder and cheese that Chinese plants need. Foreign suppliers with cold-chain partners in coastal cities will serve most of that chilled import demand.
South Korea
South Korea's dairy herd is shrinking while demand for cheese grows. The national dairy cow count fell by 11,000 head to 362,000 in the third quarter of 2026, a decline of 3.0%. USDA's Seoul office forecast domestic milk production of 1.9 million tons for 2025 and cheese imports of 150,000 tons. It linked falling milk consumption to demographic change. The result is a market where processed products grow and fluid milk contracts.
That structure favours importers and domestic processors with flexible plants. Korean consumers increasingly view dairy as a protein source, and cheese imports keep rising on that demand. Domestic dairies that depend on white milk face falling volumes each year. They must move into processed lines to hold revenue.
Convenience and online channels carry much of that change. South Korea's 5.2% CAGR for 2026 to 2036 rests on that reach and is the second-fastest rate in the profiled group. Single-serve yogurt drinks and cheese snacks suit a market of small households and long working hours. Supply is the weak point. A herd falling 3.0% in a year means domestic processors must import more raw material or pay more for local milk. Suppliers from Oceania, the United States and the EU will compete for that import demand on price and shelf life. Domestic firms that build cheese and cream lines on imported ingredients can grow without adding cows. Those tied to white milk will keep losing volume.
United States
US dairy growth is being built on new plants more than on new demand for plain milk. The International Dairy Foods Association counted more than 85 processing projects worth over USD 15.0 billion planned or under way through 2030. New York leads with USD 2.8 billion and Texas follows with USD 1.7 billion. Those plants need milk, and the herd has responded. Milk cows numbered 9.7 million head in August 2026, which was 167,000 more than a year earlier. August output rose 1.7% to 19.9 billion pounds.
Prices are weaker than volumes. The all-milk price is forecast at USD 19.9 per hundredweight for 2026 and the Class III cheese milk price at USD 15.8. Cheddar is forecast at USD 1.5 per pound for 2026. Low prices support cheese and powder exports, which are forecast at 49.1 billion pounds on a skim-solids basis in 2026.
Disease risk accompanies that expansion. APHIS confirmed avian influenza in two Washington dairy herds on 8 October 2026. It reported that cattle in 19 states have been infected since March 2024. Plant expansion and export demand give the United States a 4.8% CAGR over 2026 to 2036, in line with the global rate. Convenience retail adds domestic pull. In-store sales at US convenience stores reached USD 341.2 billion in 2025. Processors that can serve both export powder orders and chilled single-serve lines will capture the widest share of that growth. New capacity could outrun demand and push cheese prices lower for longer.
New Zealand
New Zealand dairy is an export business, so its growth tracks world prices more than home demand. Dairy export revenue was expected to rise 5.0% to a record NZD 28.6 billion in the year to 30 June 2026. That year carried a farmgate payout of NZD 9.9 per kilogram of milksolids. Fonterra paid a final 2025/26 Farmgate Milk Price of NZD 9.7 per kgMS and reported revenue of NZD 27.0 billion for its financial year.
The business has changed shape. Fonterra closed the Mainland Group transaction with Lactalis on 31 March 2026, handing over its consumer and associated businesses. It set a capital return of NZD 2.0 per share for farmer shareholders. The cooperative now concentrates on ingredients and foodservice. Lactalis owns the consumer brands that were built on New Zealand milk. Two owners now compete for the same export customers with different product sets.
Export prices more than volume will decide whether New Zealand achieves its 4.5% CAGR between 2026 and 2036. In July 2026 Fonterra cut its 2026/27 forecast milk price to NZD 9.3 per kgMS within a range of NZD 8.0 to NZD 10.5. It cited softer demand at a time of strong global supply. The Ministry for Primary Industries expects export revenue to ease 3.0% in 2026-27 as production declines from record levels. Collections of just above 1.6 billion kgMS leave little room for volume growth. Value growth must come from higher-margin ingredients and foodservice lines sold into Asia. Buyers in that region will compare New Zealand powders and butter against rising US and EU export supplies.
Australia
Australian dairy is producing more value from less milk. National milk production dipped 0.7% to 8,315 million litres in 2024-25. The number of farms fell 3.0% to 3,772. Cheese accounted for 40.0% of that milk and drinking milk for 32.0%. Exports absorbed 36.0% of production and earned AUD 3.8 billion, a 5.0% rise. Processors have moved manufacturing milk into cheese because it earns more than powder at current prices.
Domestic retail is concentrated in supermarkets. Supermarket milk sales were about AUD 3.0 billion in the 52 weeks to July 2025. About 62.0% of dairy spread sales went through supermarkets. Private-label milk contracts between processors and supermarket chains shape the price of much of the fluid market. Brands earn their margin in cheese, yogurt and specialty milk instead of standard two-litre packs.
Cheese exports and premium retail lines support a 4.0% CAGR for Australia over 2026 to 2036, a middle position in the profiled group. The supply base is the limit. A national herd of 1.3 million cows across farms averaging 345 cows cannot grow quickly. Each dry season removes more small farms. Export value rose 5.0% in 2024-25 while milk volume fell, which shows how much of the growth now comes from product mix. Processors that secure long-term milk contracts and specialise in cheese will hold their margins. Those relying on commodity powder will face competition from larger New Zealand and US volumes. Retail brands will need price increases to grow because supermarket milk volumes move little from year to year.
United Kingdom
British milk supply is falling after a record year, and that will shape prices through the forecast period. AHDB forecasts 12,737 million litres for the 2026/27 GB milk year against 13,021 million litres in 2025/26, a fall of 2.2%. The GB milking herd fell 2.2% to 1.6 million head in July 2026, the lowest number recorded. Five heatwaves and a drought forced many farms to feed winter forage in summer.
Prices are recovering from a sharp fall. The UK average farmgate milk price was 38.5 pence per litre in September 2026. That was 4.8% above August but 16.0% below a year earlier. Milk volumes purchased in September were 1,198 million litres, 2.0% lower than in September 2025. Processors raised prices in August mainly to stabilise supply, not because commodity values had recovered.
The United Kingdom therefore carries a 3.6% CAGR for 2026 to 2036 on tight supply and rising costs. Feed, fuel, fertiliser and labour costs are all rising. Margin pressure varies by contract type and region. Processors with aligned retail contracts can pass some of that cost to grocers. Those selling into commodity cheese and butter cannot. FAO reported that cheese prices declined across the major exporting regions in September 2026. Retailers will keep milk as a traffic driver, so growth will come from cheese, yogurt and protein lines. A second dry summer would cut supply further and push processors to import more cheese. Buyers should expect milk contracts to carry more cost-tracking clauses as processors try to hold their supply base.
Germany
Germany entered 2026 with more milk and much lower prices. Deliveries rose 1.0% to 31.6 million tonnes in 2025, including 1.4 million tonnes of organic milk. The dairy herd stood at 3.6 million cows in November 2025. The conventional farmgate price averaged 52.2 cents per kg across 2025. It then fell to 43.5 cents in December 2025 and 37.9 cents in February 2026. Organic milk held at 65.4 cents in February 2026, so the premium for organic supply widened.
Processors responded by pushing milk into butter and powder. German deliveries in January to February 2026 were 349.5 thousand tonnes higher than a year earlier. Across the EU, butter output rose 9.2% over January to June 2026 and skim milk powder output rose 11.1%. German deliveries added to that EU volume, and export demand for butter absorbed much of it.
Consolidation and organic milk give Germany a 3.5% CAGR over 2026 to 2036. The Arla and DMK merger took effect on 1 June 2026. It brings German milk into a cooperative with a pool of about 20.0 billion kg. A larger cooperative can run German plants at higher utilisation and sell branded lines across more countries. Price-sensitive households will keep discounters central to milk and cheese sales. Organic and regional brands offer the main route to higher prices per litre. Processors should expect farmgate prices to recover slowly because EU raw milk prices were still 20.4% below a year earlier in July 2026. Farms that switched to organic supply will hold their income better through that recovery.
France
French dairies spent early 2026 turning a milk surplus into butter and powder. FranceAgriMer reported February 2026 collection of 1.93 billion litres, up 6.4% on February 2025. The standard French milk price was EUR 427.1 per 1,000 litres that month. That was EUR 40.8 lower than a year earlier. Dairies used the extra milk for fat and powder. Butter output rose 10.2% and skim milk powder output rose 10.1% in February, while cheese output fell 1.9%.
Cheese remains the core of French dairy value. A fall in cheese output while collection rises shows plants chasing powder and butter prices more than retail demand. Whey prices reached EUR 1,520.0 per tonne in week 17 of 2026, close to their 2022 peak. That rewarded cheese plants that sell whey as a protein ingredient. The link between cheese and whey is now central to processor margins.
A 3.2% CAGR over 2026 to 2036 for France reflects a mature retail market where growth depends on export cheese and protein ingredients. Danone reported like-for-like sales growth of 3.5% for first-half 2026. Its high-protein yogurt grew at a double-digit rate in every region. Supermarket price negotiations will limit retail growth at home. Summer heat threatens supply. FAO noted limited milkfat availability in Europe after a hot and dry summer in 2026. Processors that balance cheese, whey and branded yogurt will outperform those tied to commodity powder. French cooperatives should expect pressure on milk prices to continue until EU supply growth slows. Export cheese will carry most of the value growth in the meantime.
Italy
Italian dairy value is driven by cheese exports more than by fluid milk. Cheese exports reached 678,974 tonnes in 2025, up 4.6%. Their value rose 12.8% to EUR 6,085.8 million. Growth continued in 2026. Exports reached 223,050 tonnes in January to April, up 3.2%. They were worth EUR 1,977.0 million, a rise of 3.5%. Value grew faster than volume in 2025, which shows that Italian cheese commanded higher prices abroad.
EU raw milk prices set the cost base for Italian cheese makers. The EU raw milk price of EUR 42.0 per 100 kg in July 2026 was 20.4% below a year earlier. Cheaper milk improves margins at home but also makes foreign cheese cheaper on Italian shelves. FAO reported weaker buying interest for EU cheese in September 2026 as abundant US export supplies weighed on prices.
Export cheese supports a 3.1% CAGR for Italy over 2026 to 2036, a rate held back by a flat home market. Export growth slowed from 12.8% in value in 2025 to 3.5% in early 2026 as prices stopped rising. Italian processors depend on open export markets for aged cheese. A new tariff would hurt the highest-value lines first. The home market offers little volume growth. Processors with protected designations will keep pricing power abroad. Those making standard mozzarella and fresh cheese will compete on cost with imports. Buyers abroad should expect Italian cheese prices to hold even as EU milk stays cheap.
Japan
Japan's dairy processors are growing sales while the raw milk behind them declines. J-Milk expects raw milk output of 7,331 thousand tonnes in fiscal 2026, down 0.9% from 7,396 thousand tonnes in fiscal 2025. Drinking-milk processing is expected to fall 1.2% to 3,790 thousand tonnes. Milk for cheese is expected to rise 2.3% to 446 thousand tonnes. In May 2026 national output was already 1.9% below a year earlier, with both Hokkaido and the prefectures down.
Fewer litres of fluid milk do not mean falling dairy sales. Meiji Holdings reported first-quarter net sales of JPY 289.4 billion for April to June 2026, up 5.8%. Its operating profit rose 27.7%. Japanese processors earn their growth from yogurt, cheese and nutrition products that carry higher prices than milk. Convenience stores sell much of that range in single-serve packs.
Shrinking supply and an ageing population hold Japan to a 2.9% CAGR over 2026 to 2036, below every other profiled country. Butter output is forecast at 77.8 thousand tonnes in fiscal 2026, up 0.4%, which leaves little surplus for export. Imports of cheese and butter will replace the milk lost as prefectural farms close. Processors must pay enough to keep Hokkaido farms in business while holding retail prices that households accept. Products with a health claim and a long shelf life will carry most of the value growth. Suppliers with strong convenience store distribution will keep the advantage in this market.
Who are the notable companies in the Dairy Products Market?
Lactalis, Nestlé, Danone, Fonterra and Arla Foods set the commercial pattern of this market. Lactalis grew by acquisition in 2026 when it completed the purchase of Fonterra's Mainland Group consumer and associated businesses on 31 March 2026. Fonterra kept its consumer business and Anchor brand in Greater China and most of its ingredients and foodservice operations, although the sale included its Oceania ingredients and foodservice business. Nestlé reported organic growth of 3.6% for the six months to June 2026 on total sales of CHF 43.1 billion. Its Coffee mate creamer brand declined in the second quarter. Danone grew its Essential Dairy and Plant-based business by 3.8% like-for-like in the second quarter of 2026 on high-protein yogurt.
European cooperatives compete on milk volume and farmer returns. Arla Foods merged with DMK on 1 June 2026 and expects revenue of EUR 16.8 billion to EUR 17.6 billion for 2026. FrieslandCampina reported revenue of EUR 6,834.0 million for the first half of 2026. It announced an investment programme of more than EUR 90.0 million for technology upgrades at three Dutch plants. Both pay members a milk price that falls when commodity markets weaken.
North American and Asian processors show different models. Saputo reported revenue of CAD 17,551.0 million for fiscal 2026. It closed its Green Bay plant in December 2025 and moved that production to Franklin in Wisconsin. Mengniu lifted first-half 2026 revenue by 7.8% to CNY 44.8 billion through fresh milk, cheese and formula. Meiji grew first-quarter sales by 5.8% to JPY 289.4 billion. Buyers should compare each supplier on milk sourcing, cold-chain reach and the share of branded protein lines in its mix.
Key Developments in the Dairy Products Market
- In June 2026, Royal FrieslandCampina N.V. officially commissioned expanded butter production capacity at its Lochem facility in the Netherlands. The investment centralises all FrieslandCampina butter production at Lochem following the June 2025 closure of the Den Bosch butter plant, and supports brands including Debic, Campina Botergoud, Frico, and Frau Antje across professional and consumer channels [33].
- In June 2026, Arla Foods amba and DMK Group completed their merger to form Europe’s largest farmer-owned dairy cooperative, effective 1 June 2026. The combined entity unites approximately 11,200 dairy farmers and 28,800 employees under the Arla Foods name, with combined annual revenues exceeding EUR 20 billion [34].
- In March 2026, Fonterra Co-operative Group Ltd completed the sale of its global consumer and associated businesses, Mainland Group, to Lactalis. The transaction transferred consumer brands including Anchor, Mainland, and Kāpiti to Lactalis, with Fonterra returning NZD 4.22 billion in proceeds to farmer shareholders [35].
Key Players in the Dairy Products Market
- Lactalis
- Nestlé S.A.
- Danone S.A.
- Fonterra Co-operative Group Limited
- Arla Foods amba
- Royal FrieslandCampina N.V.
- Saputo Inc.
- China Mengniu Dairy Company Limited
- Meiji Holdings Co., Ltd.
Dairy Products Market Report Scope
Table 6: Dairy Products Market Report Scope
| Coverage field | Report scope |
|---|---|
| Market definition | Revenue from processed dairy products made from animal milk, including fluid milk, cheese, yogurt, butter, cream, milk powders and ice cream, sold through retail and food service. Plant-based substitutes are excluded. |
| Product Type | Milk; Cheese; Yogurt; Butter; Cream; Milk Powder; Ice Cream; Others |
| Distribution Channel | Convenience Stores; Supermarkets and Hypermarkets; Specialty Stores; Online Retail; Food Service; Others |
| Source | Cow Milk; Buffalo Milk; Goat Milk; Sheep Milk; Camel and Other Milk |
| Product Form and Flavour | Slices, Shreds and Blocks; Drinkable Liquids and Shakes; Set Tubs and Cups; Spreads and Dips; Plain and Unsweetened; Fruit-Flavoured and Indulgent; Savoury and Herbed |
| Channel share basis | The Convenience Stores share of 66.6% is carried as given in FMI's channel assessment and is not reinterpreted in this report |
| Regions covered | North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, Middle East and Africa |
| Profiled markets | China, South Korea, United States, New Zealand, Australia, United Kingdom, Germany, France, Italy, Japan |
| Companies covered | Lactalis; Nestlé S.A.; Danone S.A.; Fonterra Co-operative Group Limited; Arla Foods amba; Royal FrieslandCampina N.V.; Saputo Inc.; China Mengniu Dairy Company Limited; Meiji Holdings Co., Ltd. |
| Quantitative Units | USD billion |
Source: Future Market Insights analysis of the dairy products market, 2026.
Dairy Products Market Research Methodology
The dairy products assessment draws on agricultural statistics, milk market observatories, trade data and company disclosures. FMI measures annual revenue from processed dairy products sold to households and food service. Segment values are classified by product type, distribution channel and source. Country forecasts reflect local milk supply, farmgate prices and trade over the same 2026 to 2036 period. Milk volumes, farmgate prices and product revenue are reviewed as separate measures.
Dairy Products Market by Segments
Dairy Products Market segmented by Product Type:
- Milk
- Cheese
- Yogurt
- Butter
- Cream
- Milk Powder
- Ice Cream
- Others
Dairy Products Market segmented by Distribution Channel:
- Convenience Stores
- Supermarkets and Hypermarkets
- Specialty Stores
- Online Retail
- Food Service
- Others
Dairy Products Market segmented by Source:
- Cow Milk
- Buffalo Milk
- Goat Milk
- Sheep Milk
- Camel and Other Milk
Dairy Products Market segmented by Product Form:
- Slices, Shreds and Blocks
- Drinkable Liquids and Shakes
- Set Tubs and Cups
- Spreads and Dips
Dairy Products Market segmented by Flavour:
- Plain and Unsweetened
- Fruit-Flavoured and Indulgent
- Savoury and Herbed
Dairy Products Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Ireland
- Denmark
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] U.S. Department of Agriculture, Economic Research Service. (2026, October 16). Livestock, Dairy, and Poultry Outlook: October 2026 (LDP-M-388).
- [2] U.S. Department of Agriculture, National Agricultural Statistics Service. (2026, September 22). Milk Production. https://esmis.nal.usda.gov/sites/default/release-files/796070/mkpr0926.pdf
- [3] U.S. Department of Agriculture, Animal and Plant Health Inspection Service. (2026, October 8). USDA Confirms Highly Pathogenic Avian Influenza in Two Dairy Herds in Washington. https://www.aphis.usda.gov/print/pdf/node/8319
- [4] Food and Agriculture Organization of the United Nations. (2026, October 2). FAO Food Price Index.
- [5] Food and Agriculture Organization of the United Nations. (2024). Gateway to dairy production and products: Dairy animals, accessed 3 November 2026. https://www.fao.org/dairy-production-products/production/dairy-animals/en
- [6] European Commission, Directorate-General for Agriculture and Rural Development. (2026, September 17). Milk market situation factsheet.
- [7] European Commission, Directorate-General for Agriculture and Rural Development. (2026). Short-term outlook for EU agricultural markets: Autumn 2026 edition. https://agriculture.ec.europa.eu/data-and-analysis/markets/outlook/short-term_en
- [8] Agriculture and Horticulture Development Board. (2026, October 14). Dairy October 2026 forecast update: GB milk production under pressure. https://ahdb.org.uk/news/dairy-october-2026-forecast-update-gb-milk-production-under-pressure
- [9] Department for Environment, Food and Rural Affairs. (2026, October 29). United Kingdom milk prices and composition of milk statistics notice (data for September 2026). https://www.gov.uk/government/statistics/uk-milk-prices-and-composition-of-milk/united-kingdom-milk-prices-and-composition-of-milk-statistics-notice-data-for-september-2026
- [10] FranceAgriMer. (2026, April). Note de conjoncture mensuelle: Filière lait de vache. https://www.franceagrimer.fr/sites/default/files/2026-05/NCO-NOT-LAI-2026-04.pdf
- [11] Bundesanstalt für Landwirtschaft und Ernährung. (2026, August). Bericht zur Markt- und Versorgungslage Milch und Milcherzeugnisse 2026. https://bmel-statistik.de/fileadmin/daten/0611100-2026.pdf
- [12] Assolatte. (2026). Le esportazioni italiane di formaggi (gennaio-dicembre 2025). Istat data. https://www.assolatte.it/zpublish/4/uploads/4/eco_cate/17734129068187643865_Export%20formaggi%20dicembre%202025.pdf
- [13] Assolatte. (2026). Le esportazioni italiane di formaggi (gennaio-aprile 2026). Istat data. https://cms.assolatte.it/zpreview/4/uploads/4/eco_cate/1784714392751825244_Export%20formaggi%20gennaio-aprile%202026.pdf
- [14] National Data Agency, Republic of Korea. (2026, October 23). 2026년 3분기 가축동향조사 결과 (Livestock Trend Survey results, third quarter 2026). Korea Development Institute Economic Information and Education Center. https://eiec.kdi.re.kr/policy/materialView.do?num=288440
- [15] U.S. Department of Agriculture, Foreign Agricultural Service. (2024). South Korea: Dairy and Products Annual (KS2024-0025). https://www.fas.usda.gov/data/south-korea-dairy-and-products-annual-8
- [16] Japan Dairy Association (J-Milk). (2026, July 31). 2026年度の生乳および牛乳乳製品の需給見通しと課題について (Outlook and issues for raw milk and dairy product supply and demand in fiscal 2026). https://www.j-milk.jp/gyokai/jukyu/h4ogb4000000n7tz-att/a1785480124306.pdf
- [17] Japan Dairy Association (J-Milk). (2026, July 9). Jミルク需給短信【7月】 (Supply and demand bulletin, July 2026). https://www.j-milk.jp/gyokai/jukyu/h4ogb4000000lxhq-att/h4ogb4000000mzbj.pdf
- [18] National Bureau of Statistics of China. (2026, January 19). National Economy Made Steady Progress with Expected Targets Achieved Successfully in 2025.
- [19] Dairy Australia. (2025). The Australian Dairy Industry In Focus 2025. https://assets.dairyaustralia.com.au/api/public/content/In-Focus-2025
- [20] Fonterra Co-operative Group Limited. (2026, September 24). Fonterra delivers strong FY26 performance. https://www.fonterra.com/nz/en/our-stories/media/fonterra-delivers-strong-fy26-performance.html
- [21] Fonterra Co-operative Group Limited. (2026, March 31). Fonterra completes sale of Mainland Group to Lactalis. https://www.fonterra.com/au/en/our-stories/media/fonterra-completes-sale-of-mainland-group-to-lactalis.html
- [22] Fonterra Co-operative Group Limited. (2026, July 12). Fonterra revises its 2026/27 forecast Farmgate Milk Price. NZX announcement. https://announcements.nzx.com/announcement/475956
- [23] Ministry for Primary Industries, New Zealand. (2026, June). Situation and Outlook for Primary Industries, June 2026. https://www.mpi.govt.nz/news-and-resources/economic-intelligence-unit/situation-and-outlook-for-primary-industries/
- [24] Arla Foods amba. (2026, August 27). Surging brands and strong protein demand drive Arla Foods to a standout first half. https://arla.com/company/news-and-press/2026/pressrelease/surging-brands-and-strong-protein-demand-drive-arla-foods-to-a-standout-first-half
- [25] Royal FrieslandCampina N.V. (2026, July 17). Half-year report 2026. https://www.frieslandcampina.com/uploads/2026/07/Half-year-report-2026-Royal-FrieslandCampina-NV.pdf
- [26] Danone S.A. (2026, July 29). First-half 2026 results: conference call transcript. https://www.danone.com/content/dam/corp/global/danonecom/investors/en-result-center/2026/transcriptH126danone.pdf
- [27] Saputo Inc. (2026, June 4). Saputo Reports Financial Results for the Fourth Quarter and Fiscal 2026. https://newsroom.saputo.com/news-releases/news-release-details/saputo-reports-financial-results-fourth-quarter-and-fiscal-2026
- [28] China Mengniu Dairy Company Limited. (2026, August 27). 2026 interim results press release. https://www.mengniuir.com/pdf/press/20260827_en.pdf
- [29] Nestlé S.A. (2026, July 23). Half-year results 2026: execution driving RIG. https://www.nestle.com/media/pressreleases/allpressreleases/half-year-results-2026
- [30] Meiji Holdings Co., Ltd. (2026, August 5). Consolidated financial results for the first quarter of the fiscal year ending March 2027. Japan Exchange Group. https://www2.jpx.co.jp/disc/22690/081220260804508801_tse-qcedjpsm-22690-20260805322690-ixbrl.htm
- [31] International Dairy Foods Association. (2026, October 20). U.S. Dairy Processing Invests $15 Billion in Manufacturing Across 23 States. https://www.idfa.org/news/u-s-dairy-processing-invests-15-billion-in-manufacturing-across-23-states
- [32] National Association of Convenience Stores. (2026, April 15). U.S. Convenience In-Store Sales Top $340 Billion. https://www.convenience.org/stay-current/press-releases/2026-press-releases/u-s-convenience-in-store-sales-top-$340-billion
- [33] Royal FrieslandCampina N.V. (2026). FrieslandCampina expands butter production capacity at its Lochem butter factory. As reported by OFI Magazine: https://www.ofimagazine.com/news/friesland-campina-expands-butter-production-capacity-at-lochem-factory
- [34] Arla Foods amba. (2026). Arla Foods and DMK Group officially unite to create Europe’s leading dairy cooperative. https://www.arla.com/company/news-and-press/2026/pressrelease/arla-foods-and-dmk-group-officially-unite-to-create-europes-leading-dairy-cooperative/
- [35] Fonterra Co-operative Group Ltd. (2026). Fonterra completes sale of Mainland Group to Lactalis. https://www.fonterra.com/nz/en/our-stories/media/fonterra-completes-sale-of-mainland-group-to-lactalis.html
Table of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
Read More...
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Product Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Type, 2026 to 2036
- Milk
- Cheese
- Yogurt
- Butter
- Cream
- Milk Powder
- Ice Cream
- Others
- Y-o-Y Growth Trend Analysis By Product Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Type, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Convenience Stores
- Supermarkets and Hypermarkets
- Specialty Stores
- Online Retail
- Food Service
- Others
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source, 2026 to 2036
- Cow Milk
- Buffalo Milk
- Goat Milk
- Sheep Milk
- Camel and Other Milk
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Product Form, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Product Form, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Product Form, 2026 to 2036
- Slices, Shreds and Blocks
- Drinkable Liquids and Shakes
- Set Tubs and Cups
- Spreads and Dips
- Y-o-Y Growth Trend Analysis By Product Form, 2021 to 2025
- Absolute $ Opportunity Analysis By Product Form, 2026 to 2036
- Global Market Analysis and Forecast, By Flavour, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Flavour, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Flavour, 2026 to 2036
- Plain and Unsweetened
- Fruit-Flavoured and Indulgent
- Savoury and Herbed
- Y-o-Y Growth Trend Analysis By Flavour, 2021 to 2025
- Absolute $ Opportunity Analysis By Flavour, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Ireland
- Denmark
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- By Country
- Market Attractiveness Analysis
- By Country
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Product Type
- By Distribution Channel
- By Source
- By Product Form
- By Flavour
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Lactalis
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Fonterra Co-operative Group Limited
- Arla Foods amba
- Danone S.A.
- China Mengniu Dairy Company Limited
- Nestlé S.A.
- Royal FrieslandCampina N.V.
- Saputo Inc.
- Meiji Holdings Co., Ltd.
- Lactalis
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used
List of Tables
- Table 1: Global Market Value (USD Billion) Forecast by Region, 2021 to 2036
- Table 2: Global Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 3: Global Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 4: Global Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 5: Global Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 6: Global Market Value (USD Billion) Forecast by Flavour, 2021 to 2036
- Table 7: North America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 8: North America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 9: North America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 10: North America Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 11: North America Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 12: North America Market Value (USD Billion) Forecast by Flavour, 2021 to 2036
- Table 13: Latin America Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 14: Latin America Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 15: Latin America Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 16: Latin America Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 17: Latin America Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 18: Latin America Market Value (USD Billion) Forecast by Flavour, 2021 to 2036
- Table 19: Western Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 20: Western Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 21: Western Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 22: Western Europe Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 23: Western Europe Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 24: Western Europe Market Value (USD Billion) Forecast by Flavour, 2021 to 2036
- Table 25: Eastern Europe Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 26: Eastern Europe Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 27: Eastern Europe Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 28: Eastern Europe Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 29: Eastern Europe Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 30: Eastern Europe Market Value (USD Billion) Forecast by Flavour, 2021 to 2036
- Table 31: East Asia Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 32: East Asia Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 33: East Asia Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 34: East Asia Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 35: East Asia Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 36: East Asia Market Value (USD Billion) Forecast by Flavour, 2021 to 2036
- Table 37: South Asia and Pacific Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 38: South Asia and Pacific Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 39: South Asia and Pacific Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 40: South Asia and Pacific Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 41: South Asia and Pacific Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 42: South Asia and Pacific Market Value (USD Billion) Forecast by Flavour, 2021 to 2036
- Table 43: Middle East and Africa Market Value (USD Billion) Forecast by Country, 2021 to 2036
- Table 44: Middle East and Africa Market Value (USD Billion) Forecast by Product Type, 2021 to 2036
- Table 45: Middle East and Africa Market Value (USD Billion) Forecast by Distribution Channel, 2021 to 2036
- Table 46: Middle East and Africa Market Value (USD Billion) Forecast by Source, 2021 to 2036
- Table 47: Middle East and Africa Market Value (USD Billion) Forecast by Product Form, 2021 to 2036
- Table 48: Middle East and Africa Market Value (USD Billion) Forecast by Flavour, 2021 to 2036
List of Figures
- Figure 1: Global Market Pricing Analysis
- Figure 2: Global Market Value (USD Billion) Forecast 2021-2036
- Figure 3: Global Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 4: Global Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 5: Global Market Attractiveness Analysis by Product Type
- Figure 6: Global Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 7: Global Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 8: Global Market Attractiveness Analysis by Distribution Channel
- Figure 9: Global Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 10: Global Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 11: Global Market Attractiveness Analysis by Source
- Figure 12: Global Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 13: Global Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 14: Global Market Attractiveness Analysis by Product Form
- Figure 15: Global Market Value Share and BPS Analysis by Flavour, 2026 and 2036
- Figure 16: Global Market Y-o-Y Growth Comparison by Flavour, 2026-2036
- Figure 17: Global Market Attractiveness Analysis by Flavour
- Figure 18: Global Market Value (USD Billion) Share and BPS Analysis by Region, 2026 and 2036
- Figure 19: Global Market Y-o-Y Growth Comparison by Region, 2026-2036
- Figure 20: Global Market Attractiveness Analysis by Region
- Figure 21: North America Market Incremental Dollar Opportunity, 2026-2036
- Figure 22: Latin America Market Incremental Dollar Opportunity, 2026-2036
- Figure 23: Western Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 24: Eastern Europe Market Incremental Dollar Opportunity, 2026-2036
- Figure 25: East Asia Market Incremental Dollar Opportunity, 2026-2036
- Figure 26: South Asia and Pacific Market Incremental Dollar Opportunity, 2026-2036
- Figure 27: Middle East and Africa Market Incremental Dollar Opportunity, 2026-2036
- Figure 28: North America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 29: North America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 30: North America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 31: North America Market Attractiveness Analysis by Product Type
- Figure 32: North America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 33: North America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 34: North America Market Attractiveness Analysis by Distribution Channel
- Figure 35: North America Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 36: North America Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 37: North America Market Attractiveness Analysis by Source
- Figure 38: North America Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 39: North America Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 40: North America Market Attractiveness Analysis by Product Form
- Figure 41: North America Market Value Share and BPS Analysis by Flavour, 2026 and 2036
- Figure 42: North America Market Y-o-Y Growth Comparison by Flavour, 2026-2036
- Figure 43: North America Market Attractiveness Analysis by Flavour
- Figure 44: Latin America Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 45: Latin America Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 46: Latin America Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 47: Latin America Market Attractiveness Analysis by Product Type
- Figure 48: Latin America Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 49: Latin America Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 50: Latin America Market Attractiveness Analysis by Distribution Channel
- Figure 51: Latin America Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 52: Latin America Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 53: Latin America Market Attractiveness Analysis by Source
- Figure 54: Latin America Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 55: Latin America Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 56: Latin America Market Attractiveness Analysis by Product Form
- Figure 57: Latin America Market Value Share and BPS Analysis by Flavour, 2026 and 2036
- Figure 58: Latin America Market Y-o-Y Growth Comparison by Flavour, 2026-2036
- Figure 59: Latin America Market Attractiveness Analysis by Flavour
- Figure 60: Western Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 61: Western Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 62: Western Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 63: Western Europe Market Attractiveness Analysis by Product Type
- Figure 64: Western Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 65: Western Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 66: Western Europe Market Attractiveness Analysis by Distribution Channel
- Figure 67: Western Europe Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 68: Western Europe Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 69: Western Europe Market Attractiveness Analysis by Source
- Figure 70: Western Europe Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 71: Western Europe Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 72: Western Europe Market Attractiveness Analysis by Product Form
- Figure 73: Western Europe Market Value Share and BPS Analysis by Flavour, 2026 and 2036
- Figure 74: Western Europe Market Y-o-Y Growth Comparison by Flavour, 2026-2036
- Figure 75: Western Europe Market Attractiveness Analysis by Flavour
- Figure 76: Eastern Europe Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 77: Eastern Europe Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 78: Eastern Europe Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 79: Eastern Europe Market Attractiveness Analysis by Product Type
- Figure 80: Eastern Europe Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 81: Eastern Europe Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 82: Eastern Europe Market Attractiveness Analysis by Distribution Channel
- Figure 83: Eastern Europe Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 84: Eastern Europe Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 85: Eastern Europe Market Attractiveness Analysis by Source
- Figure 86: Eastern Europe Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 87: Eastern Europe Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 88: Eastern Europe Market Attractiveness Analysis by Product Form
- Figure 89: Eastern Europe Market Value Share and BPS Analysis by Flavour, 2026 and 2036
- Figure 90: Eastern Europe Market Y-o-Y Growth Comparison by Flavour, 2026-2036
- Figure 91: Eastern Europe Market Attractiveness Analysis by Flavour
- Figure 92: East Asia Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 93: East Asia Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 94: East Asia Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 95: East Asia Market Attractiveness Analysis by Product Type
- Figure 96: East Asia Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 97: East Asia Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 98: East Asia Market Attractiveness Analysis by Distribution Channel
- Figure 99: East Asia Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 100: East Asia Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 101: East Asia Market Attractiveness Analysis by Source
- Figure 102: East Asia Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 103: East Asia Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 104: East Asia Market Attractiveness Analysis by Product Form
- Figure 105: East Asia Market Value Share and BPS Analysis by Flavour, 2026 and 2036
- Figure 106: East Asia Market Y-o-Y Growth Comparison by Flavour, 2026-2036
- Figure 107: East Asia Market Attractiveness Analysis by Flavour
- Figure 108: South Asia and Pacific Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 109: South Asia and Pacific Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 110: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 111: South Asia and Pacific Market Attractiveness Analysis by Product Type
- Figure 112: South Asia and Pacific Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 113: South Asia and Pacific Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 114: South Asia and Pacific Market Attractiveness Analysis by Distribution Channel
- Figure 115: South Asia and Pacific Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 116: South Asia and Pacific Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 117: South Asia and Pacific Market Attractiveness Analysis by Source
- Figure 118: South Asia and Pacific Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 119: South Asia and Pacific Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 120: South Asia and Pacific Market Attractiveness Analysis by Product Form
- Figure 121: South Asia and Pacific Market Value Share and BPS Analysis by Flavour, 2026 and 2036
- Figure 122: South Asia and Pacific Market Y-o-Y Growth Comparison by Flavour, 2026-2036
- Figure 123: South Asia and Pacific Market Attractiveness Analysis by Flavour
- Figure 124: Middle East and Africa Market Value Share and BPS Analysis by Country, 2026 and 2036
- Figure 125: Middle East and Africa Market Value Share and BPS Analysis by Product Type, 2026 and 2036
- Figure 126: Middle East and Africa Market Y-o-Y Growth Comparison by Product Type, 2026-2036
- Figure 127: Middle East and Africa Market Attractiveness Analysis by Product Type
- Figure 128: Middle East and Africa Market Value Share and BPS Analysis by Distribution Channel, 2026 and 2036
- Figure 129: Middle East and Africa Market Y-o-Y Growth Comparison by Distribution Channel, 2026-2036
- Figure 130: Middle East and Africa Market Attractiveness Analysis by Distribution Channel
- Figure 131: Middle East and Africa Market Value Share and BPS Analysis by Source, 2026 and 2036
- Figure 132: Middle East and Africa Market Y-o-Y Growth Comparison by Source, 2026-2036
- Figure 133: Middle East and Africa Market Attractiveness Analysis by Source
- Figure 134: Middle East and Africa Market Value Share and BPS Analysis by Product Form, 2026 and 2036
- Figure 135: Middle East and Africa Market Y-o-Y Growth Comparison by Product Form, 2026-2036
- Figure 136: Middle East and Africa Market Attractiveness Analysis by Product Form
- Figure 137: Middle East and Africa Market Value Share and BPS Analysis by Flavour, 2026 and 2036
- Figure 138: Middle East and Africa Market Y-o-Y Growth Comparison by Flavour, 2026-2036
- Figure 139: Middle East and Africa Market Attractiveness Analysis by Flavour
- Figure 140: Global Market - Tier Structure Analysis
- Figure 141: Global Market - Company Share Analysis
Frequently Asked Questions
How big is the dairy products market in 2026?
FMI estimates the market at USD 540.0 billion in 2026, up from USD 515.3 billion in 2025. It is forecast to reach USD 863.0 billion by 2036 at a 4.8% CAGR.
Which distribution channel leads the dairy products market in 2026?
Convenience Stores lead by distribution channel with 66.6% in 2026. All other channels together hold 33.4%.
Which product type and source lead in 2026?
Milk holds 42.3% by product type. Cow Milk holds 81.0% by source in FMI's 2026 assessment.
Which country is forecast to grow fastest through 2036?
China has the highest forecast CAGR at 6.4% during 2026 to 2036, followed by South Korea at 5.2%. These are FMI forecasts and are not rates reported by the cited public bodies.
How do farmgate milk prices affect dairy product supply?
Low farmgate prices push farmers to cut herds, which limits later supply. The EU raw milk price was EUR 42.0 per 100 kg in July 2026, 20.4% below a year earlier [6].
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDF
