

- Market Size (2026)
- USD 36.4 Bn
- Forecast (2036)
- USD 63.3 Bn
- CAGR (2026 to 2036)
- 5.7%
How big is Chemical Testing Services Market in 2026?
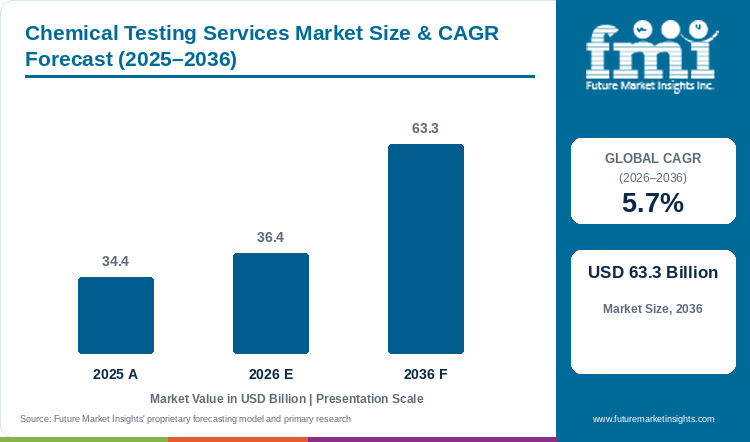
Chemical testing services market size stood at USD 34.40 billion in 2025, reaches USD 36.4 billion in 2026 and is projected at USD 63.30 billion by 2036. Demand for chemical testing services is set to expand at a 5.7% CAGR from 2026 to 2036, as manufacturers submit more samples for compliance and quality checks.
Demand for chemical testing services is rising fastest in markets with rising regulatory filing volumes. The U.S. EPA extended the Section 8(d) health and safety study deadline for 16 chemicals including benzene, styrene and naphthalene, with filings for 15 of these chemicals due September 9, 2025, a step that mainly requires manufacturers to compile and submit already-completed studies rather than commission new lab work [1]. The European Union's proposed universal PFAS restriction, first put forward in February 2023 and updated by ECHA in August 2025, is adding to REACH dossier testing obligations for manufacturers and importers [2]. China's Ministry of Ecology and Environment received 3,264 new chemical record notifications in the first half of 2025, covering 16,619 substances, figures made public on August 29, 2025, under a simplified registration route for lower-risk new substances [3]. Due to this, laboratories across the United States, the European Union and China are each handling a growing filing load tied to PFAS detection and REACH dossier testing work in particular. FMI puts outsourced services in the lead with 61% of sourcing sales in 2026, as manufacturers turn to accredited third-party labs instead of building in-house capacity for filings tied to each regime. Rising filing volume tied to REACH, TSCA and China's chemical substance rules is anticipated to keep demand for outsourced testing capacity ahead of in-house options through 2036.
Key Market Trends & Insights
- By testing service type, chemical composition analysis leads with 21% of 2026 sales, as manufacturers confirm material content before every shipment.
- By sample type, polymers and plastics hold 19% of 2026 sales. SGS added environmental and PFAS testing capacity in Michigan after acquiring RTI Laboratories in January 2025.
- By end use, consumer goods account for 22% in 2026, owing to retailers and brand owners requiring supply chain compliance checks before listing a product.
- By service delivery mode, laboratory testing accounts for 68% of 2026 sales, and accredited lab capacity will keep laboratories as the main delivery channel through 2036. Japan revised Chemical Substances Control Law enforcement rules effective April 1, 2025, changing production volume reporting formats for four substance categories.
- By sourcing, outsourced services collect 61% of 2026 sales, as manufacturers prefer accredited third-party labs over building in-house testing capacity.
Regional Highlights
- The fastest profiled-country growth comes from China, at 7.4% CAGR to 2036.
- USA follows at 6.8%, with Australia at 5.9% and Japan at 5.4%; Germany records the slowest profiled pace at 5.0% through 2036, reflecting contracting chemical industry output.
- Chinese laboratories are handling a growing filing load, even though the Ministry of Ecology and Environment logged 3,264 new chemical record notifications under a simplified, lower-testing registration route in the first half of 2025 [3].
Market Size & Forecast
Table 1: Market Size and Forecast for the Chemical Testing Services Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 34.40 billion |
| Estimated Market Size in 2026 | USD 36.4 billion |
| Projected Market Size by 2036 | USD 63.30 billion |
| CAGR, 2026 to 2036 | 5.7% |
| Incremental Opportunity, 2026 to 2036 | USD 26.94 billion |
| Market Expansion Multiple | 1.7x |
Most chemical testing orders now come from manufacturers meeting compliance deadlines under REACH, TSCA and China's chemical substance rules. Confirmed material composition and contaminant-free certificates are the main reason a buyer approves a lab contract. Regulatory filing deadlines add pressure across major markets: Australia's AICIS and the EU's REACH regime both require new PFAS testing ahead of their filing windows, while the EPA's September 9, 2025 deadline requires manufacturers to submit already-completed health and safety studies on 15 chemicals under TSCA Section 8(d) [1]. The EU's universal PFAS restriction, proposed in February 2023 and updated by ECHA in August 2025, adds a similar filing load for REACH dossiers [2]. At the compliance end, accredited laboratories are expanding capacity, as SGS added PFAS and environmental testing capability through the RTI Laboratories acquisition completed in January 2025. High laboratory accreditation and equipment costs can still delay new entrants from matching established testing groups. Expanding regulatory filing volume across major chemical markets is anticipated to drive most new testing contracts through 2036.
Regulatory Filing Volume and Laboratory Capacity
Sales of chemical testing services keep rising as governments add more substances to national compliance lists. The EPA extended Section 8(d) study deadlines for 16 chemicals including benzene, styrene and naphthalene, requiring manufacturers to submit already-completed health and safety studies by September 9, 2025 for most of these chemicals [1]. Germany's chemical industry output fell about 2.5% in 2025, and VCI forecast a further 1% decline for 2026, with plants running at about 70% of capacity, a historic low. Due to this, German manufacturers are directing testing budgets toward compliance work instead of new product lines. China's Ministry of Ecology and Environment logged 3,264 new chemical record notifications under a simplified registration route in the first half of 2025, covering 16,619 substances [3]. Australia's chemical regulator AICIS asked registrants on October 14, 2025 to report on 522 PFAS substances imported or manufactured in the country, with a response window of 40 working days. FMI expects accredited third-party labs to take most new filing-driven contracts in the early forecast years, as plant compliance teams look for faster turnaround on REACH, TSCA and AICIS submissions.
Laboratory groups are expanding capacity to meet the compliance calendar across these regimes. Japan's Ministry of Economy, Trade and Industry revised Chemical Substances Control Law enforcement rules through an October 2024 ordinance, with the update effective April 1, 2025. The rule changed production volume reporting formats for general chemical substances, priority assessment substances, monitoring substances and Class II specified substances. SGS strengthened the North American PFAS and environmental testing network by acquiring RTI Laboratories in Michigan, a deal announced January 20, 2025 that added an eighth PFAS laboratory and a fifth laboratory certified by the U.S. Department of Defense. Consolidation among large accredited groups is shifting niche PFAS and specialty testing toward labs with Department of Defense and state-level certification. Smaller independent labs are competing on turnaround speed and local accreditation, not the full compliance portfolio that global groups offer. China logged 16,619 new chemical substances through its simplified notification route in the first half of 2025 [3], and FMI expects outsourced testing demand tied to PFAS detection and REACH dossier work to keep rising across these three regimes through 2036. The EU's universal PFAS restriction, proposed in February 2023 and advanced through an ECHA update in August 2025, is expected to add further REACH testing volume as the dossier moves toward adoption [2].
Table 2: Regulatory Filing and Compliance Indicators for the Chemical Testing Services Market (mixed units, counts and dates), mixed reporting years from 2024 to 2025
| Indicator | Data Point | Market Relevance | Source |
|---|---|---|---|
| US TSCA Section 8(d) deadline, 2025 | Filings for 15 chemicals due September 9, 2025; covers benzene, styrene, naphthalene | Deadline requires submitting already-completed studies, a compliance task rather than new testing demand. | [1] |
| EU REACH PFAS restriction proposal | Universal restriction proposed February 2023; ECHA issued an update in August 2025 | Expanding PFAS rules add new REACH testing volume. | [2] |
| China MEE new chemical notifications, 2025 H1 | 3,264 notifications covering 16,619 substances; published August 29, 2025 | Simplified notification route; limited direct effect on lab testing volume. | [3] |
| SGS acquisition of RTI Laboratories | Announced January 20, 2025; eighth PFAS lab, fifth DoD certified lab | Consolidation concentrates PFAS testing among large accredited groups. | — |
| Japan CSCL enforcement rule revision | Ordinance issued October 2024; effective April 1, 2025 | Revised reporting formats affect four substance categories. | — |
| Germany chemical industry output, 2025 | Output down about 2.5%; capacity utilisation about 70%, a historic low | Compliance testing demand holds steadier than overall output. | — |
| Germany chemical industry forecast, 2026 | Output forecast down about 1%; chemical-pharma sales forecast down about 2% | Weak output keeps testing budgets focused on compliance work. | — |
| Australia AICIS PFAS reporting round | Notices issued October 14, 2025 covering 522 PFAS substances; 40 working day response window | A short-term reporting round adds to Australian filing volume. | — |
| Japan production volume reporting categories | Four categories revised: general, priority assessment, monitoring, Class II specified chemicals | Reporting format changes affect ongoing compliance filings. | — |
Table 3: Country Compliance and Capacity Benchmarks for the Chemical Testing Services Market (mixed units and counts), mixed reporting years from 2025
| Indicator | Reported value | Related figure | Source |
|---|---|---|---|
| Chemical testing services market, 2025 to 2026 | USD 34.40 billion to USD 36.4 billion | 5.7% CAGR, 2026 to 2036 | Future Market Insights |
| China new chemical notifications, 2025 H1 | 3,264 | Covering 16,619 substances | [3] |
| US TSCA Section 8(d) deadline | September 9, 2025 | Covers 15 of 16 chemicals under the rule | [1] |
| EU PFAS restriction proposal | Published August 2025 | Not yet in force | [2] |
| SGS RTI Laboratories acquisition | Announced January 20, 2025 | Eighth PFAS lab for SGS | — |
| Japan CSCL enforcement rule update | Effective April 1, 2025 | Ordinance issued October 2024 | — |
| Germany chemical industry capacity utilisation, 2025 | About 70% | Described as a historic low by VCI | — |
| Australia AICIS PFAS reporting round | 522 substances | 40 working day response window | — |
Analyst Perspective
“Laboratories that can switch between REACH, TSCA and China's chemical substance filing formats within one accredited network will take most new compliance contracts. Groups adding PFAS and environmental testing capacity close to manufacturing clusters in the United States, the European Union and China will gain share through 2036.”
- Nikhil Kaitwade, Principal Consultant, Future Market Insights.
How is the chemical testing services market segmented?
The chemical testing services market is studied across five commercial segments plus region, namely testing service type, sample type, end use, service delivery mode and sourcing. In 2026, chemical composition analysis holds 21%, polymers and plastics 19%, consumer goods 22%, laboratory testing 68% and outsourced services 61% of respective segment sales.
By testing service type: chemical composition analysis, physical and mechanical testing, biodegradability and toxicology testing, microbiological testing, and regulatory compliance testing.
By sample type: polymers and plastics, metals and alloys, pharmaceuticals and cosmetics, and food contact materials.
By end use: consumer goods, pharmaceuticals and healthcare, industrial chemicals and petrochemicals, and food and beverage.
By service delivery mode: laboratory testing, on-site testing, remote and digital monitoring, and integrated compliance support.
By sourcing: outsourced services, hybrid sourcing, and contract research testing.
By region: North America, Latin America, Western Europe, Eastern Europe, East Asia, South Asia and Pacific, and Middle East and Africa.
Why does chemical composition analysis lead testing service type sales?
Chemical composition analysis will hold 21% of testing service type sales in 2026, as manufacturers confirm material content before every compliance filing.
Table 4: Testing Service Type Share for the Chemical Testing Services Market (percentage share), 2026
| Testing Service Type | Share (2026) |
|---|---|
| Chemical Composition Analysis | 21% |
| Other Segments Combined | 79% |
| Total | 100% |
Table 5: Testing Service Type Leadership and Market Growth for the Chemical Testing Services Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 5.7% |
| Leading Segment | Chemical Composition Analysis |
Demand for chemical composition analysis comes first in most compliance programs, as manufacturers need to confirm material content before any REACH, TSCA or China filing. FMI finds that chemical composition analysis accounts for 21% of testing service type sales in 2026. Physical and mechanical testing and biodegradability and toxicology testing usually follow once composition is confirmed, and microbiological testing serves a smaller group of food contact and pharmaceutical clients. The EPA set a September 9, 2025 deadline for manufacturers to submit already-completed health and safety studies on 15 chemicals under Section 8(d) [1]. Rising filing volume tied to REACH, TSCA and China's chemical substance rules is anticipated to keep this segment ahead through 2036.
- Chemical composition analysis holds 21% of testing service type sales in 2026, since every compliance filing starts with confirmed material content.
- Manufacturers comparing labs for composition testing should check accreditation scope, turnaround time and PFAS detection limits, as these factors set filing readiness.
Why do polymers and plastics lead sample type sales?
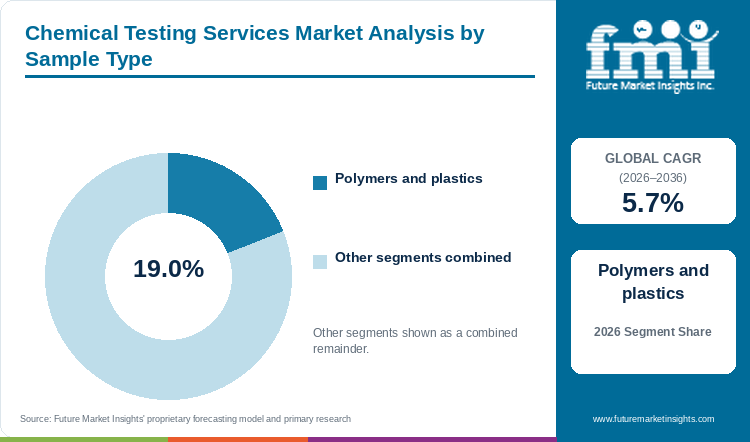
Polymers and plastics make up 19% of sample type sales in 2026, as packaging and consumer goods clients test additive and recycled content most often.
Sales of polymer and plastics testing follow packaging and consumer goods output, as recycled content and additive checks apply to most plastic parts sold into retail. As per FMI estimates, polymers and plastics hold 19% of sample type sales in 2026. Metals and alloys testing suits automotive and industrial clients, and pharmaceuticals and cosmetics testing serves a separate regulatory track. SGS added PFAS and environmental testing capacity for polymer and material clients through the RTI Laboratories acquisition completed in January 2025. Wider verification needs for recycled polymers are expected to keep this sample type ahead of other categories.
- Polymers and plastics hold 19% of sample type sales in 2026, as packaging and consumer goods clients test additive and recycled content most often.
- Buyers sourcing plastics should ask a lab for recycled-content and migration test methods, since these checks now shape most retail compliance programs.
Why does consumer goods lead end use sales?
Consumer goods account for 22% of end use sales in 2026, owing to retailer and brand owner supply chain compliance checks.
Demand for chemical testing among consumer goods makers is rising, as retailers and brand owners require supply chain compliance checks before listing a product. FMI data shows consumer goods making up 22% of end use sales in 2026. Pharmaceuticals and healthcare testing follows a separate regulatory track, and industrial chemicals and food and beverage clients test in smaller, more technical batches. Australia's AICIS asked registrants on October 14, 2025 to report on 522 PFAS substances used in consumer and industrial products. Retailer-driven compliance checks are expected to keep consumer goods testing ahead of other end use categories through 2036.
- Consumer goods account for 22% of end use sales in 2026, and retailer compliance programs will keep this end use in front through the forecast period.
- Brands sourcing consumer products should confirm a lab tests against the destination market's own substance list, since lists differ between the United States, the European Union and China.
Why does laboratory testing lead service delivery mode sales?
Laboratory testing captures 68% of service delivery mode sales in 2026, supported by equipment that only an accredited lab can run.
Accredited labs handle most chemical testing work, as physical sample analysis still needs equipment that a client site rarely has. FMI estimates that laboratory testing captures 68% of service delivery mode sales in 2026. On-site testing and remote monitoring serve production-line quality checks, and integrated compliance support bundles several delivery modes into one filing package. Japan's revised Chemical Substances Control Law enforcement rules, effective April 1, 2025, changed how production volume data is reported across four substance categories. Growing on-site testing for production-line quality control is expected to add a second delivery channel alongside laboratory testing through 2036.
- Laboratory testing captures 68% of service delivery mode sales in 2026, supported by equipment that only an accredited lab can run.
- On-site and remote monitoring buyers should confirm data from a production line still links back to an accredited lab result, since regulators generally ask for both.
What gives outsourced services the lead in sourcing demand?
Outsourced services hold 61% of sourcing sales in 2026, as manufacturers prefer accredited third-party labs over in-house testing capacity.
Manufacturers prefer sending samples to accredited third-party labs over building in-house testing capacity, as outside labs maintain accreditation across multiple regimes at once. Outsourced services hold 61% of sales by sourcing in 2026, as per FMI. In-house testing and hybrid sourcing suit larger manufacturers running high sample volumes on fixed product lines. SGS expanded the outsourced PFAS and environmental testing network in Michigan after completing the RTI Laboratories acquisition in January 2025. Laboratory consolidation among large accredited groups is anticipated to keep outsourced services ahead of in-house options through 2036.
- Buyers want one accredited partner across REACH, TSCA and China filings, giving outsourced services 61% of sourcing sales in 2026.
- Manufacturers weighing in-house testing should compare equipment and accreditation cost against the price of sending the same sample volume to an outside lab.
What are the drivers, restraints, and opportunities in the chemical testing services market?
Expanding regulatory compliance requirements push manufacturers toward accredited testing, high equipment and accreditation costs slow new entrants, and laboratory consolidation around large accredited groups opens the main opportunity for PFAS and integrated compliance support.
- Driver: Key drivers of the chemical testing services market include expanding regulatory compliance requirements under REACH, TSCA and China's chemical substance rules that require more accredited testing per shipment.
- Restraint: High capital costs for analytical equipment and the time needed to build an accreditation track record slow new entrants into chemical testing services.
- Opportunity: Laboratory consolidation around large accredited groups opens growth for integrated compliance support and PFAS testing in the chemical testing services market.
Regulatory Filing Deadlines Drive Outsourced Testing
Compliance deadlines are pushing more samples toward accredited outside labs. Australia's AICIS asked registrants on October 14, 2025 to report on 522 PFAS substances imported or manufactured in the country, a mandate that requires new PFAS testing and reporting work. The EPA's September 9, 2025 deadline for submitting already-completed health and safety studies on 15 chemicals under TSCA Section 8(d) adds a related compliance task [1]. Due to this, manufacturers without in-house toxicology or PFAS detection capability are sending more samples to accredited third-party labs. Sales of outsourced compliance testing are anticipated to grow fastest in markets with the most active filing calendars through 2036.
Equipment and Accreditation Costs Slow New Entrants
Building a new accredited testing lab takes time and capital that smaller providers often lack. SGS added an eighth PFAS laboratory and a fifth U.S. Department of Defense certified lab through an acquisition completed in January 2025, not by building new capacity from scratch. Every new accreditation also needs a track record with regulators before clients trust a result. High equipment and accreditation costs may slow new entrants in the early forecast years.
PFAS Rules Expand Testing Scope
Expanding PFAS rules are adding testing categories across major markets. The European Union's universal PFAS restriction, proposed in February 2023 and advanced through an ECHA update in August 2025, continues to broaden cross-sector restrictions under REACH [2]. Australia's AICIS asked registrants on October 14, 2025 to report on 522 PFAS substances imported or manufactured in the country. Laboratories with established PFAS detection capability stand to gain new contracts through 2036.
Which country CAGRs are profiled in the chemical testing services market?
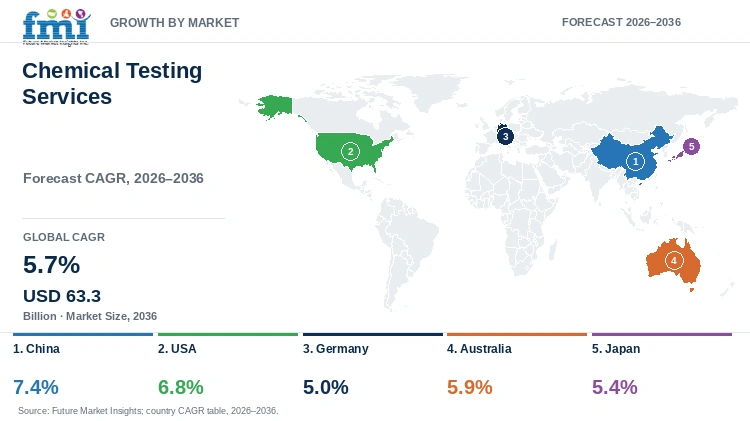
Sales of chemical testing services in China grow fastest among the five profiled countries, at a 7.4% CAGR between 2026 and 2036. Germany posts the slowest rate, a 5.0% CAGR over the same period, as contracting chemical industry output and low capacity use weigh on testing volume. Across all five, manufacturers buy more testing mainly to meet compliance deadlines and to support exports.
Table 6: Country CAGRs and Primary Growth Levers for the Chemical Testing Services Market (CAGR percentage), 2026 to 2036
| Country | CAGR (2026–2036) | Primary Growth Lever |
|---|---|---|
| China | 7.4% | Rising new-substance filing volume under China's chemical substance rules |
| USA | 6.8% | PFAS and toxicology study filings tied to EPA TSCA deadlines |
| Germany | 5.0% | Slowest profiled rate; contracting chemical industry output and low capacity use |
| Australia | 5.9% | AICIS PFAS reporting round adding near-term filing volume |
| Japan | 5.4% | Routine CSCL renewal filings under revised reporting formats |
Source: Future Market Insights
China Chemical Testing Services Market Outlook (2026–2036)
China's Ministry of Ecology and Environment logged 3,264 new chemical record notifications in the first half of 2025, covering 16,619 substances, under a simplified registration route that requires less testing per substance than a full registration, with the figures made public on August 29, 2025 [3]. China is set for the fastest rate among profiled countries, a 7.4% CAGR for 2026 to 2036, as export manufacturers increasingly test to the destination market's own chemical rules rather than relying on the domestic notification route alone. Local laboratory capacity is expanding to meet this export-driven testing load, though demand still outpaces accredited slots during peak filing periods.
Key takeaway: Rising new-substance filing volume will keep Chinese laboratories at near-full accredited capacity.
USA Chemical Testing Services Market Outlook (2026–2036)
The EPA extended the Section 8(d) health and safety study deadline for 16 chemicals, including benzene, styrene and naphthalene, requiring manufacturers to submit already-completed studies for most of them by September 9, 2025 [1]. SGS strengthened the North American PFAS and environmental testing network by acquiring RTI Laboratories in Michigan, a deal announced January 20, 2025. Due to this, U.S. sales of chemical testing services are set for a 6.8% CAGR over 2026 to 2036, led by PFAS testing demand and the SGS capacity expansion.
Key takeaway: PFAS and toxicology study filings tied to EPA deadlines form the main U.S. opening.
Germany Chemical Testing Services Market Outlook (2026–2036)
Germany is projected to add chemical testing services sales at a 5.0% CAGR through 2036, the slowest among profiled countries. Germany's chemical industry output fell about 2.5% in 2025, and VCI forecast a further 1% decline for 2026, with plants running at about 70% of capacity, a historic low. Demand for compliance-focused testing is holding up even as output falls, as manufacturers still need accredited results to keep products on the EU market. Due to this, German buyers are directing testing budgets toward REACH and PFAS compliance work instead of new product development.
Key takeaway: Compliance testing will keep demand steadier than overall German chemical output through 2036.
Australia Chemical Testing Services Market Outlook (2026–2036)
Australia's chemical regulator AICIS asked registrants on October 14, 2025 to report on 522 PFAS substances imported or manufactured in the country, with a response window of 40 working days. Due to this, Australian manufacturers and importers are sending more samples for PFAS identification and volume reporting. Australia is set for a 5.9% CAGR over 2026 to 2036, as the PFAS reporting round adds a fixed near-term filing load on top of routine industrial chemical testing.
Key takeaway: The AICIS PFAS reporting round will add a short-term spike in Australian filing volume.
Japan Chemical Testing Services Market Outlook (2026–2036)
Japan's Ministry of Economy, Trade and Industry revised Chemical Substances Control Law enforcement rules through an October 2024 ordinance, with the update effective April 1, 2025. The revision changed production volume reporting formats across four substance categories. Japanese sales of chemical testing services are set for a 5.4% CAGR from 2026 to 2036, below the global rate, as the country's reporting system is already established and growth tracks routine renewal filings, not a new compliance regime.
Key takeaway: Japanese testing demand will track routine CSCL renewal filings, not a new rule change.
Who are the notable companies in the chemical testing services market?
Intertek Group Plc, Bureau Veritas, SGS SA, Eurofins Scientific, ALS Limited, Element Materials Technology, TÜV NORD AG, UL Solutions, and TÜV Rheinland Group compete across accreditation scope, service portfolio and lab network reach.
Chemical testing providers include global testing, inspection and certification groups and specialised regional laboratories that differ in accreditation scope, service portfolio and lab network reach. Intertek Group Plc, Bureau Veritas, SGS SA and TÜV NORD AG operate broad accredited lab networks across major chemical markets. UL LLC, SAI Global Limited and Aspirata Auditing Testing And Certification (Pty) Ltd supply compliance and certification services alongside testing. SCS Global Services, TÜV Rheinland Group and MISTRAS Group complete the supplier set with specialised and niche testing capability. Leading providers are adding PFAS and environmental testing capacity to gain compliance-driven contracts.
- Global testing, inspection and certification leaders: Intertek Group Plc, Bureau Veritas, SGS SA, Eurofins Scientific, ALS Limited, Element Materials Technology, and TÜV NORD AG operate broad accredited laboratory networks.
- Compliance and certification specialists: UL Solutions supplies certification alongside testing.
- Specialised and regional service providers: TÜV Rheinland Group adds further accredited chemical testing capability.
Competitive Benchmarking: Chemical Testing Services Market
Table 7: Competitive Benchmarking for the Chemical Testing Services Market (qualitative capability ratings), 2026
| Company | Accreditation | Portfolio | Automation | Reach |
|---|---|---|---|---|
| Intertek | High | High | High | High |
| Bureau Veritas | High | High | High | High |
| SGS | High | High | High | High |
| TÜV NORD | High | Medium | Medium | High |
| Eurofins Scientific | High | High | Medium | High |
| ALS Limited | Medium | Medium | Medium | Medium |
| Element Materials Technology | Medium | Low | Low | Low |
| UL Solutions | Medium | Medium | Low | Medium |
| TÜV Rheinland | High | Medium | Medium | High |
This chemical testing services table rates companies High when documentation is broad, Medium when it covers part of the range, and Low when public documentation runs thin. Intertek, Bureau Veritas and SGS are rated on global accredited laboratory networks.
Key Developments in the Chemical Testing Services Market
- In January 2025, SGS SA announced an agreement to acquire RTI Laboratories in Michigan, adding an eighth PFAS laboratory and a fifth laboratory certified by the U.S. Department of Defense.
- In August 2025, ECHA issued an update on the EU's universal PFAS restriction proposal, first put forward in February 2023, signalling continued movement toward a broader cross-sector restriction under REACH and adding to compliance testing obligations for manufacturers and importers [2].[2].
- In August 2025, China's Ministry of Ecology and Environment made public 3,264 new chemical record notifications received in the first half of 2025, covering 16,619 substances [3].
- In October 2025, Australia's AICIS asked registrants to report on 522 PFAS substances imported or manufactured in the country, with a response window of 40 working days.
Key Players in the Chemical Testing Services Market
Global Testing, Inspection and Certification Leaders
- Intertek Group Plc
- Bureau Veritas
- SGS SA
- TÜV NORD AG
Compliance and Certification Specialists
- UL Solutions
- Eurofins Scientific
- ALS Limited
Specialised and Regional Service Providers
- Element Materials Technology
- TÜV Rheinland Group
Chemical Testing Services Market - Report Scope
Table 8: Report Scope for the Chemical Testing Services Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Testing service type; sample type; end use; service delivery mode; sourcing; region |
| Quantitative units | USD billion |
| Market definition | Fees earned from chemical composition analysis, physical and mechanical testing, biodegradability and toxicology testing, microbiological testing, regulatory compliance testing and related laboratory and on-site services performed for manufacturers. In-house testing that a manufacturer performs for internal use only is excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries covered | China; USA; Germany; Australia; Japan |
| Key companies profiled | Intertek Group Plc, Bureau Veritas, SGS SA, Eurofins Scientific, ALS Limited, Element Materials Technology, TÜV NORD AG, UL Solutions, and TÜV Rheinland Group |
| Forecast period | 2026 to 2036 |
| Approach | Sizing reconciles bottom-up and top-down data across laboratory accreditation counts, filing volume under major chemical regulations, provider activity and country compliance conditions, checked against company filings and primary interviews. |
Chemical Testing Services Market - Research Methodology
Table 9: Research Methodology for the Chemical Testing Services Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary research includes interviews with chemical testing providers, accreditation bodies, laboratory managers and manufacturer compliance teams. Interviews cover turnaround time, accreditation scope, PFAS detection limits and service pricing. |
| Desk Research | Desk research draws on provider filings, regulatory announcements, accreditation records, chemical industry statistics and national compliance rules. |
| Market Sizing and Forecasting | Sizing starts from the 2025 market value and adds laboratory accreditation counts, filing volume under major chemical regulations, average service pricing and segment splits in each country. |
| Data Validation | Each estimate is tested against provider disclosures, regulatory filing data and primary interviews. In-house testing that a manufacturer performs for internal use only stays outside market value, so no activity is counted twice. |
Chemical Testing Services Market by Segments
Chemical Testing Services Market segmented by Testing Service Type:
- Chemical composition analysis
- Physical and mechanical testing
- Biodegradability and toxicology testing
- Microbiological testing
- Regulatory compliance testing
Chemical Testing Services Market segmented by Sample Type:
- Polymers and plastics
- Metals and alloys
- Pharmaceuticals and cosmetics
- Food contact materials
Chemical Testing Services Market segmented by End Use:
- Consumer goods
- Pharmaceuticals and healthcare
- Industrial chemicals and petrochemicals
- Food and beverage
Chemical Testing Services Market segmented by Service Delivery Mode:
- Laboratory testing
- On-site testing
- Remote and digital monitoring
- Integrated compliance support
Chemical Testing Services Market segmented by Sourcing:
- Outsourced services
- Hybrid sourcing
- Contract research testing
Chemical Testing Services Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Beveridge & Diamond, P.C. (2025, March). Twelve TSCA Developments to Expect in 2025.https://www.bdlaw.com/publications/twelve-tsca-developments-to-expect-in-2025/
- [2] reuschlaw Legal Consultants. (2025, October 24). REACH and POPs 2025: Key Regulatory Changes.https://www.reuschlaw.de/wp-content/uploads/2025/10/251024-reuschlaw-onepager-reachpop2025-eng.pdf
- [3] ChemLinked. (2025, September 1). China MEE Received 3,264 New Chemical Record Notifications in 2025 H1.https://chemical.chemlinked.com/news/chemical-news/china-mee-received-3264-new-chemical-record-notifications-in-2025-h1
This Report Answers
- What value will chemical testing services sales reach in 2026?
- By 2036, what market value will chemical testing services reach?
- Which testing service type takes the largest share of sales?
- What sample type and end use do manufacturers favour?
- Which profiled countries show the fastest growth in chemical testing services sales?
- Which providers lead the supply of chemical testing services to manufacturers?
Frequently Asked Questions
What is the chemical testing services market worth in 2026?
Chemical testing services sales are valued at USD 36.4 billion in 2026, according to FMI. The market will reach USD 63.30 billion by 2036 as manufacturers submit more samples for regulatory compliance and quality checks.
What CAGR is projected for the chemical testing services market through 2036?
FMI projects a 5.7% CAGR for the chemical testing services market from 2026 to 2036. Expanding regulatory compliance requirements and laboratory outsourcing will support much of this growth.
Which testing service type holds a leading share in 2026?
Chemical composition analysis will hold 21% of testing service type sales in 2026. Manufacturers confirm material content first in most compliance filings.
Which service delivery mode holds a leading share in 2026?
Laboratory testing will account for 68% of service delivery mode sales in 2026. Manufacturers select accredited labs for equipment and methods that a production site cannot run alone.
Which country has a leading growth outlook through 2036?
Key companies include Intertek Group Plc, Bureau Veritas, SGS SA, Eurofins Scientific, ALS Limited, Element Materials Technology, TÜV NORD AG, UL Solutions, and TÜV Rheinland Group.
Who are the key companies in the chemical testing services market?
Key companies include Intertek Group Plc, Bureau Veritas, SGS SA, Eurofins Scientific, ALS Limited, Element Materials Technology, TÜV NORD AG, UL Solutions, and TÜV Rheinland Group.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Testing Service Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Testing Service Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Testing Service Type, 2026 to 2036
- Chemical composition analysis
- Physical and mechanical testing
- Biodegradability and toxicology testing
- Microbiological testing
- Regulatory compliance testing
- Y-o-Y Growth Trend Analysis By Testing Service Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Testing Service Type, 2026 to 2036
- Global Market Analysis and Forecast, By Sample Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sample Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sample Type, 2026 to 2036
- Polymers and plastics
- Metals and alloys
- Pharmaceuticals and cosmetics
- Food contact materials
- Y-o-Y Growth Trend Analysis By Sample Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Sample Type, 2026 to 2036
- Global Market Analysis and Forecast, By End Use, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By End Use, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By End Use, 2026 to 2036
- Consumer goods
- Pharmaceuticals and healthcare
- Industrial chemicals and petrochemicals
- Food and beverage
- Y-o-Y Growth Trend Analysis By End Use, 2021 to 2025
- Absolute $ Opportunity Analysis By End Use, 2026 to 2036
- Global Market Analysis and Forecast, By Service Delivery Mode, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Service Delivery Mode, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Service Delivery Mode, 2026 to 2036
- Laboratory testing
- On-site testing
- Remote and digital monitoring
- Integrated compliance support
- Y-o-Y Growth Trend Analysis By Service Delivery Mode, 2021 to 2025
- Absolute $ Opportunity Analysis By Service Delivery Mode, 2026 to 2036
- Global Market Analysis and Forecast, By Sourcing, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Sourcing, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Sourcing, 2026 to 2036
- Outsourced services
- Hybrid sourcing
- Contract research testing
- Y-o-Y Growth Trend Analysis By Sourcing, 2021 to 2025
- Absolute $ Opportunity Analysis By Sourcing, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- By Country
- Market Attractiveness Analysis
- By Country
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- By Country
- Market Attractiveness Analysis
- By Country
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- By Country
- Market Attractiveness Analysis
- By Country
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- By Country
- Market Attractiveness Analysis
- By Country
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- By Country
- Market Attractiveness Analysis
- By Country
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- By Country
- Market Attractiveness Analysis
- By Country
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- By Country
- Market Attractiveness Analysis
- By Country
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Testing Service Type
- By Sample Type
- By End Use
- By Service Delivery Mode
- By Sourcing
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Intertek
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Bureau Veritas
- SGS
- TÜV NORD
- Eurofins Scientific
- ALS Limited
- Element Materials Technology
- UL Solutions
- TÜV Rheinland
- Intertek Group Plc
- SGS SA
- TÜV NORD AG
- TÜV Rheinland Group
- Intertek
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


