

- Market Size (2026)
- USD 491.2 Bn
- Forecast (2036)
- USD 1175.4 Bn
- CAGR (2026 to 2036)
- 9.1%
How big is Biosimilar and Biologics Market in 2026?
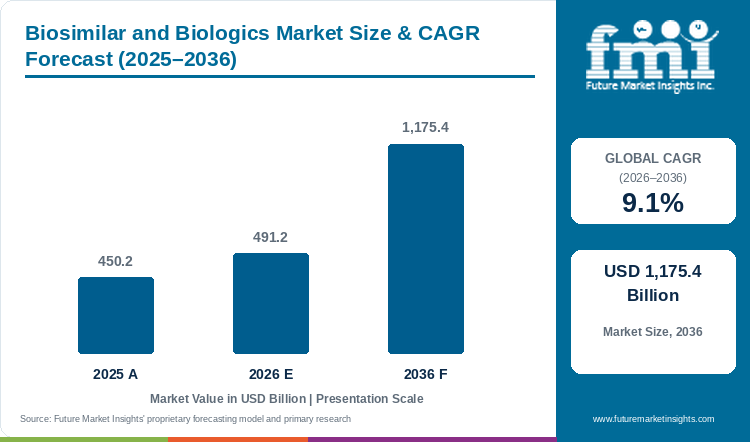
Demand is projected to expand at 9.1% CAGR from 2026 to 2036. Market value rises from USD 450.2 billion in 2025 to USD 491.24 billion in 2026 and USD 1,175.4 billion by 2036.
The biosimilar and biologics market is estimated at USD 491.24 billion in 2026 and projected to reach USD 1,175.4 billion by 2036, at a CAGR of 9.1% from 2026 to 2036. Revenue covers the broad biological-medicine portfolio, including reference products and biosimilars within the same market, while conventional small-molecule chemical medicines are excluded. Antibodies, recombinant proteins, vaccines and cell- or gene-based treatments create different manufacturing and delivery requirements, making the actual medicine central to procurement. Established treatment demand continues alongside biosimilar competition as eligible reference products lose exclusivity, giving purchasers additional authorized options for particular molecules. A biosimilar must demonstrate the required similarity to its reference medicine, so comparative evidence remains specific to the product being evaluated. [1][2] Buyers consider this evidence together with availability, prescribing arrangements and the practical requirements of hospital or outpatient treatment. Cancer contributes a substantial application because specialist biological therapies need reliable supply throughout the care pathway, while manufacturing consistency remains consequential across other disease areas. The commercial outlook therefore connects continuing use of established medicines with qualified competitive entry, supported by production capacity and distribution suited to each treatment setting. [3]
Key Market Trends & Insights
- Biosimilar competition is widening the choice of biological treatments as developers establish comparability and suppliers prepare portfolios around the expiry of eligible reference-product exclusivity. [1]
- Regulatory assessment continues to focus on the evidence supporting similarity, with quality and immunogenicity considerations influencing how development programs are designed. [1][3]
- Health-system uptake depends on prescribing and purchasing arrangements as well as authorization, because European decisions on pharmacy substitution remain with individual member states. [2]
Regional Highlights
- US biosimilar procurement connects the FDA’s product-specific similarity and interchangeability framework with the hospital and specialty channels through which biological medicines reach patients. [1]
- German and French purchasers operate within the European assessment framework, while prescribing, purchasing and pharmacy-substitution arrangements influence local uptake of authorized alternatives. [2]
- The United Kingdom has dedicated MHRA biosimilar licensing guidance, while India’s production and treatment-access requirements make characterization and reliable manufacture central to supplier planning. [3][4]
Market Size & Forecast
Table 1: Market Size and Forecast for Biosimilar and Biologics Market (USD billion and percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 market value | USD 450.2 billion |
| 2026 market value | USD 491.24 billion |
| 2036 market value | USD 1,175.4 billion |
| CAGR 2026 to 2036 | 9.1% |
| Revenue increase 2026 to 2036 | USD 684.16 billion |
| Market expansion 2026 to 2036 | 2.39 times |
Demand through 2036 is expected to reflect both continuing use of reference biologics and the entry of qualified biosimilar alternatives, with the commercial balance differing by molecule and treatment setting. Pharmacovigilance services remain relevant after authorization because product use continues to generate safety information. For manufacturers, the opportunity depends on maintaining reliable supply and an appropriate evidence package, while health-system uptake also requires confidence among prescribers and practical arrangements for treatment delivery and patient support. [1][2][3]
How do comparability and supply conditions shape the market?
Biological medicines require manufacturing and regulatory approaches suited to their complexity, while biosimilar development uses comparison with an already authorized reference product. FDA, EMA and WHO distinguish this assessment from the conventional generic model. The commercial implication is that access depends on a combination of acceptable evidence, reliable production and the purchasing arrangements through which authorized treatments enter routine care. [1][2][3]
Table 2: Industry evidence relevant to the biosimilar and biologics market
| Indicator | Data point or observation | Market relevance | Source |
|---|---|---|---|
| Biosimilarity | FDA requires high similarity and no clinically meaningful differences from the reference product. | Competitive entry rests on comparative evidence. | [1] |
| European substitution | Member states decide whether pharmacy substitution is permitted. | Authorization alone does not determine national uptake. | [2] |
| UK licensing guidance | MHRA guidance updated in February 2025 sets out biosimilar application and comparability requirements. | Developers and suppliers need evidence specific to the UK licensing route. | [4] |
Analyst Perspective
"Producers pairing reliable biologic manufacturing with cost-competitive biosimilars
and strong immunogenicity data will lead as patents expire."- Anurag Sharma, Principal Consultant, FMI
How is the Biosimilar and Biologics Market segmented?
The market is segmented by Drug Class, Application, Manufacturing Type, Drug Classification, Mode of Purchase, Source, Distribution Channel, and Region.
By drug class, the market covers Monoclonal Antibodies, Recombinant Hormones/Proteins, Vaccines, Cellular Based Biologics, Gene-based Biologics, Therapeutic Enzymes and Others. Applications include Infectious Diseases, Cancer, Autoimmune Diseases, Rare Diseases and Others. Manufacturing is divided into Contract Manufacturing and In-house Manufacturing, while drug classification distinguishes Branded Drugs and Generic Drugs. Mode of purchase includes Prescription Drugs and Over-the-Counter Drugs. Source categories are Bacterial Cells, Yeast Cells, Plant Cells, Animal Cells and Other Sources, with Hospital Pharmacies, Retail Pharmacies and Online Pharmacies forming the distribution channels. These classifications describe different dimensions of the same biological-medicine portfolio, including its biosimilar products.
Why do monoclonal antibodies lead demand by drug class?
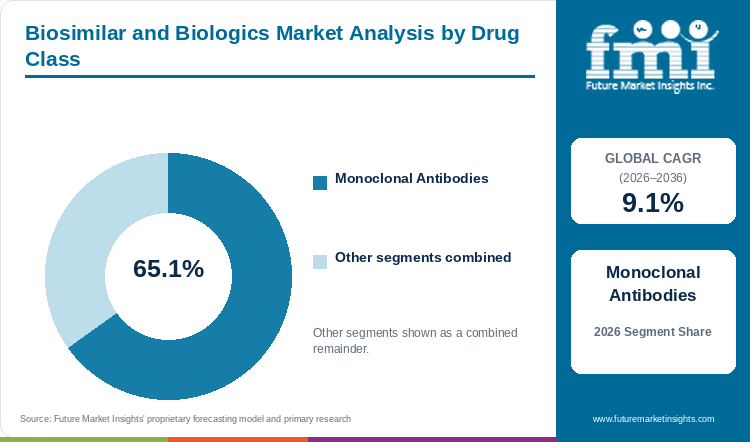
The Monoclonal Antibodies segment is projected to account for 65.1% of drug class demand in 2026.
Table 3: Drug Class Share for Biosimilar and Biologics Market (percentage share), 2026
| Drug Class | Estimated share (2026) |
|---|---|
| Monoclonal Antibodies | 65.1% |
| Other drug classes | 34.9% |
| Total | 100.0% |
Table 4: Segment Position and Market Growth for Biosimilar and Biologics Market, 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 9.1% |
| Profiled drug class segment | Monoclonal Antibodies |
Monoclonal antibodies occupy a leading position because they serve established treatment needs in oncology and immune-mediated disease, bringing reference products and biosimilar competitors into settings with continuing therapeutic demand. The commercial importance of the class does not remove the need for product-specific evidence, since a biosimilar must demonstrate the required relationship to its own reference medicine. [1] Purchasing decisions also depend on how treatment is delivered, the support available to patients and confidence in supply continuity. These considerations make the category relevant across hospital and specialty channels, where a lower acquisition cost is only one part of the decision. Reliable manufacturing and appropriate comparative evidence therefore remain central to competition within this substantial drug class. [3]
- Monoclonal antibodies are projected to represent 65.1% of drug-class demand in 2026, supported by established treatment use in oncology and immune-mediated disease.
- Each monoclonal-antibody biosimilar is evaluated against its reference medicine, with similarity requirements remaining product-specific despite the shared drug-class label. [1]
Why does Cancer hold a substantial share of application demand?
The Cancer segment is projected to account for 32.4% of application demand in 2026.
Table 5: Application Share for Biosimilar and Biologics Market (percentage share), 2026
| Application | Estimated share (2026) |
|---|---|
| Cancer | 32.4% |
| Other applications | 67.6% |
| Total | 100.0% |
Cancer treatment brings biological medicines into specialist pathways where the intended indication, administration setting and continuity of supply influence purchasing. Monoclonal antibodies contribute to that demand through defined products, while an eligible biosimilar provides another authorized option related to its reference medicine. [1][2] The projected application share includes relevant reference and biosimilar product revenue within the biological-medicine total, with conventional chemical anticancer drugs outside this market. Purchasers need to consider product availability alongside the evidence and the arrangements through which a patient receives treatment. [3] Manufacturers can support that requirement through consistent production and appropriate distribution, allowing the selected medicine to remain accessible across a planned course of care as competition develops within individual treatment classes.
- Cancer is projected to account for 32.4% of application demand in 2026, reflecting specialist biological-treatment portfolios and the continuing supply requirements of oncology care.
- A cancer biosimilar is assessed against its own reference medicine, with its treatment role and purchasing conditions remaining specific to the authorized product. [1][2]
What are the drivers, restraints, and opportunities in the Biosimilar and Biologics Market?
The opening created by eligible reference-product expiry becomes commercially useful when a developer can deliver a consistent authorized medicine through the channels that patients and prescribers already use. Comparative evidence, manufacturing continuity and national purchasing conditions consequently need to be considered together, since regulatory authorization establishes an essential product basis while treatment uptake still depends on reliable access. [1][2][3]
Driver
Established use of monoclonal antibodies in oncology and immune-mediated disease creates a continuing treatment base within the biological-medicine portfolio. As eligible reference products lose exclusivity, qualified biosimilar entry can broaden the options available to purchasers who need authorized alternatives with appropriate comparative evidence. [1][2] Suppliers addressing this demand need to maintain manufacturing consistency and dependable availability, allowing a product to fit the prescribing and purchasing arrangements through which patients receive treatment in each health system. [2][3]
Restraint
Complex manufacturing and the need to demonstrate similarity create development requirements that differ from those of conventional small-molecule generics. [1][3] Even after authorization, uptake can be influenced by prescribing habits, reimbursement and the conditions under which substitution is permitted. EMA explicitly leaves pharmacy-substitution decisions to member states. [2] Suppliers therefore face both technical and commercial barriers, because an acceptable evidence package must be followed by reliable production and practical access to the channels through which patients receive treatment.
Opportunity
Biologics contract manufacturing can provide an additional production route when developers organize capacity around a specific product and its quality requirements, linking commercial expansion with manufacturing readiness. [3] The opportunity is to align this capacity with comparative evidence and treatment-channel support before an authorized option reaches routine use. Suppliers able to maintain availability and explain the relevant product evidence can help health systems make practical use of additional biological-medicine choices within their own purchasing and prescribing arrangements. [1][2]
Which country CAGRs are profiled in the Biosimilar and Biologics Market?
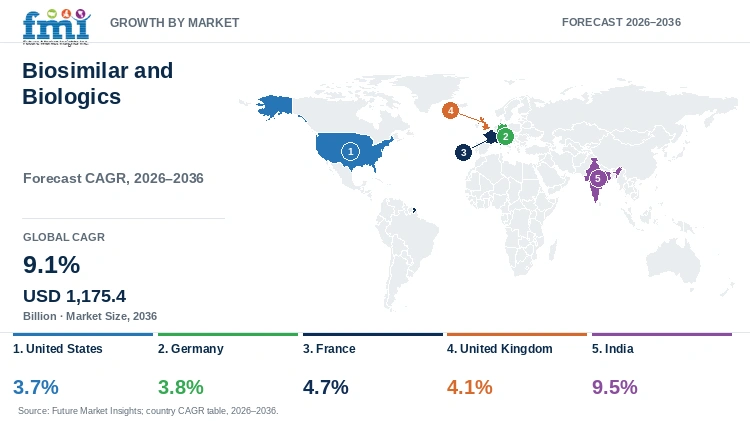
Table 6: Country CAGR Comparison for Biosimilar and Biologics Market (CAGR percentage), 2026 to 2036
| Country | CAGR | Forecast period |
|---|---|---|
| United States | 3.7% | 2026 to 2036 |
| Germany | 3.8% | 2026 to 2036 |
| France | 4.7% | 2026 to 2036 |
| United Kingdom | 4.1% | 2026 to 2036 |
| India | 9.5% | 2026 to 2036 |
Country-wise Analysis
United States Biosimilar and Biologics Market Outlook (2026 to 2036)
US purchasers encounter reference biological medicines and biosimilars through several treatment channels, with the FDA’s distinction between biosimilarity and interchangeability affecting how an alternative is described. Biosimilars meet the required similarity standard, while interchangeability is a separate regulatory status rather than a higher standard of treatment quality. [1] The broad US biological-medicine market is projected to grow at 3.7% CAGR from 2026 to 2036. Hospital-administered therapies and medicines used outside the hospital create different distribution and patient-support requirements, so a procurement decision needs to follow the actual product and care setting. Manufacturers can strengthen access through dependable production and clear product information, particularly when several authorized options relate to the same reference medicine and treatment must continue across successive purchasing periods.
Germany Biosimilar and Biologics Market Outlook (2026 to 2036)
Germany combines an established pharmaceutical manufacturing base with specialist demand for biological treatment, making analytical capability and supply continuity consequential within procurement. Under the European framework, a biosimilar is evaluated against the relevant reference medicine, while member states retain responsibility for pharmacy-substitution decisions. [2] German demand is projected to expand at 3.8% CAGR from 2026 to 2036 across the broad biological-medicine portfolio. Purchasers assessing competing products need to relate authorization and product evidence to the indication and administration requirements of their existing care pathways. A manufacturer’s ability to characterize and consistently supply a medicine therefore supports its commercial position, with clinical information and a workable delivery arrangement helping an authorized alternative become a sustainable purchasing option.
France Biosimilar and Biologics Market Outlook (2026 to 2036)
French oncology centers and other specialist services need biological-medicine supplies that remain available throughout a planned course of care, giving the treatment pathway a direct role in procurement. An additional biosimilar option changes the available purchasing choice for a particular reference medicine, while the therapeutic indication and administration requirements continue to define the product needed. EMA’s framework establishes the scientific assessment of similarity, with national arrangements influencing subsequent uptake. [2] The broad French market is projected at 4.7% CAGR from 2026 to 2036. Suppliers consequently need to connect the authorized portfolio with dependable delivery and usable product information, allowing hospital and outpatient purchasing teams to assess continuity alongside the comparative evidence relevant to the medicine.
United Kingdom Biosimilar and Biologics Market Outlook (2026 to 2036)
The MHRA’s biosimilar licensing guidance, updated in February 2025, gives UK developers a specific resource covering reference products, comparability, labeling and related application requirements. [4] Procurement follows that product-specific evidence into the treatment setting, where an authorized biological medicine needs a dependable supply route and information appropriate to its intended use. The broad UK biological-medicine market is projected to expand at 4.1% CAGR from 2026 to 2036. For suppliers preparing a biosimilar portfolio, manufacturing readiness and the reference product used in development are practical considerations before routine supply begins. Buyers then assess how the proposed option fits existing prescribing and administration arrangements, with support for continuing access carrying commercial significance alongside authorization and portfolio breadth.
India Biosimilar and Biologics Market Outlook (2026 to 2036)
India’s biological-medicine opportunity connects manufacturing capability with the practical task of extending access to established treatments, including authorized biosimilar alternatives. A production program needs suitable characterization and consistent processes for the particular biological product, with WHO’s evaluation principles explaining why similarity must be established against a reference medicine. [3] The broad Indian market is projected to grow at 9.5% CAGR from 2026 to 2036. Purchasing spans medicines with different administration and distribution requirements, so additional capacity becomes useful when it supplies the product needed by the care setting. Manufacturers can strengthen their position through dependable availability and product-specific evidence, linking production scale with the hospital, pharmacy and patient-support arrangements through which biological treatment becomes accessible.
Who are the notable companies in the Biosimilar and Biologics Market?
Pfizer Inc.; Hoffmann-La Roche AG; AbbVie Inc.; Amgen Inc.; Biocon Limited
Reference-product companies and biosimilar developers compete through portfolios that can differ by molecule, therapeutic setting and market access, with several participants active across both roles. Established biologics portfolios create a continuing supply requirement, while biosimilar entry introduces an additional authorized option for selected reference medicines. Purchasers can compare relevant product availability and manufacturing consistency alongside the comparative evidence, then consider how the supplier supports the hospital or specialty channel through which the treatment will be delivered. [1][2][3]
Competitive Benchmarking: Biosimilar and Biologics Market
Table 7: Competitive positioning for the biosimilar and biologics market
| Company | Positioning | Commercial distinction |
|---|---|---|
| Pfizer Inc. | Reference biologic and biosimilar portfolios | Participates across biological treatments and biosimilar competition. |
| Hoffmann-La Roche AG | Biological medicines | Supplies biological treatment portfolios across major therapeutic areas. |
| AbbVie Inc. | Immunology and other biological treatments | Competes through established biological-medicine franchises. |
| Amgen Inc. | Biotechnology medicines and biosimilars | Combines biological product development with biosimilar participation. |
| Biocon Limited | Biological and biosimilar development | Addresses access to biological therapies through biosimilar capabilities. |
Key Developments in the Biosimilar and Biologics Market
- The MHRA updated its biosimilar licensing guidance in February 2025, providing a UK resource on reference-product selection, comparability and application requirements. [4]
- WHO’s 2022 evaluation guidelines set out internationally applicable principles for licensing biosimilars, maintaining a focus on demonstrated similarity and the relationship to the reference biological product. [3]
- EMA’s current biosimilar overview distinguishes the scientific assessment of interchangeability from pharmacy-substitution decisions, which continue to be made by individual European Union member states. [2]
Key Players in the Biosimilar and Biologics Market
Reference biologic and biosimilar portfolios
- Pfizer Inc.
Biological medicines
- Hoffmann-La Roche AG
Immunology and other biological treatments
- AbbVie Inc.
Biotechnology medicines and biosimilars
- Amgen Inc.
Biological and biosimilar development
- Biocon Limited
Biosimilar and Biologics Market - Report Scope
Table 8: Report Scope for Biosimilar and Biologics Market, 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market | Biosimilar and Biologics Market |
| Revenue coverage | Biological medicines, including reference products and biosimilars within one market; conventional small-molecule chemical medicines excluded. |
| Historical reference year | 2025 |
| Base year | 2026 |
| Forecast period | 2026 to 2036 |
| Quantitative units | USD billion and percentage shares/CAGRs |
| 2026 market value | USD 491.24 billion |
| 2036 market value | USD 1,175.4 billion |
| Forecast CAGR | 9.1% from 2026 to 2036 |
| Segmentation | Drug Class, Application, Manufacturing Type, Drug Classification, Mode of Purchase, Source, Distribution Channel |
| Country profiles | United States, Germany, France, United Kingdom, India |
Biosimilar and Biologics Market - Research Methodology
Table 9: Research Methodology for Biosimilar and Biologics Market, 2026 edition
| Method | Approach |
|---|---|
| Market definition | Reference biological medicines and biosimilars are included within one biological-medicine revenue total; conventional small-molecule chemical medicines are excluded. |
| Secondary research | FMI market coverage is assessed alongside official technical guidance, regulatory material and relevant first-party disclosures. |
| Segmentation | Demand is organized by the stated category axes, retaining the distinction between segment shares and growth rates. |
| Country assessment | Local care pathways, purchasing conditions and service availability inform the interpretation of each geographic outlook. |
| Competitive assessment | Participants are compared by relevant offering, customer setting and delivery capability rather than unsupported company rankings. |
| Consistency review | Market values, forecast periods, units, segment labels and country growth rates are checked for agreement throughout the analysis. |
Biosimilar and Biologics Market by Segments
Biosimilar and Biologics Market segmented by Drug Class:
- Monoclonal Antibodies
- Recombinant Hormones/Proteins
- Vaccines
- Cellular Based Biologics
- Gene-based Biologics
- Therapeutic Enzymes
- Others
Biosimilar and Biologics Market segmented by Application:
- Infectious Diseases
- Cancer
- Autoimmune Diseases
- Rare Diseases
- Others
Biosimilar and Biologics Market segmented by Manufacturing Type:
- Contract Manufacturing
- In-house Manufacturing
Biosimilar and Biologics Market segmented by Drug Classification:
- Branded Drugs
- Generic Drugs
Biosimilar and Biologics Market segmented by Mode of Purchase:
- Prescription Drugs
- Over-the-Counter Drugs
Biosimilar and Biologics Market segmented by Source:
- Bacterial Cells
- Yeast Cells
- Plant Cells
- Animal Cells
- Other Sources
Biosimilar and Biologics Market segmented by Distribution Channel:
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
Biosimilar and Biologics Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] US Food and Drug Administration. Accessed 15 October 2026. Biosimilars Basics for Patients
- [2] European Medicines Agency. Accessed 15 October 2026. Biosimilar medicines: overview
- [3] World Health Organization. Accessed 15 October 2026. Guidelines on evaluation of biosimilars
- [4] UK Medicines and Healthcare products Regulatory Agency. Accessed 15 October 2026. Guidance on the licensing of biosimilar products
This Report Answers
- How big is the biosimilar and biologics market in 2026?
- What is the market outlook through 2036?
- Which segments lead demand in 2026?
- Which countries are examined in the forecast?
- Which companies participate in the market?
Frequently Asked Questions
How big is the biosimilar and biologics market in 2026?
The market is estimated at USD 491.24 billion in 2026, compared with USD 450.2 billion in 2025.
What is the market outlook through 2036?
Market value is projected to reach USD 1,175.4 billion by 2036, with a CAGR of 9.1% from 2026 to 2036.
Which segments lead demand in 2026?
Monoclonal Antibodies are projected to hold 65.1% of drug-class demand in 2026, while Cancer accounts for 32.4% by application.
Which countries are examined in the forecast?
The country analysis covers United States, Germany, France, United Kingdom and India, with projected growth from 2026 to 2036.
Which companies participate in the market?
Relevant participants include Pfizer Inc., Hoffmann-La Roche AG, AbbVie Inc., Amgen Inc., Biocon Limited, whose portfolios serve different requirements within the market.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Drug Class, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Drug Class, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Drug Class, 2026 to 2036
- Monoclonal Antibodies
- Recombinant Hormones/Proteins
- Vaccines
- Cellular Based Biologics
- Gene-based Biologics
- Therapeutic Enzymes
- Others
- Y-o-Y Growth Trend Analysis By Drug Class, 2021 to 2025
- Absolute $ Opportunity Analysis By Drug Class, 2026 to 2036
- Global Market Analysis and Forecast, By Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Application, 2026 to 2036
- Infectious Diseases
- Cancer
- Autoimmune Diseases
- Rare Diseases
- Others
- Y-o-Y Growth Trend Analysis By Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Application, 2026 to 2036
- Global Market Analysis and Forecast, By Manufacturing Type, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Manufacturing Type, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Manufacturing Type, 2026 to 2036
- Contract Manufacturing
- In-house Manufacturing
- Y-o-Y Growth Trend Analysis By Manufacturing Type, 2021 to 2025
- Absolute $ Opportunity Analysis By Manufacturing Type, 2026 to 2036
- Global Market Analysis and Forecast, By Drug Classification, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Drug Classification, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Drug Classification, 2026 to 2036
- Branded Drugs
- Generic Drugs
- Y-o-Y Growth Trend Analysis By Drug Classification, 2021 to 2025
- Absolute $ Opportunity Analysis By Drug Classification, 2026 to 2036
- Global Market Analysis and Forecast, By Mode of Purchase, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Mode of Purchase, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Mode of Purchase, 2026 to 2036
- Prescription Drugs
- Over-the-Counter Drugs
- Y-o-Y Growth Trend Analysis By Mode of Purchase, 2021 to 2025
- Absolute $ Opportunity Analysis By Mode of Purchase, 2026 to 2036
- Global Market Analysis and Forecast, By Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Source, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Source, 2026 to 2036
- Bacterial Cells
- Yeast Cells
- Plant Cells
- Animal Cells
- Other Sources
- Y-o-Y Growth Trend Analysis By Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Source, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East & Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Chile
- Rest of Latin America
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- UK
- Italy
- Spain
- France
- Nordic
- BENELUX
- Rest of Western Europe
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Russia
- Poland
- Hungary
- Balkan & Baltic
- Rest of Eastern Europe
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia & New Zealand
- Rest of South Asia and Pacific
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Key Takeaways
- Middle East & Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Kingdom of Saudi Arabia
- Other GCC Countries
- Türkiye
- South Africa
- Other African Union
- Rest of Middle East & Africa
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Australia & New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Russia
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Kingdom of Saudi Arabia
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Drug Class
- By Application
- By Manufacturing Type
- By Drug Classification
- By Mode of Purchase
- By Source
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Pfizer Inc.
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Hoffmann-La Roche AG
- AbbVie Inc.
- Amgen Inc.
- Biocon Limited
- Pfizer Inc.
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


