

- Market Size (2026)
- USD 18.2 Bn
- Forecast (2036)
- USD 79.6 Bn
- CAGR (2026 to 2036)
- 15.9%
How big is the AI in Fintech market in 2026?
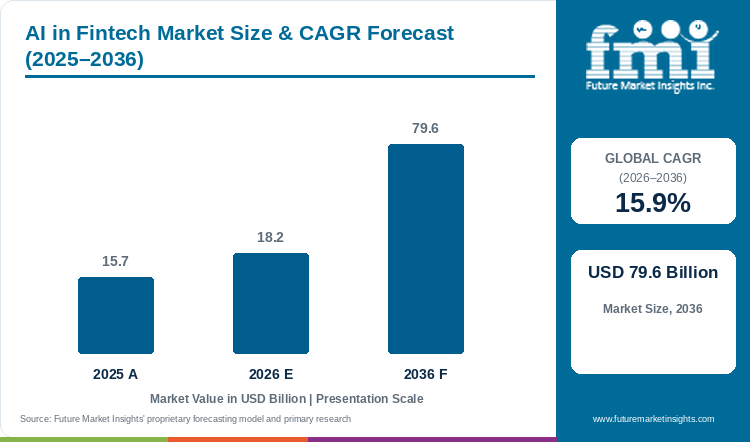
Demand is projected to expand at 15.9% CAGR from 2026 to 2036. Market value rises from USD 15.7 billion in 2025 to USD 18.2 billion in 2026 and USD 79.58 billion by 2036. [1]
FMI values the AI in Fintech market at USD 18.2 billion in 2026 compared with an estimated USD 15.7 billion in 2025, with sales forecast to reach USD 79.58 billion by 2036, growing at a 15.9% CAGR. [1] Software represents 61.6% of solution demand and digital payments holds 23.9% by fintech domain in 2026, linking financial AI purchasing with continuing application and decision-support work. [1] The EBA and ECB reported EUR 4.2 billion of EEA payment fraud in 2024 and described increasing manipulation of payers, identifying patterns relevant to institutions assessing payment controls. [2] The FSB’s financial-AI analysis identifies model risk and third-party dependencies, giving buyers a reason to examine the service, data and providers supporting their deployed applications. [3] Fraud and risk models need representative transaction records because performance measured on another customer population may not transfer to the payment or lending decisions of the purchasing institution. Operational assessment should consider loss outcomes alongside interruptions to legitimate customers, with uncertain cases directed into an escalation process rather than treated as automatically fraudulent transactions. Software also supports customer interactions and financial analytics, making traceable version changes and clear review responsibilities relevant as institutions introduce models into several connected workflows. Through 2036, FMI expects commercial qualification to follow measured performance within a defined population and dependable monitoring after launch, as buyers examine how changing transaction patterns affect the relationship between model behavior and the service delivered to customers.
Key Market Trends and Insights
- Software accounts for 61.6% of solution demand in 2026, reflecting its role in supporting recurring financial decisions and customer workflows within the AI in Fintech market. [1]
- Digital payments holds 23.9% of fintech domain demand in 2026, reflecting the need for timely transaction decisions and continuing assessment of fraud and customer treatment. [1]
- FSB identifies model risk and third-party dependencies in financial AI, making the services and data supporting an application relevant to its assessment within the institution’s decision workflow. [3]
Regional Highlights
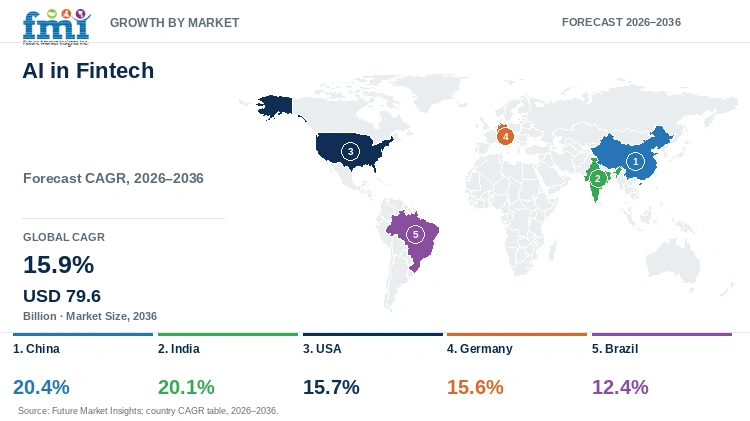
- Fastest-growing profiled market: China at 20.4% CAGR from 2026 to 2036. [1]
- Local fraud patterns need representative test data rather than one imported benchmark.
Market Size and Forecast
Table 1: Market size and forecast for the AI in Fintech market in USD billion and percentage
| Metric | Value |
|---|---|
| 2025 market size | USD 15.7 billion |
| Estimated market size in 2026 | USD 18.2 billion |
| Projected market size by 2036 | USD 79.58 billion |
| CAGR 2026 to 2036 | 15.9% |
| Added revenue 2026 to 2036 | USD 61.38 billion |
| Market expansion multiple | 4.4x |
QR code payment is one transaction route within digital payments. Fraud models need representative records and ongoing monitoring, with uncertain cases directed to a review process as customer behavior changes.
Payment Fraud and Financial-AI Evidence
Payment-fraud records describe losses and fraud patterns within the EEA. Financial-AI analysis also examines model and third-party dependencies. [2][3]
Table 2: Evidence and adoption indicators for the AI in Fintech market
| Indicator | Data point or finding | Commercial relevance | Source |
|---|---|---|---|
| EEA fraud value | EUR 4.2 billion in 2024 | Defines a concrete payment-control problem | [2] |
| EEA value rate | Around 0.002% of transaction value | Different denominator from event counts | [2] |
| Fraud methods | Payer manipulation is increasing | Requires evaluation beyond established patterns | [2] |
| FSB analysis | Model risk and third-party dependence | Informs qualification and monitoring | [3] |
Analyst Perspective
"Financial institutions need to understand how a model behaves within the decisions they actually make, including the cases that interrupt legitimate customers. A useful comparison connects loss outcomes with review workload and a clear escalation route. Providers should also make model changes and dependencies traceable, because monitoring after launch helps the institution assess whether new transaction patterns are changing performance within the customer population the service was designed to support."
- Sudip Saha, Principal Consultant, FMI
How is the AI in Fintech market segmented?
The market covers 4 commercial axes and region: solution; fintech domain; application; end user.
By solution: Software; Services. By fintech domain: Digital payments; Digital banking; Digital lending; Investments; Insurtech; Embedded finance; Crypto and blockchain. By application: Fraud intelligence; Financial analytics; Virtual assistants; Risk assessment; Robo-advice; Claims processing; Other uses. By end user: Banks; Fintech providers; Insurers; Payment companies; Investment firms; RegTech providers; Other users.
Why does software lead demand within the solution category?
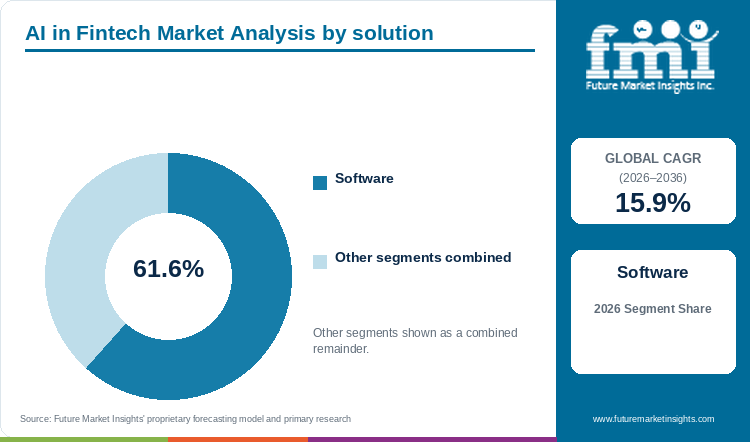
The software segment accounts for 61.6% of solution demand in 2026. [1]
Software leads solution demand because financial institutions use applications to support several decisions within continuing workflows, including fraud assessment, risk evaluation and customer interactions. The operating value depends on the records supplied and the way model changes are reviewed, making traceability relevant beyond the initial installation. Embedded lending adds a lending decision within another service, where version control and clear responsibilities help the institution follow the model being used. The segment’s position therefore reflects repeat application work, with monitoring and suitable escalation needed as the financial process and customer behavior change.
- Software accounts for 61.6% of solution demand in 2026, reflecting its role in supporting recurring financial decisions and customer workflows within the AI in Fintech market. [1]
- Institutions should connect deployed software with traceable model versions and a practical review route, allowing teams to examine how changes affect the financial decisions delivered through the application.
Table 3: Leading solution share for the AI in Fintech market
| Solution | Share in 2026 |
|---|---|
| Software | 61.6% |
| Other segments combined | 38.4% |
| Total | 100.0% |
Table 4: Segment leadership and market growth for the AI in Fintech market
| Metric | Value |
|---|---|
| Global CAGR 2026 to 2036 | 15.9% |
| Leading segment | Software |
Why do digital payments lead demand within the fintech domain category?
The digital payments segment accounts for 23.9% of fintech domain demand in 2026. [1]
Digital payments leads domain demand because providers need timely decisions while managing fraud exposure and the treatment of legitimate customers within the same transaction workflow. The EBA-ECB findings describe varied fraud patterns and increasing manipulation of payers, giving institutions a reason to evaluate controls against representative payment records. Anti-money laundering systems address related monitoring obligations, although fraud assessment retains its own decision and escalation requirements. The leading share therefore reflects the continuing work associated with payment decisions, with speed assessed alongside loss outcomes, customer friction and review capacity. [2]
- Digital payments holds 23.9% of fintech domain demand in 2026, reflecting the need for timely transaction decisions and continuing assessment of fraud and customer treatment. [1]
- Payment providers should evaluate fraud outcomes alongside false positives and review workload, using representative transaction cases and an escalation process for uncertainty as customer behavior and fraud patterns change. [2]
What are the drivers restraints and opportunities in the AI in Fintech market?
- Changing fraud patterns support repeated decision-support work because institutions need to assess new methods while preserving usable payment services, making ongoing evaluation and monitoring relevant beyond the initial purchase of a financial AI model. [2]
- Model risk and third-party dependencies complicate deployment because institutions rely on external services and data as well as application behavior, requiring buyers to understand those dependencies within the controlled financial decision process they operate. [3]
- Measured review creates an opportunity to improve model qualification through representative workflow tests, clear escalation and traceable version records, allowing buyers to compare operational performance within a defined population and monitor uncertain cases after launch.
Changing fraud creates repeated decision-support work
EBA-ECB findings describe higher payment-fraud value and changing methods, supporting continuing model evaluation as institutions assess new patterns and preserve usable services for legitimate customers. [2]
Model and third-party dependencies complicate deployment
FSB identifies model risk and third-party dependencies in financial AI, giving institutions a reason to examine the services and data supporting their applications when assessing deployment within a controlled decision process. [3]
Measured review can improve model qualification
Representative workflow tests, post-launch monitoring and clear version records give institutions a basis for model qualification. RegTech software connects financial technology with compliance processes, where review needs to consider loss outcomes alongside interruptions to legitimate customers.
Which country CAGRs are profiled in the AI in Fintech market?
Table 5: Country CAGR comparison for the AI in Fintech market
| Country | CAGR 2026 to 2036 |
|---|---|
| China | 20.4% |
| India | 20.1% |
| USA | 15.7% |
| Germany | 15.6% |
| Brazil | 12.4% |
Country-wise Analysis
China
A financial institution deploying an AI model in China needs customer and transaction records that reflect the activity the model will encounter after launch. A pattern that distinguishes an unusual payment in one customer group may be ordinary in another, so local testing helps the institution judge both missed fraud and unnecessary interruptions. Those requirements for locally useful financial decisions accompany a country market projected to expand at a 20.4% CAGR from 2026 to 2036. [1] Deployment also changes the work of the review team, whose staff need to understand which cases require attention and how their decisions feed back into monitoring. Institutions can gain more useful capacity when software fits that operating process, while continuing tests of new transaction patterns provide a basis for deciding whether a model remains suitable as customer behavior changes.
India
Fast payment decisions leave little room for a financial service to interrupt routine Indian transactions without a clear reason. An AI application therefore has to balance the detection of suspicious activity with the cost of treating an ordinary customer as a risk, giving manageable false positives a direct role in the purchasing decision. Uncertain cases need an escalation route that staff can use within the available time, while model tests should include the transactions and customer groups the institution actually serves. Against those requirements for timely decisions and manageable review, the Indian market is forecast to expand at a 20.1% CAGR from 2026 to 2036. [1] Suppliers can support adoption through monitoring that reveals changes after deployment and a clear connection between an alert, the evidence behind it and the action available to the institution's review team.
USA
US institutions evaluating AI for lending or payments can begin with the decisions their own staff already review, comparing the proposed model against labelled examples from that application. A lending assessment and a payment alert involve different evidence and consequences, making the intended use important when judging performance. The Financial Stability Board's AI analysis identifies model risk and data quality among the issues relevant to wider financial adoption. [3] FMI projects a 15.7% CAGR for the USA market from 2026 to 2036, with financial institutions evaluating applications against their own decision and control requirements. [1] A supplier's commercial offer becomes more useful when it explains how outputs can be reviewed and monitored after deployment, allowing the institution to organize staff responsibilities around the application. Repeat purchasing then depends on whether those controls remain practical as the model encounters new customers and changed transaction patterns.
Germany
Payment fraud measured by lost value can present a different operating problem from fraud measured by the number of events. The EBA and ECB's joint report analyzes those measures across EU and EEA payment instruments, providing a regional context relevant to German institutions without describing a Germany-only total. [2] Buyers can use that distinction when deciding which cases an AI system should prioritize and what a reduction in alerts would mean for financial losses. Those payment-control questions provide context for a German market forecast to expand at a 15.6% CAGR from 2026 to 2036. [1] Model qualification also needs to examine the institution's own transactions, because the consequence of missing one high-value transfer differs from interrupting many routine purchases. Connecting tests with the review team's actual decisions gives the software purchase a clearer relationship with the problem it is intended to address.
Brazil
For a fintech provider serving Brazilian customers, local transaction records give model testing a closer connection with the payment activity encountered in use. Customer channels and merchant patterns can change after deployment, so an assessment based on older records needs continuing checks against new transactions. As providers assess applications against changing local transaction records, the Brazilian market is projected to expand at a 12.4% CAGR from 2026 to 2036. [1] A provider can examine how often alerts lead to a useful intervention and whether ordinary payments are being delayed, allowing the review process to guide changes in the application. Customer-facing tools also benefit from language and explanations that the intended audience can use, especially when a decision affects access to a financial service. Suppliers gain a stronger basis for renewal when these operating details remain manageable as transaction volumes and the customer mix develop.
Who are the notable companies in the AI in Fintech market?
IBM; AWS; Microsoft; Google; NVIDIA
Competitive Benchmarking
Table 6: Competitive positioning for the AI in Fintech market
| Company or institution | Positioning | Evidence or purchasing distinction |
|---|---|---|
| IBM | Financial AI applications and platforms | Application and integration position [1] |
| AWS | Cloud AI services | Infrastructure and model-service position [1] |
| Microsoft | Cloud and enterprise AI | Platform and workflow support [1] |
| Cloud AI services for financial institutions | Google Cloud documents financial-services AI solutions supporting operations and risk management. [4] | |
| NVIDIA | AI computing and software for financial services | Documents AI platform use cases including fraud detection and customer experience. [5] |
Key Developments in the AI in Fintech Market
- EBA and ECB released their joint payment-fraud report in December 2025, reporting EUR 4.2 billion of EEA fraud in 2024 and describing changing methods, including increasing payer manipulation, relevant to the assessment of payment controls. [2]
- The FSB published its financial-AI stability analysis in November 2024, identifying vulnerabilities including model risk and third-party dependencies that institutions need to consider when examining the services and data supporting deployed financial applications. [3]
Key Players in the AI in Fintech Market
IBM; AWS; Microsoft; Google; Salesforce; Oracle; NVIDIA; Affirm.
AI in Fintech Market Report Scope
Table 7: Report coverage for the AI in Fintech market
| Coverage field | Report scope |
|---|---|
| Market breakdown | Solution; Fintech domain; Application; End user; region |
| Quantitative units | USD billion |
| Market definition | AI software and attributable services for financial technology applications. General compute is counted only where attributable to the defined offer. Financial assets and transaction principal are excluded. |
| Regions covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries profiled | China; India; USA; Germany; Brazil |
| Key companies profiled | IBM; AWS; Microsoft; Google; Salesforce; Oracle; NVIDIA; Affirm |
| Forecast period | 2026 to 2036 |
AI in Fintech Market Research Methodology
Table 8: Research methods for the AI in Fintech market
| Method | Approach |
|---|---|
| Market coverage | Financial AI software and services by fintech domain, application and end user within the controlled decisions delivered by financial institutions. |
| Public industry evidence | EBA-ECB payment-fraud evidence, FSB financial-AI analysis and official platform disclosures. |
| Operating and technical context | Changing fraud patterns, model risks and third-party dependencies. |
| Product and service assessment | Representative transaction records, loss outcomes, false positives, escalation and traceable model changes. |
| Supplier research | Official company disclosures establish documented products, services and participation roles. |
| Country and segment analysis | Examine local operating conditions and the purchasing requirements of each market category. |
| Interpretation of industry indicators | Fraud value from event frequency and general model capability from application performance within a defined customer population, with post-deployment monitoring informing interpretation of changing transaction behavior. |
AI in Fintech Market by Segments
By solution
- Software
- Services
By fintech domain
- Digital payments
- Digital banking
- Digital lending
- Investments
- Insurtech
- Embedded finance
- Crypto and blockchain
By application
- Fraud intelligence
- Financial analytics
- Virtual assistants
- Risk assessment
- Robo-advice
- Claims processing
- Other uses
By end user
- Banks
- Fintech providers
- Insurers
- Payment companies
- Investment firms
- RegTech providers
- Other users
AI in Fintech Market by Region
- North America
- USA
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- UK
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Future Market Insights. Published outlook accessed 12 October 2026. AI in Fintech Market.
- [2] European Banking Authority and European Central Bank. 15 December 2025. Joint report on payment fraud.
- [3] Financial Stability Board. 14 November 2024. The Financial Stability Implications of Artificial Intelligence.
- [4] Google. Financial services. Accessed 13 October 2026.
- [5] NVIDIA. AI Solutions for Finance Industries. Accessed 13 October 2026.
This Report Answers
- How big is the AI in Fintech market in 2026?
- What market value is projected by 2036?
- Which solution segment leads demand?
- Which other commercial categories shape the market?
- Which countries have the fastest profiled growth?
- Which companies and institutions participate in the market?
Frequently Asked Questions
How large is the AI in Fintech market in 2026?
FMI estimates market value at USD 18.2 billion in 2026, compared with an estimated USD 15.7 billion in 2025. [1]
What value and CAGR are projected through 2036?
Market value is projected to reach USD 79.58 billion by 2036 at a 15.9% CAGR from 2026 to 2036. [1]
Which solution segment leads in 2026?
Software accounts for 61.6% of this category. [1]
What is the report segmentation?
Solution; Fintech domain; Application; End user, and region.
Which profiled market records the highest CAGR?
China has the highest profiled rate at 20.4% from 2026 to 2036. [1]
Who are the key participants?
IBM; AWS; Microsoft; Google; Salesforce; Oracle; NVIDIA; Affirm.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By solution, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By solution, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By solution, 2026 to 2036
- Software
- Services
- Y-o-Y Growth Trend Analysis By solution, 2021 to 2025
- Absolute $ Opportunity Analysis By solution, 2026 to 2036
- Global Market Analysis and Forecast, By fintech domain, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By fintech domain, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By fintech domain, 2026 to 2036
- Digital payments
- Digital banking
- Digital lending
- Investments
- Insurtech
- Embedded finance
- Crypto and blockchain
- Y-o-Y Growth Trend Analysis By fintech domain, 2021 to 2025
- Absolute $ Opportunity Analysis By fintech domain, 2026 to 2036
- Global Market Analysis and Forecast, By application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By application, 2026 to 2036
- Fraud intelligence
- Financial analytics
- Virtual assistants
- Risk assessment
- Robo-advice
- Claims processing
- Other uses
- Y-o-Y Growth Trend Analysis By application, 2021 to 2025
- Absolute $ Opportunity Analysis By application, 2026 to 2036
- Global Market Analysis and Forecast, By end user, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By end user, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By end user, 2026 to 2036
- Banks
- Fintech providers
- Insurers
- Payment companies
- Investment firms
- RegTech providers
- Other users
- Y-o-Y Growth Trend Analysis By end user, 2021 to 2025
- Absolute $ Opportunity Analysis By end user, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- USA
- Canada
- By solution
- By fintech domain
- By application
- By end user
- By Country
- Market Attractiveness Analysis
- By Country
- By solution
- By fintech domain
- By application
- By end user
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By solution
- By fintech domain
- By application
- By end user
- By Country
- Market Attractiveness Analysis
- By Country
- By solution
- By fintech domain
- By application
- By end user
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- UK
- Italy
- Spain
- Benelux
- Nordics
- By solution
- By fintech domain
- By application
- By end user
- By Country
- Market Attractiveness Analysis
- By Country
- By solution
- By fintech domain
- By application
- By end user
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By solution
- By fintech domain
- By application
- By end user
- By Country
- Market Attractiveness Analysis
- By Country
- By solution
- By fintech domain
- By application
- By end user
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By solution
- By fintech domain
- By application
- By end user
- By Country
- Market Attractiveness Analysis
- By Country
- By solution
- By fintech domain
- By application
- By end user
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By solution
- By fintech domain
- By application
- By end user
- By Country
- Market Attractiveness Analysis
- By Country
- By solution
- By fintech domain
- By application
- By end user
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC countries
- South Africa
- Türkiye
- Israel
- By solution
- By fintech domain
- By application
- By end user
- By Country
- Market Attractiveness Analysis
- By Country
- By solution
- By fintech domain
- By application
- By end user
- Key Takeaways
- Key Countries Market Analysis
- USA
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- UK
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By solution
- By fintech domain
- By application
- By end user
- USA
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By solution
- By fintech domain
- By application
- By end user
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- IBM
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- AWS
- Microsoft
- NVIDIA
- IBM
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


