

- Market Size (2026)
- USD 45.1 Bn
- Forecast (2036)
- USD 99.2 Bn
- CAGR (2026 to 2036)
- 8.2%
How big is Wearable Medical Device Market in 2026?
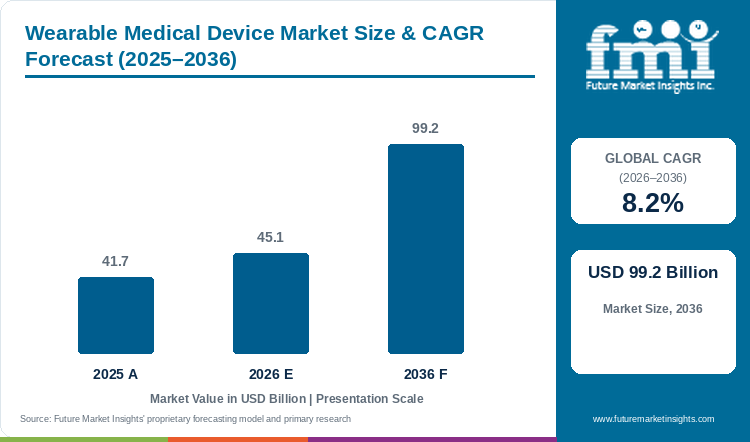
Measured at USD 41.7 billion in 2025 and advancing to USD 45.1 billion in 2026, the wearable medical device market is forecast to reach USD 99.2 billion by 2036 at an 8.2% CAGR.
Hospitals and health insurers are moving chronic diabetes, heart-rhythm, and post-surgical care out of acute inpatient beds and into patient homes using body-worn patches and pumps, supported by a September 2025 clinical study in the Journal of Diabetes Science and Technology showing that wearable continuous glucose sensors and automated insulin pumps kept high-risk hospitalized and dialysis patients within safe blood-sugar ranges [1]. Therapeutic Wearables Insulin Patch Pumps, TENS & Respiratory are projected to capture 54.9% of device category demand in 2026 through repeat 3-day pod and electrode refills, whereas standalone continuous glucose monitoring sensors are forecast to grow at a faster 15.7% compound annual growth rate as non-insulin Type 2 diabetes and over-the-counter users adopt epidermal biosensors. Clinical deployment spans hospital discharge kits, retail pharmacy prescription counters, and home telemonitoring networks. FMI analysis indicates that global wearable medical device market value will progress from USD 41.7 billion in 2025 to USD 45.1 billion in 2026 and reach USD 99.2 billion by 2036 at an 8.2% CAGR, generating USD 54.1 billion in added valuation. Nonetheless, skin irritation from multi-week medical adhesives and strict FDA cybersecurity and alarm-accuracy reviews continue to delay hospital rollouts and limit multi-year patient wear compliance.
Key Market Trends & Insights
- By device category: Therapeutic wearables covering insulin patch pumps, TENS, and respiratory units are projected to capture 54.9% of category demand in 2026 because disposable drug-delivery pods and neuromodulation cartridges generate recurring monthly replenishment.
- By wearing site: Adhesive skin patches and chest straps are estimated to hold 46.3% of site demand in 2026 as single-use ECG and interstitial glucose patches eliminate motion artifacts and cross-contamination.
- By clinical application: Home healthcare and remote patient monitoring are forecast to command 62.9% of application demand in 2026 as health systems shift post-surgical and chronic disease management into outpatient residences.
- By regulatory class: FDA 510k and CE Class IIa/IIb cleared medical grade devices are anticipated to account for 71.3% of regulatory demand in 2026 because physician billing and insurer coverage require validated clinical accuracy.
- By distribution and reimbursement: Hospital and physician prescription dispensing is projected to represent 53.7% of channel distribution in 2026, while private commercial health insurance and out-of-pocket pathways account for 59.3% of payment volume.
Regional Highlights
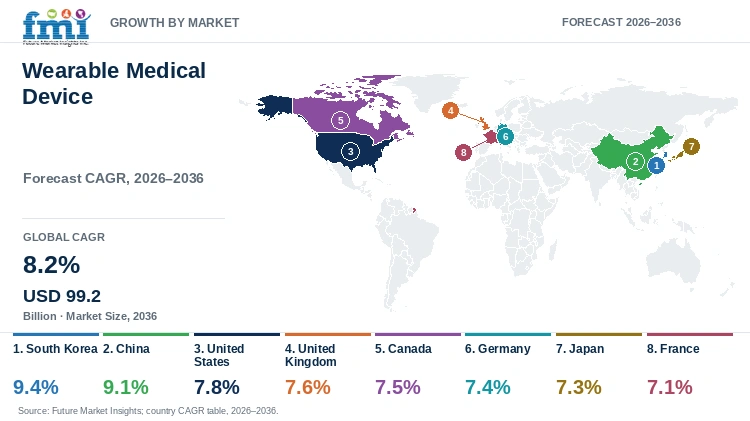
- Top national expansion: South Korea is forecast to lead country-level progression at a 9.4% CAGR from 2026 to 2036, supported by National Health Insurance Service reimbursement for ambulatory cardiac patches and smart inpatient ward deployments.
- Broader country progression: China at 9.1% CAGR, the United States at 7.8%, the United Kingdom at 7.6%, Canada at 7.5%, Germany at 7.4%, Japan at 7.3%, and France at 7.1% anchor global biosensor and patch-pump procurement.
Market Size & Forecast
Table 1: Market Size and Forecast for the Wearable Medical Device Market (USD billion and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 41.7 billion |
| Estimated Market Size in 2026 | USD 45.1 billion |
| Projected Market Size by 2036 | USD 99.2 billion |
| CAGR, 2026 to 2036 | 8.2% |
| Added Valuation, 2026 to 2036 | USD 54.1 billion |
The global wearable medical device sector is projected to generate an incremental USD 54.1 billion in net valuation expansion between 2026 and 2036, lifting annual market size from USD 45.1 billion to USD 99.2 billion. Device manufacturers and health systems are scaling automated insulin delivery pumps and multi-week ambulatory cardiac telemetry patches that replace bulky wired Holter monitors. In November 2025, cardiologists analyzing over 1 million patients in Heart Rhythm demonstrated that 14-day ambulatory electrocardiogram patch monitoring achieved high arrhythmia diagnostic yield across both frequent and infrequent symptom cohorts [2]. Multi-week disposable sensor wear economics drive recurring consumable revenue per diagnosed patient.
Monitored Patient Pool & Disposable Biosensor Unit Sizing
Table 2: Monitored Patient Pool and Disposable Biosensor Unit Sizing for the Wearable Medical Device Market (USD billion and operational ranges), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD billion) | 41.7 | 45.1 | 99.2 |
| Patients on prescription wearable monitoring/therapy (million) | 42.0 to 46.0 | 45.5 to 50.0 | 96.0 to 105.0 |
| Annual disposable biosensor & patch-pod units (million) | 680.0 to 740.0 | 745.0 to 810.0 | 1,680.0 to 1,820.0 |
| Annual spend per monitored patient (USD) | 905.0 to 990.0 | 902.0 to 991.0 | 945.0 to 1,033.0 |
Operational note: Monitored patient pool and annual disposable sensor unit figures reconcile corporate CGM, patch-pump, and ambulatory ECG shipment filings against payer remote patient monitoring claims.
Annual disposable sensor shipments expand faster than hardware controller sales because continuous glucose monitors and insulin patch pods require replacement every 3 to 15 days. Hospital cardiology and endocrinology departments connect wearable patches to remote patient monitoring platforms that automate clinician triage when biometric thresholds are breached. Higher sensor replacement frequency across Type 2 basal insulin and heart-failure populations sustains high-margin consumable growth through 2036.
Per Capita & Hospital Prescription Channel Sizing
Table 3: Per Capita and Payer Coverage Indicators for the Wearable Medical Device Market (USD and percentages), 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.2 | 8.3 | 9.0 |
| Annual per capita wearable medtech spend (USD) | 5.09 | 5.43 | 11.02 |
| Private insurance & out-of-pocket pathway share (%) | 59.0% to 60.0% | 59.3% | 56.0% to 58.0% |
| Public healthcare & national formulary share (%) | 40.0% to 41.0% | 40.7% | 42.0% to 44.0% |
Table 4: Hospital Prescription and Commercial Insurance Allocation for the Wearable Medical Device Market (USD billion and shares), 2026
| Metric | Value | Institutional Reference Basis |
|---|---|---|
| Market size, 2026 | USD 45.1 billion | 2026 global valuation baseline |
| Hospital & physician prescription channel, 2026 | USD 24.2 billion | 53.7% primary distribution channel allocation |
| Private commercial insurance & out-of-pocket, 2026 | USD 26.7 billion | 59.3% primary reimbursement pathway allocation |
| Cleared medical-grade device allocation, 2026 | USD 32.2 billion | 71.3% FDA 510k & CE Class IIa/IIb share |
Hospital and physician prescription dispensing accounts for USD 24.2 billion of the USD 45.1 billion global market in 2026, while private commercial health insurance and out-of-pocket spending represents USD 26.7 billion across payment pathways. Integrated delivery networks deploy connected remote healthcare telemetry to monitor post-discharge sepsis, cardiac arrhythmia, and gestational diabetes patients at home. Pharmacy benefit expansion for wearable patch pumps and CGM sensors lowers patient copays and accelerates prescription fulfillment.
Analyst Perspective
"Wearable medtech suppliers can no longer rely on raw biometric data collection alone to secure hospital formulary contracts. Payers and clinical directors demand closed-loop therapeutic actuation, FDA-cleared artificial intelligence triage algorithms that reduce nurse alarm fatigue, and direct CPT reimbursement integration."
- Anurag Sharma, Principal Consultant, Future Market Insights.
How is the wearable medical device market segmented?
The wearable medical device market is segmented by device category, wearing site, clinical application, regulatory class, distribution channel, and reimbursement pathway. In 2026, Therapeutic Wearables Insulin Patch Pumps, TENS & Respiratory are projected at 54.9%, Adhesive Skin Patches & Chest Straps at 46.3%, Home Healthcare & Remote Patient Monitoring at 62.9%, FDA 510k & CE Class IIa/IIb Cleared Medical Grade at 71.3%, Hospital & Physician Prescription Dispensing at 53.7%, and Private Commercial Health Insurance and Out-of-Pocket at 59.3%.
By device category: Therapeutic Wearables Insulin Patch Pumps, TENS & Respiratory, and Diagnostic & Vital-Sign Monitoring ECG Patches, Pulse Oximeters & Cuffless BP.
By wearing site: Adhesive Skin Patches & Chest Straps, Wrist-Worn Clinical Trackers & Smart Rings, and Headbands, Smart Hearables & Smart Clothing.
By clinical application: Home Healthcare & Remote Patient Monitoring, Cardiology, Arrhythmia & Post-Discharge Telemetry, Endocrinology & Automated Drug Delivery, and Sleep Apnea & Neuromodulation Pain Relief.
By regulatory class: FDA 510k & CE Class IIa/IIb Cleared Medical Grade and Consumer-Clinical Crossover Wellness Grade.
By distribution and reimbursement: Hospital & Physician Prescription Dispensing, Retail Pharmacies & Durable Medical Equipment Providers, Direct-to-Consumer E-Commerce, Private Commercial Health Insurance and Out-of-Pocket (59.3%), and Public Healthcare Systems and National Formularies (40.7%).
Why do Therapeutic Wearables Insulin Patch Pumps, TENS & Respiratory lead the device category?
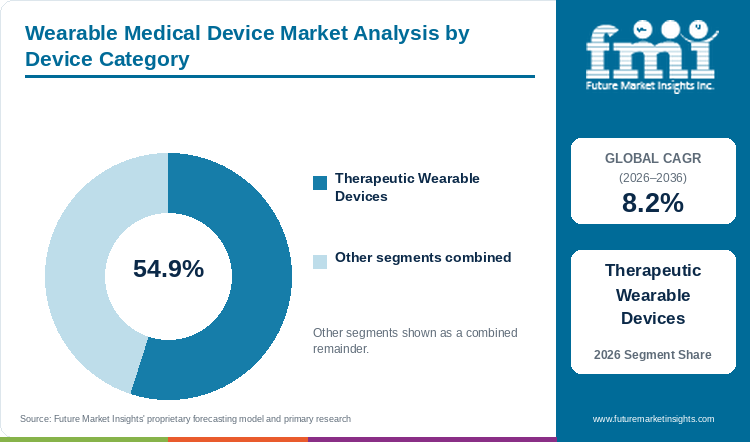
Therapeutic Wearables Insulin Patch Pumps, TENS & Respiratory are projected to capture 54.9% of device category demand in 2026, supported by recurring disposable pod and electrode refills.
Table 5: Device Category Share for the Wearable Medical Device Market (percentage share), 2026
| Device Category | Share (2026) |
|---|---|
| Therapeutic Wearables Insulin Patch Pumps, TENS & Respiratory | 54.9% |
| Other Segments Combined | 45.1%* |
| Total | 100.0% |
*Note: Other Segments Combined represents Diagnostic & Vital-Sign Monitoring ECG Patches, Pulse Oximeters & Cuffless BP. Source: Future Market Insights analysis.
Table 6: Device Category Leadership and Market Growth for the Wearable Medical Device Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 8.2% |
| Leading Segment | Therapeutic Wearables Insulin Patch Pumps, TENS & Respiratory |
Endocrinologists, pain clinics, and pharmacy benefit managers favor tubeless insulin patch pumps, wearable TENS units, and ambulatory respiratory devices because patients replace disposable drug-delivery pods and adhesive electrodes every 3 to 7 days. In the complementary diagnostic tier, hospital wards deploy wireless clinical pulse oximeters and continuous ECG patches to detect postoperative respiratory depression and atrial fibrillation.
- Therapeutic Wearables Insulin Patch Pumps, TENS & Respiratory are projected to capture 54.9% of device category demand in 2026, while Diagnostic & Vital-Sign Monitoring ECG Patches, Pulse Oximeters & Cuffless BP account for the remaining 45.1%.
- Real-world clinical outcomes from 1,922 patients published in Pain Management in April 2026 demonstrated that adaptive dual-modality transcutaneous electrical nerve stimulation and neuromuscular stimulation via the wearable NXTSTIM EcoAI platform significantly reduced chronic lower-back pain scores without opioid escalation [3].
Why do Adhesive Skin Patches & Chest Straps define the largest wearing site segment?
Adhesive Skin Patches & Chest Straps are estimated to secure 46.3% of the wearing site category in 2026, driven by single-use epidermal ECG and CGM sensor stability.
Single-use epidermal patches applied to the upper arm or chest maintain stable electrode and microneedle contact during sleep and exercise while eliminating hospital cross-contamination between patients. Sleep clinics also prescribe home sleep apnea diagnostic wearables using forehead and finger sensors to replace overnight hospital polysomnography labs.
- Adhesive Skin Patches & Chest Straps are estimated to command 46.3% of the wearing site category in 2026, ahead of Wrist-Worn Clinical Trackers & Smart Rings and Headbands, Smart Hearables & Smart Clothing.
- Clinical trial methodologists writing in Nature Reviews Drug Discovery in March 2026 documented that pharmaceutical sponsors routinely deploy epidermal skin patches and wrist-worn accelerometers to capture continuous digital endpoints across Phase II and Phase III neurology, cardiology, and metabolic trials [4].
What keeps Home Healthcare & Remote Patient Monitoring ahead by clinical application?
Home Healthcare & Remote Patient Monitoring are expected to command 62.9% of clinical application demand in 2026, driven by hospital-at-home discharge protocols.
Hospital executives and health insurers transition stable cardiac, pulmonary, and diabetic patients out of high-cost inpatient beds into supervised home recovery using multiparameter patient monitors connected to virtual nursing command centers.
- Home Healthcare & Remote Patient Monitoring are expected to hold 62.9% of clinical application demand in 2026, followed by Cardiology, Arrhythmia & Post-Discharge Telemetry, Endocrinology & Automated Drug Delivery, and Sleep Apnea & Neuromodulation Pain Relief.
- A health-economic claims analysis of 213,564 commercially insured patients published in The American Journal of Managed Care in August 2025 found that multi-year continuous ambulatory cardiac monitoring patches achieved lower total healthcare costs and fewer repeat diagnostic tests per detected arrhythmia than 24-hour Holter monitors [5].
Why do FDA 510k & CE Class IIa/IIb Cleared Medical Grade devices lead the regulatory class category?
FDA 510k & CE Class IIa/IIb Cleared Medical Grade devices are forecast to generate 71.3% of regulatory class valuation in 2026, owing to physician billing and payer accuracy mandates.
Formal FDA 510(k) or European Union Medical Device Regulation Class IIa/IIb clinical clearance is mandatory for physician prescription dispensing, hospital electronic health record integration, and independent CPT or national formulary reimbursement.
- FDA 510k & CE Class IIa/IIb Cleared Medical Grade wearables are forecast to account for 71.3% of regulatory class demand in 2026, whereas Consumer-Clinical Crossover Wellness Grade devices represent 28.7%.
- An umbrella review of 42 systematic reviews published in Physiological Reviews in December 2025 evaluated wrist-worn wearables across cardiovascular, metabolic, and mental health outcomes and concluded that medical-grade regulatory validation is required to prevent false-positive patient anxiety [6].
What gives Hospital & Physician Prescription Dispensing the leading position in distribution and reimbursement?
Hospital & Physician Prescription Dispensing is anticipated to account for 53.7% of distribution channel demand in 2026, while Private Commercial Health Insurance and Out-of-Pocket represents 59.3% of payment pathways.
Endocrinologists, cardiologists, and hospital discharge teams initiate prescription orders and prior-authorization workflows for closed-loop insulin pods and 14-day arrhythmia patches, while private commercial health insurers and out-of-pocket buyers fund the majority of global device payments.
- Hospital & Physician Prescription Dispensing is anticipated to capture 53.7% of distribution channel demand in 2026 ahead of Retail Pharmacies & DME Providers and Direct-to-Consumer E-Commerce, while Private Commercial Health Insurance and Out-of-Pocket represents 59.3% of payment pathways versus 40.7% for Public Healthcare Systems and National Formularies.
- Cardiology health-services researchers reporting in the Journal of Telemedicine and Telecare in January 2026 evaluated a hypertension remote patient monitoring program in a large healthcare system and demonstrated a positive 22.2% return on investment when cellular blood-pressure wearables were billed under established reimbursement codes [7].
What are the drivers, restraints, and opportunities in the wearable medical device market?
In the wearable medical device market, expanding remote patient monitoring reimbursement and closed-loop diabetes adoption propel sensor volumes whereas adhesive skin irritation restrains wear compliance and AI-enabled respiratory patches create high-margin hospital opportunities.
- Driver: Expansion of CPT and national reimbursement codes for remote physiological monitoring, continuous glucose sensing, and ambulatory ECG telemetry accelerates physician prescribing.
- Restraint: Epidermal adhesive skin irritation, nurse telemetry alert overload, and strict FDA cybersecurity and clinical trial endpoints restrain multi-year patient adherence.
- Opportunity: Over-the-counter metabolic biosensors, AI-enabled opioid respiratory depression monitors, and closed-loop neurostimulation patches open high-growth clinical segments.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Miniaturized optical and electrochemical biosensors are expanding clinical diagnostics into home sleep medicine and non-diabetic metabolic tracking. Device makers launch over-the-counter glucose biosensors and finger-worn pulse oximetry rings that allow primary care physicians to screen for obstructive sleep apnea and prediabetes without hospital admission. In May 2026, a systematic review and meta-analysis of 19 studies covering 1,622 participants published in the Journal of Translational Medicine confirmed that finger-worn wearable devices achieved 88% sensitivity and 85% specificity for obstructive sleep apnea detection compared with laboratory polysomnography [8]. Validated home screening accuracy allows sleep clinics to clear multi-month diagnostic backlogs.
Risk Assessment of the Wearable Medical Device Market: Operational and Formulation Friction
Clinical proof of statistically significant reductions in hospital readmissions across complex post-discharge populations remains an operational challenge for remote monitoring vendors. Health systems procuring ambulatory infusion systems and wearable vital-sign patches require structured clinical escalation workflows so biometric alerts translate into timely physician intervention. In June 2026, investigators reporting a randomized clinical trial of 436 sepsis and infection survivors in JAMA Network Open found that remote vital-sign monitoring alone did not significantly reduce 30-day hospital readmissions unless paired with rapid outpatient clinical follow-up [9]. Device suppliers must therefore bundle automated nurse triage software with hardware sensors to prove hospital cost savings.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Next-generation self-powered triboelectric sensors and closed-loop neuromodulation patches are creating new therapeutic categories in neurology and sleep medicine. Suppliers of home sleep testing devices and cranial nerve stimulators are integrating continuous electromyography feedback directly into flexible skin patches. In January 2026, biomedical engineers publishing in Nature Communications developed a closed-loop wearable neurostimulation system using triboelectric facial-muscle sensing that automatically detects hemifacial spasms and delivers synchronized electrical pulses to suppress involuntary contractions [10]. Closed-loop sense-and-stimulate architectures allow medtech innovators to command therapeutic reimbursement rates instead of diagnostic commodity pricing.
Wearable Medical Device Market by Country (2026 to 2036)
National growth rates reflect differences in remote patient monitoring reimbursement codes, hospital-at-home bed capacity, diabetes and atrial fibrillation prevalence, and regulatory clearance pathways across eight benchmark countries.
Table 7: Country CAGR and Primary Growth Levers for the Wearable Medical Device Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| South Korea | 9.4% | MFDS breakthrough medical device clearances and NHIS inpatient smart-ward telemetry |
| China | 9.1% | NMPA Class II wireless vital-sign patches and domestic CGM manufacturing scale |
| United States | 7.8% | Medicare basal-insulin CGM coverage, pharmacy patch pumps, and CPT RPM billing |
| United Kingdom | 7.6% | NICE hybrid closed-loop insulin pump mandates and NHS virtual ward expansion |
| Canada | 7.5% | Provincial public formulary CGM/pump coverage and rural cardiac telemonitoring |
| Germany | 7.4% | Statutory GKV Hilfsmittelverzeichnis reimbursement and DiGA telemonitoring |
| Japan | 7.3% | Super-aging home cardiac patches and PMDA-cleared wearable blood-pressure cuffs |
| France | 7.1% | Permanent Télésurveillance Médicale reimbursement and LPPR diabetes coverage |
Source: Future Market Insights analysis
South Korea Wearable Medical Device Market Outlook (2026 to 2036)
Regulatory clearances from the Ministry of Food and Drug Safety designating wearable biosensors as breakthrough medical devices drive rapid adoption across tertiary hospital networks in South Korea. Universal National Health Insurance coverage for multi-day ambulatory ECG patches and smart hospital telemetry wards accelerates clinical device deployments. In April 2026, healthcare governance researchers publishing in Risk Management and Healthcare Policy highlighted how South Korea deploys wearable biometric sensors in geriatric care while enforcing strict data encryption standards [11]. South Korea is projected to record the fastest national wearable medical device growth at a 9.4% CAGR from 2026 to 2036 as university hospitals expand telemetry monitoring. However, physician resistance against uncompensated data review and strict cybersecurity audits restrict adoption outside major metropolitan hospitals.
Key takeaway: In South Korea, smart inpatient ward telemetry, NHIS patch-ECG reimbursement, and geriatric AI monitoring anchor a 9.4% CAGR through 2036.
China Wearable Medical Device Market Outlook (2026 to 2036)
National Medical Products Administration Class II fast-track approvals for continuous physiological sensors accelerate clinical deployments across provincial hospitals throughout China. Domestic device manufacturers rapidly scale automated production of continuous glucose monitors, wearable temperature patches, and cuffless blood-pressure watches to lower unit costs. In September 2026, clinical informatics investigators at Peking University published a review in JMIR mHealth and uHealth showing that continuous wearable temperature patches detected inpatient fever hours earlier than manual nurse thermometry [12]. China is forecast to expand at a 9.1% CAGR between 2026 and 2036 as public health authorities integrate wireless patient monitors into provincial smart-ward modernization programs. Still, centralized provincial volume-based procurement tenders depress wholesale device selling prices, forcing biowearable manufacturers to negotiate aggressive component supply agreements.
Key takeaway: In China, hospital wireless vital-sign patches, domestic CGM manufacturing scale, and aging diabetes management drive a 9.1% CAGR.
United States Wearable Medical Device Market Outlook (2026 to 2036)
Expanded Medicare and commercial payer reimbursement for basal-insulin continuous glucose monitors and pharmacy-dispensed wearable insulin patch pumps underpins medical biowearable demand across the United States. Healthcare systems actively leverage dedicated Current Procedural Terminology remote physiological monitoring codes to reimburse clinicians for continuous vital sign tracking. In August 2026, a systematic review published in the Journal of Medical Internet Research documented how hospitals integrate wearable patches into electronic track-and-trigger systems to prevent clinical deterioration [13]. Wearable medical device demand in the United States is estimated to progress at a 7.8% CAGR from 2026 to 2036 on home healthcare expansion. Even so, complex insurance prior-authorization requirements and frequent claims denials for off-label telemetry monitoring create substantial reimbursement friction for outpatient clinical providers.
Key takeaway: In the United States, Medicare basal-insulin CGM coverage, pharmacy patch-pump dispensing, and hospital early-warning telemetry sustain a 7.8% CAGR.
United Kingdom Wearable Medical Device Market Outlook (2026 to 2036)
National Health Service virtual ward initiatives and binding clinical guidance mandating hybrid closed-loop insulin delivery systems accelerate wearable medical device procurement across the United Kingdom. Regional Integrated Care Boards contract bulk biowearable supplies to manage chronic heart failure, diabetes, and respiratory conditions in home-based clinical settings. In June 2026, researchers at Newcastle University published a systematic clinical review in JMIR Aging showing that body-worn sensors accurately quantify mobility decline and sedentary behavior in older adults [14]. The United Kingdom wearable medical device market is projected to advance at a 7.6% CAGR between 2026 and 2036 as regional trusts expand decentralized virtual monitoring. Nevertheless, constrained capital budgets across regional hospital trusts and protracted centralized procurement cycles delay enterprise-wide biowearable hardware deployments.
Key takeaway: In the United Kingdom, NICE hybrid closed-loop diabetes mandates and NHS virtual ward telemetry programs support a 7.6% CAGR.
Canada Wearable Medical Device Market Outlook (2026 to 2036)
Provincial health ministries across Ontario, Alberta, and British Columbia expand public healthcare coverage for continuous glucose monitors, tubeless insulin patch pumps, and remote cardiac telemonitoring patches. Hospital networks deploy wireless wearable telemetry to supervise post-operative surgical patients across rural communities while reducing costly hospital readmission rates. Biomedical engineering researchers publishing in Communications Medicine in January 2026 demonstrated that wearable multi-sensor physiological patches accurately track clinical anxiety and autonomic stress in outpatient populations [15]. Canada is forecast to grow at a 7.5% CAGR from 2026 to 2036 as provincial homecare programs fund preventive biometric tracking. Even so, fragmented interprovincial formulary listing timelines and divergent medical device reimbursement policies across provinces complicate national commercial expansion for innovative medical sensor manufacturers.
Key takeaway: In Canada, provincial public formulary coverage for CGM and patch pumps and rural remote cardiac telemetry underpin a 7.5% CAGR.
Germany Wearable Medical Device Market Outlook (2026 to 2036)
Statutory health insurance coverage governed by the Federal Joint Committee and medical aid catalog listings anchor retail and hospital procurement of clinical biowearables across Germany. Sickness funds reimburse physician-prescribed continuous glucose sensors, ambulatory wearable cardiac event recorders, and certified digital health applications linked to wearable hardware. Medical informatics researchers at the University of Oldenburg publishing in JMIR mHealth and uHealth confirmed that wearable vital-sign patches enable reliable early detection of chronic cardiovascular decompensation [16]. Germany is anticipated to expand at a 7.4% CAGR between 2026 and 2036 as statutory insurers broaden preventive telemonitoring entitlements. However, stringent Federal Office for Information Security data protection mandates and lengthy clinical evaluation dossiers slow commercial market authorization for novel sensor architectures.
Key takeaway: In Germany, statutory GKV Hilfsmittelverzeichnis device coverage and DiGA telemonitoring reimbursement support a 7.4% CAGR through 2036.
Japan Wearable Medical Device Market Outlook (2026 to 2036)
Super-aging demographic trends and acute physician shortages in rural prefectures drive hospital adoption of continuous biowearables under Japan's Medical DX healthcare modernization program. Domestic electronics conglomerates and medical device groups co-develop PMDA-approved wearable electrocardiogram patches and cuffless nocturnal blood-pressure monitors for decentralized outpatient monitoring. In December 2025, surgical investigators at Nagoya City University reported in the Annals of Surgical Oncology that wearable autonomic stress sensors objectively evaluated clinical recovery trajectories after major robotic procedures [17]. Japan is projected to progress at a 7.3% CAGR from 2026 to 2036 as government fee schedules award higher reimbursement points for remote home telemetry. Nevertheless, conservative clinical prescribing habits among senior physicians and fixed biennial medical fee reductions limit premium pricing power for specialized biowearables.
Key takeaway: In Japan, super-aging home cardiac telemetry, wrist-worn blood-pressure diagnostics, and perioperative biosensor adoption sustain a 7.3% CAGR.
France Wearable Medical Device Market Outlook (2026 to 2036)
Permanent national reimbursement under the Tele-surveillance Medicale framework and expanded diabetes product listings accelerate clinical biowearable integration across public hospital centers in France. French cardiology and diabetology services routinely equip chronic heart-failure and insulin-dependent patients with continuous wearable sensors linked to centralized hospital monitoring platforms. European cardiology investigators publishing a meta-analysis in Heart confirmed that wearable cardioverter-defibrillator vests effectively protect non-ischaemic cardiomyopathy patients against sudden cardiac mortality during medical therapy titration [18]. France is forecast to expand at a 7.1% CAGR between 2026 and 2036 as regional health authorities fund decentralized chronic disease monitoring. Still, strict digital health hosting certifications and protracted ministerial pricing negotiations compress operating margins for commercial hardware suppliers.
Key takeaway: In France, permanent Télésurveillance Médicale reimbursement and LPPR coverage for diabetes and cardiac wearables drive a 7.1% CAGR.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the wearable medical device market?
Abbott Laboratories, DexCom, Inc., Medtronic plc, Koninklijke Philips N.V., Insulet Corporation, Masimo Corporation, iRhythm Technologies, Inc., and Omron Healthcare Co., Ltd. are the notable companies in the wearable medical device market.
Competitive rivalry in the global wearable medical device market centers on biosensor accuracy, closed-loop pump interoperability, FDA 510(k) and CE Class IIa/IIb clearances, and pharmacy and hospital reimbursement coverage.
- Tier 1 - Global Diabetes Biowearable & Closed-Loop Leaders: Abbott Laboratories, DexCom, Inc., and Medtronic plc command global continuous glucose sensing, smart insulin pen, and automated insulin delivery ecosystems across pharmacy and hospital channels.
- Tier 2 - Hospital Telemetry, Patch-Pump & Oximetry Specialists: Koninklijke Philips N.V., Insulet Corporation, and Masimo Corporation lead ambulatory cardiac BioTel patches, Omnipod tubeless insulin pods, and hospital Radius VSM wireless patient monitoring.
- Tier 3 - Focused Arrhythmia Patch & Cuffless Blood-Pressure Innovators: iRhythm Technologies, Inc. and Omron Healthcare Co., Ltd. anchor multi-year Zio ambulatory ECG monitoring and clinical-grade wearable blood-pressure and TENS therapy.
Competitive Benchmarking: Wearable Medical Device Market
Table 8: Competitive Benchmarking for the Wearable Medical Device Market (qualitative capability ratings), 2026
| Company | Biosensor & Therapy Breadth | FDA/CE & AI Algorithm Depth | Hospital & Payer Access | Geographic Reach |
|---|---|---|---|---|
| Abbott Laboratories | High | High | High | High |
| DexCom, Inc. | High | High | High | High |
| Medtronic plc | High | High | High | High |
| Koninklijke Philips N.V. | High | High | High | High |
| Insulet Corporation | Medium | High | High | High |
| Masimo Corporation | High | High | High | High |
| iRhythm Technologies, Inc. | Medium | High | High | Medium |
| Omron Healthcare Co., Ltd. | High | Medium | High | High |
Scoring basis: High, Medium, and Low ratings reflect therapeutic and diagnostic biosensor breadth, FDA/CE regulatory and AI algorithm depth, hospital and pharmacy reimbursement access, and multinational geographic reach.
Key Developments in the Wearable Medical Device Market
- In January 2026, Medtronic plc received FDA 510(k) clearance for its MiniMed Go Smart MDI multiple daily injection system integrating the InPen smart insulin pen with the 15-day wearable Instinct continuous glucose sensor made by Abbott Laboratories [19].
- In July 2026, DexCom, Inc. reported second-quarter 2026 global revenue of USD 1.31 billion, up 13% year-over-year, and positive CONNECT randomized trial results in non-insulin Type 2 diabetes and an updated Stelo over-the-counter biosensor app [20].
- In April 2026, iRhythm Holdings, Inc. reported first-quarter 2026 revenue of USD 0.20 billion, up 25.7% year-over-year with a 70.9% gross margin, driven by primary-care and cardiology expansion of Zio Monitor and Zio AT 14-day ambulatory ECG patches [21].
Key Players in the Wearable Medical Device Market
Tier 1: Global Diabetes Biowearable & Closed-Loop Leaders
- Abbott Laboratories
- DexCom, Inc.
- Medtronic plc
Tier 2: Hospital Telemetry, Patch-Pump & Oximetry Specialists
- Koninklijke Philips N.V.
- Insulet Corporation
- Masimo Corporation
Tier 3: Focused Arrhythmia Patch & Cuffless Blood-Pressure Innovators
- iRhythm Technologies, Inc.
- Omron Healthcare Co., Ltd.
Wearable Medical Device Market - Report Scope
Table 9: Report Scope for the Wearable Medical Device Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Device Category; Wearing Site; Clinical Application; Regulatory Class; Distribution Channel; Reimbursement and Payment Pathway |
| Quantitative Units | USD Billion |
| Market Definition | Includes commercial sales of therapeutic wearables (insulin patch pumps, TENS, respiratory devices) and diagnostic/vital-sign monitoring wearables (CGM sensors, ambulatory ECG patches, pulse oximeters, cuffless blood-pressure monitors). Category Scope Note: Excludes unvalidated consumer fitness bands, stationary bedside hospital monitors, and surgically implanted pacemakers. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | South Korea, China, United States, United Kingdom, Canada, Germany, Japan, France, and additional countries in the full report |
| Key Companies Covered | Abbott Laboratories, DexCom, Inc., Medtronic plc, Koninklijke Philips N.V., Insulet Corporation, Masimo Corporation, iRhythm Technologies, Inc., Omron Healthcare Co., Ltd. |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with top-down and bottom-up market triangulation. |
Wearable Medical Device Market - Research Methodology
Table 10: Research Methodology for the Wearable Medical Device Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Structured interviews with hospital telemetry directors, endocrinologists, electrophysiologists, and payer medical policy officers to validate sensor replacement intervals and CPT reimbursement rates. |
| Secondary Research | Analysis of SEC 10-K/10-Q filings, FDA 510(k) and De Novo clearance databases, PubMed clinical telemetry cohorts, and CMS/NICE/GKV national coverage determinations. |
| Market Sizing and Forecasting | Top-down health-system and payer remote monitoring expenditure models reconciled against bottom-up active patient pools and annual disposable sensor shipments from 2026 to 2036. |
| Country Forecasting Model | Econometric national models weight insulin-treated diabetes prevalence, atrial fibrillation hospitalization rates, and statutory telemonitoring reimbursement across eight countries. |
| Operational Benchmark Traceability | Patient pool and unit volume benchmarks in Tables 2, 3, and 4 trace to Heart Rhythm 1-million-patient cohorts, AJMC claims analyses, and corporate Q1-Q3 2026 financial disclosures. |
| Data Triangulation and Validation | OEM sensor and patch-pump revenues are cross-checked against pharmacy benefit and durable medical equipment claims to eliminate double counting between hardware and cloud software fees. |
Wearable Medical Device Market by Segments
Wearable Medical Device Market segmented by Device Category:
- Therapeutic Wearable Devices
- Diagnostic & Monitoring Wearables
Wearable Medical Device Market segmented by Wearing Site:
- Skin Patches & Straps
- Clinical Trackers & Rings
- Headbands, Hearables & Clothing
Wearable Medical Device Market segmented by Clinical Application:
- Home & Remote Monitoring
- Cardiology & Arrhythmia Telemetry
- Endocrinology & Drug Delivery
- Sleep & Neuromodulation Therapy
Wearable Medical Device Market segmented by Regulatory Class:
- Cleared Medical-Grade Wearables
- Consumer-Clinical Crossover Grade
- De Novo Active Wearables
Wearable Medical Device Market segmented by Distribution Channel:
- Hospital & Physician Prescriptions
- Retail Pharmacies & DME
- Direct-to-Consumer E-Commerce
Wearable Medical Device Market segmented by Reimbursement and Payment Pathway:
- Private Insurance & Out-of-Pocket
- Public Systems & Formularies
- Value-Based Care Programs
Wearable Medical Device Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Türkiye
- Israel
Research Sources and Bibliography
- [1] Agarwal, S., Demidowich, A. P., Soliman, D., Umpierrez, G. E., & Galindo, R. J. (2025, September 3). Wearable Diabetes Technology for Hospitalized People With Diabetes and End-Stage Kidney Disease, Peripartum State, and Steroid Use. Journal of Diabetes Science and Technology, 20(2), 290-298 (PubMed PMID 40899799).
- [2] Battisti, A. J., Pinkerton, R., Fokin, V., Yang, M., & Turakhia, M. P. (2025, November 7). Relationship of symptom frequency and symptom-rhythm correlation to arrhythmia type and time to detection: Insights from ambulatory electrocardiogram monitoring in over 1 million patients. Heart Rhythm, 23(2), e200-e208 (PubMed PMID 41205886).
- [3] Green, M., Billet, B., Kappell, M., Kappell, S., & Chakravarthy, K. (2026, April 19). Adaptive dual-modality neuromodulation for chronic pain and muscle dysfunction: real-world insights from the NXTSTIM EcoAI digital platform. Pain Management, 16(7), 779-788 (PubMed PMID 42002406).
- [4] Fayad, Z. A., Hirten, R. P., Nadkarni, G. N., & Kim, Y. S. (2026, March 23). Wearable technologies in clinical trials for drug development: trends and emerging opportunities. Nature Reviews Drug Discovery, 25(6), 448-468 (PubMed PMID 41872333).
- [5] Russo, P., Coetzer, H., Hendrickson, E. M., Boyle, K., & Wright, B. (2025, August 13). Assessment of variation in ambulatory cardiac monitoring among commercially insured patients. The American Journal of Managed Care, 32(2), 65-73 (PubMed PMID 40834206).
- [6] Glisic, M., Llane, A., Stojic, S., Muka, T., & Franco, O. H. (2025, December 29). An umbrella review of systematic reviews of the impact of wrist-worn wearables on health outcomes. Physiological Reviews, 106(2), 935-969 (PubMed PMID 41460208).
- [7] Zhang, D. S., Millet, L., Bellows, B. K., Lee, S., & Mann, D. (2026, January 19). Program cost and return on investment analysis of remote patient monitoring for hypertension management in the cardiology department of a large healthcare system. Journal of Telemedicine and Telecare, 32(3), 1357633X251403059 (PubMed PMID 41549700).
- [8] Jin, Y., Xu, J., Yue, H., Wang, L., & Zhang, X. (2026, May 15). Performance evaluation of finger-worn devices for sleep stage classification and sleep apnea detection: a systematic review and meta-analysis. Journal of Translational Medicine, 24(1), 873 (PubMed PMID 42141446).
- [9] Yende, S., Talisa, V. B., Mayes, K., Chang, C.-C. H., & Angus, D. C. (2026, June 1). Remote Monitoring Approaches to Reduce Readmissions After Infection and Sepsis: A Randomized Clinical Trial. JAMA Network Open, 9(6), e2616641 (PubMed PMID 42275060).
- [10] Qu, X., Wan, J., Zhao, H., Liu, Z., & Li, Z. (2026, January 10). Closed-loop wearable neurostimulation system with triboelectric sensing to alleviate hemifacial spasms. Nature Communications, 16(1), 11148 (PubMed PMID 41519956).
- [11] Dharmansyah, D., Rahayuwati, L., Pramukti, I., & Mutyara, K. (2026, April 23). Privacy, Security & Governance Frameworks for AI-Powered Wearable Internet of Health Things in Elderly Care: A Comprehensive Review. Risk Management and Healthcare Policy, 19, 606165 (PubMed PMID 42052619).
- [12] Liu, Y., Zhao, Q., Li, K., & Dowding, D. (2026, September 11). Continuous Temperature Monitoring via Wearable Devices for Fever or Infection Management in Acute Care Hospitals: Scoping Review of Clinical Implementation and Data Analytics. JMIR mHealth and uHealth, 14, e89773 (PubMed PMID 42727075).
- [13] Kalhori, S. R. N., Haghi, M., Tegegne, M. D., Deserno, T. M., & Spicher, N. (2026, August 10). Automated Features, Algorithms, and Technologies of Electronic Early Warning/Track-and-Trigger Systems: Systematic Review. Journal of Medical Internet Research, 28, e58233 (PubMed PMID 42574739).
- [14] Wales, J. L., Hinchliffe, C., Falck, R. S., Del Din, S., & Rochester, L. (2026, June 25). Use of Wearable Technology for Measuring and Characterizing Sedentary Behavior in People With Mild Cognitive Impairment and Dementia: Systematic Review. JMIR Aging, 9, e85361 (PubMed PMID 42349867).
- [15] Elgendi, M., Markov, K., Liu, H., Menon, C., & Ward, R. (2026, January 9). Wearable devices for anxiety assessment: a systematic review. Communications Medicine, 6(1), 20 (PubMed PMID 41513763).
- [16] Tegegne, M. D., Kalhori, S. R. N., Haas, P., Haghi, M., & Deserno, T. M. (2026, February 11). Wearable Devices for Remote Monitoring of Chronic Diseases: Systematic Review. JMIR mHealth and uHealth, 14, e74071 (PubMed PMID 41671558).
- [17] Naiki, T., Mimura, Y., Sugiyama, Y., Tasaki, Y., & Yasui, T. (2025, December 19). Mental Stress Assessment and Clinical Application of Wearable Devices as Evaluable Outcomes in Robotic Prostatectomy. Annals of Surgical Oncology, 33(4), 3698-3706 (PubMed PMID 41419713).
- [18] Providência, R., Salih, A., Aidelsburger, P., Marijon, E., & Lambiase, P. D. (2026, March 9). Wearable cardioverter-defibrillator in patients with non-ischaemic cardiomyopathy: a meta-analysis. Heart, 112(8), heartjnl-2025-326956 (PubMed PMID 41802849).
- [19] Medtronic plc. (2026, January 12). Medtronic Diabetes announces FDA clearance for MiniMed Go Smart MDI system featuring Instinct sensor made by Abbott. Medtronic Media Newsroom.
- [20] DexCom, Inc. (2026, July 30). Dexcom Reports Second Quarter 2026 Financial Results. DexCom Investor Relations.
- [21] iRhythm Holdings, Inc. (2026, April 30). iRhythm Holdings Announces First Quarter 2026 Financial Results. iRhythm Investor Relations.
- [22] Masimo Corporation. (2026, June 22). Masimo Receives FDA 510(k) Clearance for AI-Enabled Opioid-Induced Respiratory Depression (OIRD) Detection on Radius VSM to Help Identify Respiratory Risk Sooner. Masimo Media News.
- [23] Koninklijke Philips N.V. (2026, February 10). Philips announces its 2025 Fourth-Quarter and Annual Results. Royal Philips Press Center.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete reference list and detailed citations.
This Report Answers
- How large is the wearable medical device market in 2026 and what is forecast for 2036?
- Which clinical telemetry and hospital discharge pressures support wearable medical device demand?
- Why do Therapeutic Wearables Insulin Patch Pumps, TENS & Respiratory lead the device category?
- Why do Adhesive Skin Patches & Chest Straps lead the wearing site category globally?
- How do growth rates differ across South Korea, China, the United States, and the United Kingdom?
- Which leading companies supply continuous glucose monitors, patch pumps, and cardiac telemetry patches today?
- What limits patient wear-time adherence or hospital switching in the wearable medical device market?
- What should hospital value-analysis committees evaluate before procuring wearable medical devices?
Frequently Asked Questions
How big is the wearable medical device market in 2026, and what is forecast for 2036?
According to Future Market Insights, global wearable medical device market valuation is estimated to reach USD 45.1 billion in 2026 from USD 41.7 billion in 2025. Total valuation is forecast to hit USD 99.2 billion by 2036 as health systems expand remote patient monitoring and automated insulin delivery.
What is the CAGR for the wearable medical device market from 2026 to 2036?
Future Market Insights projects an 8.2% compound annual growth rate between 2026 and 2036, representing an anticipated USD 54.1 billion expansion in annual market valuation across hospital, pharmacy, and homecare channels.
Which device category segment leads the wearable medical device market?
Therapeutic Wearables Insulin Patch Pumps, TENS & Respiratory are projected to capture 54.9% of device category demand in 2026 because disposable insulin pods and neuromodulation electrodes generate recurring monthly refills.
Which clinical application segment leads the wearable medical device market?
Home Healthcare & Remote Patient Monitoring are estimated to secure 62.9% of the clinical application category in 2026 as hospitals shift chronic endocrine and cardiac oversight into outpatient residences.
Which country has a notable growth outlook during the assessment period?
South Korea is projected to lead national growth at a 9.4% CAGR through 2036, supported by National Health Insurance reimbursement for multi-day cardiac patches and smart hospital ward telemetry.
Who are the key players in the market?
Abbott Laboratories, DexCom, Inc., Medtronic plc, Koninklijke Philips N.V., Insulet Corporation, Masimo Corporation, iRhythm Technologies, Inc., and Omron Healthcare Co., Ltd. lead commercial supply.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Billion) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Device Category, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Device Category, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Device Category, 2026 to 2036
- Therapeutic Wearable Devices
- Diagnostic & Monitoring Wearables
- Y-o-Y Growth Trend Analysis By Device Category, 2021 to 2025
- Absolute $ Opportunity Analysis By Device Category, 2026 to 2036
- Global Market Analysis and Forecast, By Wearing Site, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Wearing Site, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Wearing Site, 2026 to 2036
- Skin Patches & Straps
- Clinical Trackers & Rings
- Headbands, Hearables & Clothing
- Y-o-Y Growth Trend Analysis By Wearing Site, 2021 to 2025
- Absolute $ Opportunity Analysis By Wearing Site, 2026 to 2036
- Global Market Analysis and Forecast, By Clinical Application, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Clinical Application, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Clinical Application, 2026 to 2036
- Home & Remote Monitoring
- Cardiology & Arrhythmia Telemetry
- Endocrinology & Drug Delivery
- Sleep & Neuromodulation Therapy
- Y-o-Y Growth Trend Analysis By Clinical Application, 2021 to 2025
- Absolute $ Opportunity Analysis By Clinical Application, 2026 to 2036
- Global Market Analysis and Forecast, By Regulatory Class, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Regulatory Class, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Regulatory Class, 2026 to 2036
- Cleared Medical-Grade Wearables
- Consumer-Clinical Crossover Grade
- De Novo Active Wearables
- Y-o-Y Growth Trend Analysis By Regulatory Class, 2021 to 2025
- Absolute $ Opportunity Analysis By Regulatory Class, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Hospital & Physician Prescriptions
- Retail Pharmacies & DME
- Direct-to-Consumer E-Commerce
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Reimbursement and Payment Pathway, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Billion) Analysis By Reimbursement and Payment Pathway, 2021 to 2025
- Current and Future Market Size Value (USD Billion) Analysis and Forecast By Reimbursement and Payment Pathway, 2026 to 2036
- Private Insurance & Out-of-Pocket
- Public Systems & Formularies
- Value-Based Care Programs
- Y-o-Y Growth Trend Analysis By Reimbursement and Payment Pathway, 2021 to 2025
- Absolute $ Opportunity Analysis By Reimbursement and Payment Pathway, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Billion) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Billion) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- By Country
- Market Attractiveness Analysis
- By Country
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- By Country
- Market Attractiveness Analysis
- By Country
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Benelux
- Nordics
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- By Country
- Market Attractiveness Analysis
- By Country
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- By Country
- Market Attractiveness Analysis
- By Country
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- By Country
- Market Attractiveness Analysis
- By Country
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- By Country
- Market Attractiveness Analysis
- By Country
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Billion) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Billion) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Türkiye
- Israel
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- By Country
- Market Attractiveness Analysis
- By Country
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Türkiye
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Device Category
- By Wearing Site
- By Clinical Application
- By Regulatory Class
- By Distribution Channel
- By Reimbursement and Payment Pathway
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Abbott Laboratories
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- DexCom, Inc.
- Medtronic plc
- Koninklijke Philips N.V.
- Insulet Corporation
- Masimo Corporation
- iRhythm Technologies, Inc.
- Omron Healthcare Co., Ltd.
- Abbott Laboratories
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


