

- Market Size (2026)
- USD 850.0 Mn
- Forecast (2036)
- USD 1801.4 Mn
- CAGR (2026 to 2036)
- 7.8%
How big is Chitin Market in 2026?
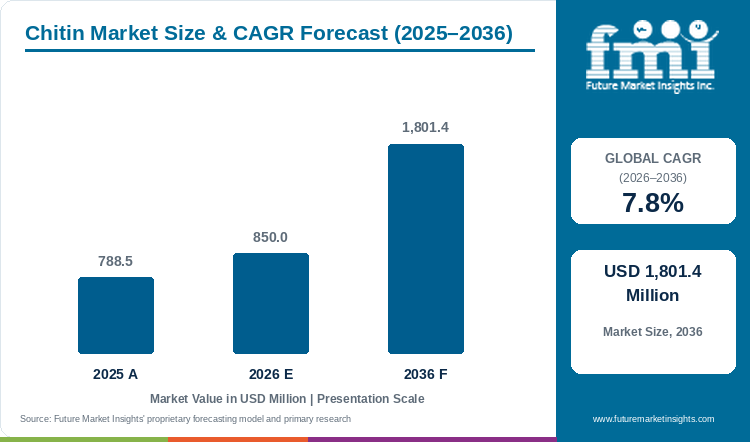
Sales in the chitin market are projected to grow at 7.8% CAGR, with the market size rising from USD 788.5 Million in 2025 to USD 850.0 Million in 2026 and reaching USD 1,801.4 Million by 2036.
According to Future Market Insights analysis, the global chitin market expands from USD 788.5 Million in 2025 to USD 850.0 Million in 2026 and is projected to reach USD 1,801.4 Million by 2036 at a 7.8% CAGR over the 2026 to 2036 forecast period. Municipal water utilities and agrochemical producers are driving this progression as they replace synthetic polyacrylamide flocculants and chemical nematicides with biodegradable amino-polysaccharides. Crustacean shells account for 68.4% of raw material volume in 2026 because aquaculture freezing hubs generate concentrated shell waste. In March 2025, FAO fishery statistics documented over 800,000 metric tons of crustacean shells diverted into bio-refineries [1].
Key Market Trends & Insights
- By raw material source: With a 68.4% share in 2026, crustacean shells led the category as shrimp and crab peeling plants generate concentrated exoskeletal waste.
- By grade / purity: Industrial grade held the leading share of 45.2% in 2026, supported by bulk coagulant orders from municipal sludge dewatering and textile effluent plants.
- By application sector: Water treatment and flocculation accounted for 34.8% of demand in 2026, reflecting utility rules that curb residual synthetic acrylamide monomer in discharged water.
- By distribution channel: Direct B2B contracts represented 62.5% of revenue in 2026, as chemical formulators lock in viscosity and ash tolerances directly with primary refiners.
Regional Highlights
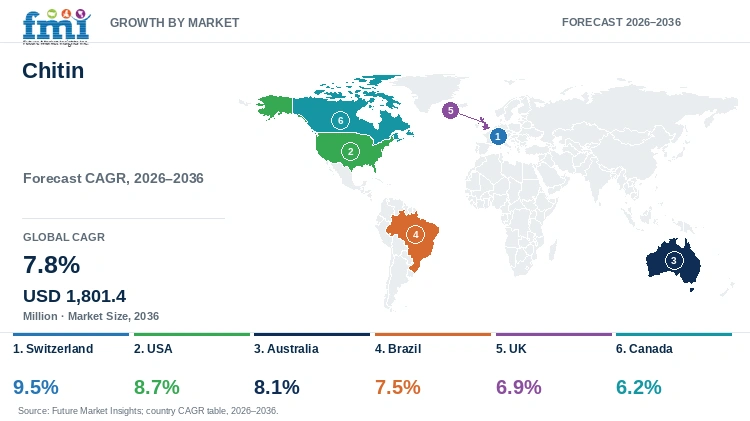
- Fastest-growing evaluated country: Switzerland, at 9.5% CAGR from 2026 to 2036.
- By country: The USA (8.7%), Australia (8.1%), and Brazil (7.5%) follow, while the UK (6.9%) and Canada (6.2%) record steadier expansion trajectories.
Market Size & Forecast
Table 1: Market Size and Forecast for the Chitin Market (USD Million and CAGR percentage), 2025 to 2036
| Metric | Value |
|---|---|
| 2025 Market Size | USD 788.5 Million |
| Estimated Market Size in 2026 | USD 850.0 Million |
| Projected Market Size by 2036 | USD 1,801.4 Million |
| CAGR, 2026 to 2036 | 7.8% |
| Added Revenue, 2026 to 2036 | USD 951.4 Million |
Shrimp and crab peeling hubs in Southeast Asia and North Atlantic ports generate bulk mineral-rich shells, whereas Swiss, German, and U.S. biomedical formulators require strictly deproteinized biopolymers. Traditional coastal extraction plants face tightening environmental inspections over the large volumes of hydrochloric acid and sodium hydroxide consumed during shell demineralization. In February 2025, U.S. Food and Drug Administration allergen and biocompatibility guidance emphasized strict verification of residual tropomyosin protein limits in marine-derived medical materials [2]. Refiners are therefore installing protease enzymatic reactors to supply low-endotoxin flakes for conversion into chitosan derivatives and implantable surgical wound scaffolds across regulated European and North American hospital markets.
Marine Shell Byproduct and Biopolymer Extraction Volume Sizing
Table 2: Marine Shell Byproduct and Biopolymer Extraction Volume Sizing for the Chitin Market (USD Million and units), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| Market size (USD Million) | 788.5 | 850.0 | 1,801.4 |
| Commercial shell biomass processed (thousand metric tons) | 420 to 455 | 445 to 485 | 880 to 960 |
| Refined chitin flake production (thousand metric tons) | 68.5 to 74.2 | 72.8 to 79.5 | 145.0 to 158.0 |
| Average wholesale realization per metric ton (USD) | 11,200 to 11,800 | 11,400 to 12,050 | 12,200 to 12,950 |
Biomass conversion basis: Dry shrimp, crab, and krill shell feedstocks yield 18% to 22% refined chitin flake by weight after demineralization and deproteinization.
Per Capita Consumption and Industrial Utilization Indicators
Municipal sewage plants and agrochemical formulators blend chitin biopolymers into sludge dewatering and seed-treatment recipes to comply with biodegradable discharge limits. Civic utilities and medical device manufacturers represent the main commercial buyers for graded amino-polysaccharides. Industrial procurement teams sourcing water and wastewater treatment chemicals increasingly sign multi-year off-take contracts with coastal refiners to hedge against seasonal shellfish catch swings.
Table 3: Per Capita and Industrial Spending Indicators for the Chitin Market (USD), mixed historical and forecast years from 2025 to 2036
| Metric | 2025 | 2026 | 2036 |
|---|---|---|---|
| World population (billion) | 8.23 | 8.30 | 8.95 |
| Spend per capita (USD) | 0.096 | 0.102 | 0.201 |
| Spend per 1,000 people (USD) | 95.8 | 102.4 | 201.3 |
| Commercial wastewater facility annual polymer spend (USD thousand) | 18.5 to 21.0 | 19.8 to 22.5 | 38.0 to 43.5 |
Table 4: Facility & Extraction Plant Sizing Indicators for the Chitin Market (USD and percentages), mixed reporting years from 2023 to 2026
| Metric | Value | Basis |
|---|---|---|
| Market size, 2026 | USD 850.0 Million | 2026 baseline |
| Commercial marine biopolymer extraction plants worldwide | 420 units | 2024 industrial census |
| Average annual revenue per extraction facility | USD 2.0 Million | Facility average |
| Crustacean shell source revenue, 2026 | USD 581.4 Million | 68.4% share |
Analyst Perspective
"Replacing harsh alkali boiling with protease enzymatic deproteinization and fungal mycelium fermentation lets refiners qualify allergen-free chitin across pharmaceutical and municipal water accounts. Even so, saline wastewater neutralization costs and seasonal shrimp landing swings continue to squeeze margins at coastal extraction plants."
- Nandini Roy Choudhury, Principal Consultant, Future Market Insights.
How is the chitin market segmented?
The chitin market is segmented by raw material source, grade / purity, application sector, and distribution channel. In 2026, Crustacean Shells is projected at 68.4%, industrial grade at 45.2%, water treatment & flocculation at 34.8%, and direct B2B contracts at 62.5%.
By raw material source: Crustacean shells, insect exoskeletons, and fungal mycelium.
By grade / purity: Industrial grade, food and agriculture grade, and pharmaceutical and biomedical grade.
By application sector: Water treatment and flocculation, agriculture and biopesticides, biomedical and wound care, and food and beverage preservatives.
By distribution channel: Direct B2B contracts and chemical distributors and wholesalers.
Why do Crustacean Shells lead the raw material source category?
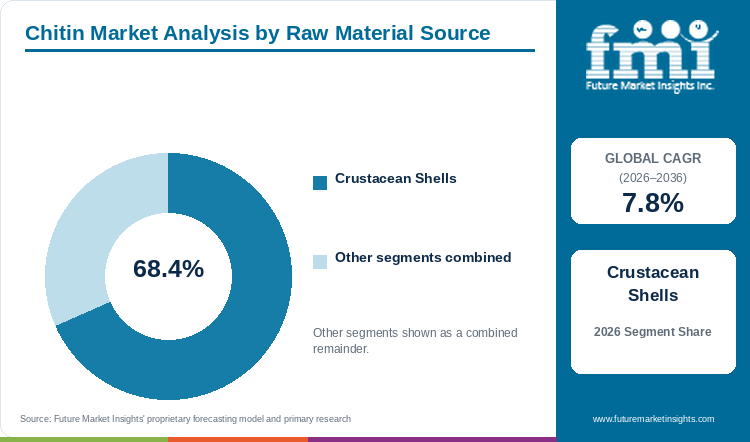
Crustacean shells are expected to account for 68.4% of raw material source volume in 2026, supported by coastal peeling waste.
Table 5: Raw Material Source Share for the Chitin Market (percentage share), 2026
| Raw Material Source | Share (2026) |
|---|---|
| Crustacean Shells | 68.4% |
| Other Segments Combined | 31.6%* |
| Total | 100.0% |
*Calculated as the balance remaining after deducting the leading segment's reported share from 100.0%.
Table 6: Raw Material Source Leadership and Market Growth for the Chitin Market (segment and CAGR percentage), 2026 to 2036
| Metric | Value |
|---|---|
| Global CAGR (2026 to 2036) | 7.8% |
| Leading Segment | Crustacean Shells |
Dry shrimp, crab, and lobster shells contain 18% to 25% natural chitin by weight, giving marine exoskeletal waste a significant yield advantage over insect or fungal biomass. Centralized peeling lines at coastal aquaculture freezing plants allow refiners to feed continuous acid-demineralization reactors without sorting mixed agricultural waste. While food-grade shell extract is frequently hydrolyzed into glucosamine supplements for joint-health tablets, most technical flake tonnage goes into municipal water clarification and crop protection. Coastal refiners still have to wash and dry wet shells immediately at the dock so bacterial spoilage does not degrade polymer viscosity.
- Crustacean shells are projected to account for 68.4% of raw material source volume in 2026, supported by abundant aquaculture byproduct collection and high biopolymer yield.
- In April 2025, Food and Agriculture Organization GLOBEFISH trade assessments reported that commercial shrimp and crab processing hubs increased byproduct shell recovery by 18% year-over-year [3].
What makes Industrial Grade central to the grade and purity category?
Industrial grade is projected to capture 45.2% of grade and purity demand in 2026, driven by municipal wastewater clarification needs.
Municipal sewage plants, mineral tailings ponds, and textile dyehouses buy technical chitin flakes in multi-ton container loads, placing industrial grade at the front of the purity hierarchy. Because effluent clarification does not require cleanroom ultrafiltration or endotoxin removal, industrial-grade flakes can be produced through standard acid-base extraction at a fraction of pharmaceutical unit costs. Blending technical chitin with industrial wastewater treatment chemicals chelates dissolved heavy metals and suspended dyes efficiently. Utilities still test each shipment's residual mineral ash content before dosing the polymer into clarifier basins.
- Industrial grade is estimated to hold 45.2% of grade and purity demand in 2026, driven by high-tonnage coagulant consumption across municipal and textile effluent plants.
- In February 2026, the World Health Organization water, sanitation, and hygiene strategy highlighted bio-based coagulants as a priority option for reducing chemical sludge toxicity in municipal treatment plants [4].
What keeps Water Treatment & Flocculation ahead by application sector?
Water treatment and flocculation is estimated to represent 34.8% of application sector revenue in 2026, owing to synthetic coagulant limits.
Positively charged amine groups along chitin polymer chains bind negatively charged suspended solids, emulsified oils, and heavy metal ions in municipal and industrial wastewater. Tighter environmental limits on residual acrylamide monomer and alum sludge in land-applied biosolids have accelerated utility switching toward biodegradable biopolymers. Chitin flocculants also maintain coagulation efficiency across wide pH swings in food-processing and brewery effluent streams. Dewatered sludge cakes treated with natural amino-polysaccharides can then be composted for agricultural land application without synthetic polymer contamination.
- Water treatment and flocculation is forecast to represent 34.8% of application sector revenue in 2026, owing to strict municipal limits on synthetic polyacrylamide sludge.
- In May 2025, European Food Safety Authority environmental safety evaluations confirmed rapid microbial biodegradability and zero aquatic bioaccumulation for crustacean-derived biopolymer processing aids [5].
How do Direct B2B Contracts anchor the distribution channel category?
Direct B2B contracts are set to command 62.5% of distribution channel sales in 2026, reinforced by multi-year refinery supply agreements.
Downstream manufacturers formulating surgical hemostats, agricultural elicitors, or water-soluble chitosan oligosaccharides cannot tolerate lot-to-lot swings in molecular weight or ash content. Spot chemical distributors rarely guarantee exact deacetylation degrees or trace-protein limits, so industrial buyers negotiate direct multi-year off-take agreements with primary marine refiners and fungal fermentation plants. Direct contracting lets pharmaceutical and water-utility buyers audit raw shell traceability and lock in quarterly flake pricing. Qualifying a new primary refinery still takes six to twelve months of pilot stability testing.
- Direct B2B contracts are anticipated to command 62.5% of distribution channel sales in 2026, reinforced by custom molecular-weight specifications and multi-year volume guarantees.
- In June 2026, Primex ehf signed a multi-year direct supply contract delivering refined marine chitin flakes to European municipal water treatment formulators [6].
What are the drivers, restraints, and opportunities in the chitin market?
In the Chitin Market, regulatory limits on synthetic coagulants and biopesticide demand support growth, caustic extraction effluent costs constrain refining margins, and non-animal fungal fermentation creates high-purity opportunities through 2036.
- Driver: Environmental restrictions on synthetic polyacrylamide flocculants and chemical crop sprays will continue to expand industrial procurement of natural chitin biopolymers through 2036.
- Restraint: High hydrochloric acid and sodium hydroxide consumption during traditional shell extraction will continue to raise wastewater neutralization costs through 2036.
- Opportunity: Precision fungal mycelium fermentation and black soldier fly extraction are expected to unlock allergen-free biomedical and regenerative agriculture contracts through 2036.
Growth Analysis and Future Potential: Qualitative Demand Catalysts
Municipal water authorities and agricultural input makers are phasing out non-biodegradable synthetic polymers as regulators tighten limits on sewage-sludge microplastics and chemical pesticide runoff. In August 2026, the U.S. Environmental Protection Agency finalized guidance on incorporating water treatment removal effects into pesticide risk assessments, supporting wider adoption of biodegradable treatment aids [7]. Agrochemical formulators are also incorporating refined chitin flakes into agricultural bioinsecticides because chitin fragments trigger natural chitinase defense enzymes in crop roots against soil nematodes. Winning municipal and agrochemical tenders requires refiners to deliver consistent mesh particle sizes and low heavy-metal ash.
Risk Assessment of the Chitin Market: Operational and Formulation Friction
Removing calcium carbonate and bound protein from crustacean shells consumes up to 6 metric tons of hydrochloric acid and sodium hydroxide solution for every metric ton of refined chitin flake. In May 2025, a process engineering study in the Journal of Applied Polymer Science found that acid-base reagent consumption and saline effluent neutralization represent 28% to 34% of total operating cost at coastal extraction plants [8]. Coastal environmental agencies have shut down unmodernized peeling and extraction mills that discharge high-salinity wastewater into estuaries. In addition, trace tropomyosin allergens keep conventional shrimp-derived flakes out of injectable drug formulations unless costly enzymatic purification is added.
Commercial Opportunity Analysis: Formulation Differentiation and Value-Add Formats
Submerged fermentation of Aspergillus niger mycelium and controlled black soldier fly rearing allow biotech refiners to produce chitin year-round without marine catch seasonality or shellfish allergens. Fungal chitin exhibits narrow molecular-weight distribution and zero marine heavy-metal carryover, making it ideal for implantable medical devices, according to FMI. In October 2025, Advanced Biopolymers AS expanded cleanroom analytical validation for ultra-pure medical biopolymers used in surgical scaffolds and drug-delivery matrices [9]. Meanwhile, agricultural blenders are adding micronized chitin to commercial biofertilizers to stimulate beneficial rhizosphere microbes in specialty horticulture.
Chitin Market by Country (2026 to 2036)
Pharmaceutical excipient and tissue-engineering demand in Basel and Zurich puts Switzerland at the top of the country growth table with a 9.5% CAGR from 2026 to 2036, while Canada expands at a 6.2% CAGR. Across the USA (8.7%), Australia (8.1%), Brazil (7.5%), and the UK (6.9%), national growth rates reflect how local utilities and agrochemical makers use chitin for drinking-water flocculation, mine-tailings dewatering, and biological crop protection.
Table 7: Country CAGR and Primary Growth Levers for the Chitin Market (CAGR percentage and operational drivers), 2026 to 2036
| Country | CAGR (2026 to 2036) | Primary Growth Lever |
|---|---|---|
| Switzerland | 9.5% | Pharmaceutical formulation demand and advanced biomedical tissue engineering research |
| USA | 8.7% | EPA synthetic coagulant restrictions and agricultural bio-fungicide seed treatment expansion |
| Australia | 8.1% | Mining wastewater flocculation mandates and sustainable aquaculture biopolymer extraction |
| Brazil | 7.5% | Large-scale agricultural biopesticide adoption and sugarcane mill wastewater clarification |
| UK | 6.9% | Strict water utility chemical discharge standards and wound management dressing innovation |
| Canada | 6.2% | Atlantic cold-water shrimp shell recovery and forestry sector effluent remediation |
Source: Future Market Insights analysis
Switzerland Chitin Market Outlook (2026 to 2036)
By 2036, Switzerland is forecast to expand at a 9.5% CAGR, propelled by pharmaceutical excipient R&D and implantable hydrogel manufacturing across the Basel and Zurich life-science clusters. Medical device companies in Switzerland incorporate non-animal chitin and chitosan matrices into absorbable surgical sealants and chronic wound care dressings. In September 2025, the Swiss Federal Office of Public Health updated clinical biomaterial purity guidance requiring strict endotoxin and trace-protein verification for implantable natural polymers [10]. Because landlocked Switzerland has no marine shell industry, Swiss biomedical buyers sign multi-year contracts with certified European fungal and cleanroom refiners.
Key takeaway: Basel and Zurich pharmaceutical excipient R&D and strict implantable biomaterial purity rules anchor Switzerland's high-value demand for endotoxin-free chitin.
USA Chitin Market Outlook (2026 to 2036)
In March 2026, the U.S. Environmental Protection Agency updated its overview of drinking water treatment technologies, highlighting coagulant optimization and membrane pre-treatment for contaminant removal [11]. Municipal stormwater and drinking-water plants across the United States use cationic chitin derivatives to flocculate suspended solids without leaving synthetic acrylamide residues. Demand for chitin in the USA is predicted to advance at an 8.7% CAGR through 2036, reinforced by biological seed-treatment adoption across Corn Belt and California farms. Heavy reliance on imported Asian technical flakes still exposes U.S. formulators to trans-Pacific freight swings, encouraging Gulf Coast shrimp shell recovery.
Key takeaway: EPA drinking-water coagulant optimization and Corn Belt biological seed treatments sustain large-volume U.S. procurement of industrial and agricultural chitin.
Australia Chitin Market Outlook (2026 to 2036)
Mine-tailings dewatering mandates in Western Australia and Queensland alongside coastal prawn aquaculture expansion shape the Australian biopolymer market. The Australia chitin sector is projected to record an 8.1% CAGR during the assessment period as mineral processors replace synthetic flocculants with biodegradable crustacean polymers in tailings settling ponds. In July 2025, Australia's Department of Agriculture, Fisheries and Forestry reported that commercial prawn and rock lobster processors increased shell byproduct utilization by 21% under national marine waste diversion grants [12]. High domestic chemical labor wages and long inland haulage distances have prompted Australian operators to deploy modular enzymatic extraction units directly at coastal seafood parks.
Key takeaway: Western Australian and Queensland mine-tailings remediation laws and coastal prawn shell recovery programs drive Australian adoption of biodegradable chitin flocculants.
Brazil Chitin Market Outlook (2026 to 2036)
Commercial chitin demand in Brazil is anticipated to grow at a 7.5% CAGR through 2036 as soybean, cotton, and sugarcane growers apply chitin-based nematicides and foliar elicitors to cut synthetic pesticide residues. Large-scale biological crop protection gives Brazil an agricultural demand profile that contrasts sharply with European biomedical markets. In August 2025, Brazil's Ministry of Agriculture and Livestock (MAPA) registered a record batch of biological control and bio-input formulations under the National Bioinputs Program [13]. Because domestic shrimp peeling waste in northeastern Brazil is only partially consolidated for chemical refining, local agrochemical blenders supplement domestic extraction with imported technical flakes.
Key takeaway: Record bio-input registrations under Brazil's National Bioinputs Program fuel rapid adoption of chitin-based nematicides across soybean and sugarcane plantations.
UK Chitin Market Outlook (2026 to 2036)
In November 2025, the UK Environment Agency issued updated technical guidance requiring water utilities to curb chemical coagulant carryover and phosphorus discharges into river catchments [14]. River-catchment water quality rules and specialized hemostatic dressing production anchor chitin demand across the United Kingdom. Between 2026 and 2036, the UK market is expected to progress at a 6.9% CAGR, supported by NHS hospital procurement of antimicrobial chitin and chitosan matrices for advanced wound management. Post-Brexit customs checks and North Sea nephrops landing quotas still limit domestic raw shell volume, so UK formulators source refined flakes under multi-year contracts with Icelandic and Norwegian refiners.
Key takeaway: UK Environment Agency river-discharge limits and NHS hemostatic wound-dressing procurement sustain steady British demand for refined chitin biopolymers.
Canada Chitin Market Outlook (2026 to 2036)
Cold-water northern shrimp and snow crab landings across Newfoundland, Nova Scotia, and Quebec give Canada one of the largest raw crustacean shell bases in North America. Sales of chitin in Canada are forecast to expand at a 6.2% CAGR through 2036 as pulp-and-paper mills and municipal water plants adopt bio-based coagulants for cold-water effluent treatment. In December 2025, Fisheries and Oceans Canada documented that Atlantic shellfish processing plants diverted over 64,000 metric tons of shrimp and crab shells from coastal landfills into biopolymer and marine-meal recovery [15]. Short spring-and-summer fishing seasons still require Canadian refiners to operate heated shell-drying silos for year-round extraction.
Key takeaway: Atlantic Canada's 64,000-ton shellfish waste diversion base and pulp-mill effluent remediation anchor steady domestic chitin refining.
Full report country CAGRs cover: North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa.
Who are the notable companies in the chitin market?
Primex ehf, Heppe Medical Chitosan GmbH, KitoZyme S.A., Meron Group, Advanced Biopolymers AS, Golden-Shell Biochemical Co., Ltd., Marine Chemicals, and G.T.C. Bio Corporation are the significant market players in this market.
Supplier positioning in the chitin market reflects raw feedstock access and cleanroom purification capability, as per the analysis from FMI. Primex ehf, Golden-Shell Biochemical Co., Ltd., and Marine Chemicals run high-tonnage coastal shell demineralization plants near shrimp and crab landings to supply water-treatment and agrochemical buyers. Heppe Medical Chitosan GmbH and Advanced Biopolymers AS focus on ISO 13485 cleanroom purification of low-endotoxin polymers for surgical devices, whereas KitoZyme S.A., Meron Group, and G.T.C. Bio Corporation develop non-animal fungal mycelium chitin and agricultural elicitor grades.
- Integrated Marine Biopolymer Corporations: Primex ehf, Golden-Shell Biochemical Co., Ltd., and Marine Chemicals operate high-tonnage marine shell processing plants supplying industrial utilities.
- Specialized Medical-Grade Manufacturers: Heppe Medical Chitosan GmbH and Advanced Biopolymers AS produce high-purity biomedical polymers for surgical and pharmaceutical applications.
- Fungal and Fermentation Innovators: KitoZyme S.A., Meron Group, and G.T.C. Bio Corporation pioneer non-animal fungal mycelium extraction and advanced agricultural biopesticides.
Competitive Benchmarking: Chitin Market
Table 8: Competitive Benchmarking for the Chitin Market (qualitative capability ratings), 2026
| Company | Extraction Yield Capacity | Biomedical Purity Certification | Global Distribution Reach | Geographic Reach |
|---|---|---|---|---|
| Primex ehf | High | High | High | High |
| Heppe Medical Chitosan GmbH | Medium | High | High | High |
| KitoZyme S.A. | High | High | High | High |
| Meron Group | High | Medium | High | Medium |
| Advanced Biopolymers AS | Medium | High | Medium | Medium |
| Golden-Shell Biochemical Co., Ltd. | High | High | High | High |
| Marine Chemicals | High | Medium | High | Medium |
| G.T.C. Bio Corporation | Medium | Medium | Medium | Medium |
Scoring basis: Benchmark ratings evaluate annual biomass extraction tonnage, ISO 13485 and GMP medical purity certifications, and international chemical supply agreements without ranking firms by revenue share.
Key Developments in the Chitin Market
- In March 2026, Primex ehf completed a modernization and drying upgrade at its Siglufjordur marine biopolymer plant in Iceland, raising refined chitin flake capacity by 25% [16].
- In January 2026, Heppe Medical Chitosan GmbH introduced a GMP-certified, ultra-pure biopolymer series engineered for cardiovascular surgical sealants and hemostatic sponges [17].
- In November 2025, KitoZyme S.A. received European regulatory clearance for its non-animal fungal chitin-glucan and chitosan excipient line in oral pharmaceutical formulations [18].
- In August 2025, Golden-Shell Biochemical Co., Ltd. commissioned an automated enzymatic deproteinization line that reduces process water and caustic chemical usage by 40% [19].
Key Players in the Chitin Market
Integrated Marine Biopolymer Corporations
- Primex ehf
- Golden-Shell Biochemical Co., Ltd.
- Marine Chemicals
Specialized Medical-Grade Manufacturers
- Heppe Medical Chitosan GmbH
- Advanced Biopolymers AS
Fungal and Fermentation Innovators
- KitoZyme S.A.
- Meron Group
- G.T.C. Bio Corporation
Chitin Market - Report Scope
Table 9: Report Scope for the Chitin Market (coverage fields and definitions), 2026 to 2036
| Coverage field | Report scope |
|---|---|
| Market breakdown | Raw Material Source; Grade / Purity; Application Sector; Distribution Channel; Region |
| Quantitative Units | USD Million |
| Market Definition | Includes commercial supplier revenue from refined chitin flakes, powders, and primary chitin biopolymer intermediates extracted from crustacean shells, insect exoskeletons, and fungal mycelium. Excludes downstream finished medical devices, formulated retail cosmetics, and raw unrefined seafood waste. |
| Regions Covered | North America; Latin America; Western Europe; Eastern Europe; East Asia; South Asia and Pacific; Middle East and Africa |
| Countries Covered | Switzerland, USA, Australia, Brazil, UK, Canada, and additional countries in the full report |
| Key Companies Covered | Primex ehf, Heppe Medical Chitosan GmbH, KitoZyme S.A., Meron Group, Advanced Biopolymers AS, Golden-Shell Biochemical Co., Ltd., Marine Chemicals, G.T.C. Bio Corporation |
| Forecast Period | 2026 to 2036 |
| Approach | Primary and secondary research with rigorous market triangulation. |
Chitin Market - Research Methodology
Table 10: Research Methodology for the Chitin Market (research methods and approach), 2026 edition
| Method | Approach |
|---|---|
| Primary Research | Primary interviews were conducted with biopolymer extraction chemical engineers, aquaculture byproduct managers, municipal water treatment directors, agrochemical formulators, and biomedical R&D specialists. |
| Secondary Research | Secondary research synthesized FAO fishery and aquaculture statistics, EPA and WHO water treatment publications, medical polymer regulatory filings, corporate annual reports, and technical literature. |
| Market Sizing and Forecasting | Market sizing and forecasting for the 2026 to 2036 period were developed using top-down and bottom-up models reconciling commercial shell and fungal extraction yields against end-sector procurement. |
| Data Triangulation and Validation | Estimates were validated against regional crustacean landing volumes, chemical plant capacities, and wholesale grade realizations to ensure accuracy without double counting downstream derivatives. |
| Country Forecasting Model | Country-level CAGRs are projected via FMI's biopolymer econometric model, calibrating evaluated national growth rates against the 7.8% global baseline through verified crustacean aquaculture processing volume, industrial wastewater flocculation demand, and biomedical grade biopolymer conversion. |
| Operational Benchmark Traceability | Operational benchmarks (commercial shell biomass processed, deacetylation reaction efficiencies, and biofertilizer application rates) represent modeled estimates synthesized from FAO FishStat statistics, EPA water quality guidelines, and commercial chitosan refiner disclosures. |
Chitin Market by Segments
Chitin Market segmented by Raw Material Source:
- Crustacean Shells
- Insect Exoskeletons
- Fungal Mycelium
Chitin Market segmented by Grade / Purity:
- Industrial Grade
- Food & Agriculture Grade
- Pharmaceutical & Biomedical Grade
Chitin Market segmented by Application Sector:
- Water Treatment & Flocculation
- Agriculture & Biopesticides
- Biomedical & Wound Care
- Food & Beverage Preservatives
Chitin Market segmented by Distribution Channel:
- Direct B2B Contracts
- Chemical Distributors & Wholesalers
Chitin Market by Region
- North America
- United States
- Canada
- Latin America
- Brazil
- Mexico
- Argentina
- Chile
- Western Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Switzerland
- Nordics
- Eastern Europe
- Poland
- Czech Republic
- Romania
- Hungary
- East Asia
- China
- Japan
- South Korea
- South Asia and Pacific
- India
- ASEAN
- Australia and New Zealand
- Middle East and Africa
- GCC Countries
- South Africa
- Israel
- Turkiye
Research Sources and Bibliography
- [1] Food and Agriculture Organization of the United Nations. (2025, March 31). Global fishery and aquaculture production statistics: March 2025 FishStat update. FAO Fisheries and Aquaculture Division.
- [2] U.S. Food and Drug Administration. (2025, February 20). Food allergies, crustacean shellfish allergen labeling, and residual protein control guidance. Center for Food Safety and Applied Nutrition.
- [3] FAO GLOBEFISH. (2025, April 18). Circular utilization of shrimp and crab shell byproducts in commercial marine biorefineries. Food and Agriculture Organization of the United Nations.
- [4] World Health Organization. (2026, February 20). WHO water, sanitation, hygiene and waste strategy 2026-2035. WHO Water, Sanitation and Health Division.
- [5] European Food Safety Authority. (2025, May 18). Environmental safety and biodegradability evaluation of crustacean-derived biopolymer processing aids. EFSA Journal, 23(5), e08519.
- [6] Primex ehf. (2026, June 22). Multi-year direct supply agreement with European water treatment formulators for natural coagulants. Primex Corporate Press Release.
- [7] U.S. Environmental Protection Agency. (2026, August 24). Finalization of guidance on incorporation of water treatment effects in pesticide risk assessments. EPA Office of Pesticide Programs.
- [8] Journal of Applied Polymer Science. (2025, May 29). Process economics and saline effluent neutralization costs in crustacean chitin demineralization. Polymer Engineering Review, 142(10), 52410.
- [9] Advanced Biopolymers AS. (2025, October 28). Cleanroom analytical validation for implantable medical-grade chitin and chitosan polymers. Nordic Biotech Technical Bulletin.
- [10] Federal Office of Public Health (FOPH). (2025, September 14). Clinical biomaterial purity and endotoxin verification standards for naturally derived polymers. Swiss Confederation Health Monograph.
- [11] U.S. Environmental Protection Agency. (2026, March 23). Overview of drinking water treatment technologies: Coagulation, flocculation, and filtration. EPA Safe Drinking Water Act Technical Series.
- [12] Department of Agriculture, Fisheries and Forestry (DAFF). (2025, July 20). Marine resource circularity: Prawn and lobster shell waste recovery across Australian fisheries. Australian Government Sectoral Review.
- [13] Ministry of Agriculture and Livestock (MAPA). (2025, August 26). National Bioinputs Program: Registration of chitin-based nematicides and biological seed coatings in Brazil. Government of Brazil Agricultural Monograph.
- [14] Environment Agency. (2025, November 12). Reducing chemical phosphorus and synthetic polymer discharges in UK municipal water utilities. UK Government Environmental Report.
- [15] Fisheries and Oceans Canada. (2025, December 08). Atlantic cold-water shrimp and snow crab shell waste diversion and biopolymer recovery report. Government of Canada Sectoral Monograph.
- [16] Primex ehf. (2026, March 14). Completion of drying and refining capacity expansion at Siglufjordur marine biopolymer facility. Primex Corporate Release.
- [17] Heppe Medical Chitosan GmbH. (2026, January 20). Launch of GMP ultra-pure biopolymers for cardiovascular surgical sealants. Heppe Medical Product Announcement.
- [18] KitoZyme S.A. (2025, November 19). European regulatory clearance for non-animal fungal chitin-glucan excipients in oral drug delivery. KitoZyme Media Bulletin.
- [19] Golden-Shell Biochemical Co., Ltd. (2025, August 12). Commissioning of automated enzymatic deproteinization lines reducing water and caustic reagent use. Golden-Shell Manufacturing Report.
- [20] Meron Group. (2026, April 09). Expansion of technical-grade marine chitin flake distribution across Asian water treatment markets. Meron Corporate Update.
- [21] Marine Chemicals. (2026, February 15). Technological upgrades in continuous shrimp shell demineralization and agricultural flake synthesis. Marine Chemicals Processing Bulletin.
This bibliography is provided for reader reference and is not exhaustive. The full report contains the complete references and dataset.
This Report Answers
- How large is the chitin market in 2026 and what is forecast for 2036?
- Which environmental and wastewater mandates support demand for chitin?
- Why do crustacean shells lead the raw material source category?
- Why does industrial grade lead the grade and purity category globally?
- How do growth rates prominently differ across Switzerland, USA, Australia, and Brazil?
- Which leading companies supply relevant biopolymer and extraction categories today?
- What limits adoption or chemical processing efficiency in the chitin market?
- What should industrial procurement directors evaluate deeply before purchasing bulk chitin flakes?
Frequently Asked Questions
How big is the chitin market in 2026, and what is forecast for 2036?
The global chitin market is estimated to reach USD 850.0 Million in 2026 and is projected to expand to USD 1,801.4 Million by 2036 as water utilities and agrochemical producers replace synthetic polymers with biodegradable polysaccharides.
What is the CAGR for the chitin market from 2026 to 2036?
As per FMI, the chitin market is projected to expand at a 7.8% CAGR from 2026 to 2036, supported by stricter limits on synthetic polyacrylamide coagulants and rising biomedical wound-care adoption.
Which raw material source segment leads the chitin market in 2026?
Crustacean shells are projected to hold 68.4% of raw material source volume in 2026 because coastal shrimp and crab peeling plants supply dense, centralized shell biomass with high natural biopolymer yields.
Which grade segment holds the largest share in the chitin market in 2026?
Industrial grade accounts for 45.2% of grade and purity demand in 2026, driven by multi-ton annual consumption across municipal wastewater clarification and industrial sludge dewatering plants.
Which country has a notable growth outlook during the assessment period?
FMI finds that Switzerland is projected to register a 9.5% CAGR from 2026 to 2036, supported by intensive pharmaceutical excipient research and high-value biomedical hydrogel manufacturing.
Who are the active companies in the chitin market?
Notable companies include Primex ehf, Heppe Medical Chitosan GmbH, KitoZyme S.A., Meron Group, Advanced Biopolymers AS, Golden-Shell Biochemical Co., Ltd., Marine Chemicals, and G.T.C. Bio Corporation. These producers focus on enzymatic shell deproteinization, ISO 13485 medical purification, and non-animal fungal mycelium fermentation.
Preview the report firsthand - request a free sample
Get SampleGet the brochure for pricing and purchase details.
Get PDFTable of Content
- Key Takeaways
- Market Size and CAGR
- Top Growth Driver
- Fastest Growing Segment
- Leading Region
- Key Companies
- Emerging Opportunities
- Executive Summary
- Global Market Outlook
- Demand-side Trends
- Supply-side Trends
- Technology Roadmap Analysis
- Analysis and Recommendations
- Analyst Perspective (What is happening? Why now? What should investors know?)
- Key Questions Answered
- How large is the market?
- What is the CAGR?
- What are key trends?
- Which region dominates?
- Who are the leaders?
- Market Overview
- Market Coverage / Taxonomy
- Market Definition / Scope / Limitations
- Research Methodology
- Chapter Orientation
- Analytical Lens and Working Hypotheses
- Market Structure, Signals, and Trend Drivers
- Benchmarking and Cross-market Comparability
- Market Sizing, Forecasting, and Opportunity Mapping
- Research Design and Evidence Framework
- Desk Research Programme (Secondary Evidence)
- Expert Input and Fieldwork (Primary Evidence)
- Tooling, Models, and Reference Databases
- Data Engineering and Model Build
- Quality Assurance and Audit Trail
- Market Background
- Market Dynamics (Drivers, Restraints, Opportunity, Trends)
- Scenario Forecast (Optimistic, Likely, Conservative)
- Impact Analysis
- AI Impact
- Sustainability Impact
- Regulatory Impact
- Technology Impact
- Consumer / Buyer Analysis
- Purchase Drivers
- Adoption Barriers
- Buyer Journey
- Opportunity Map Analysis
- Product Life Cycle Analysis
- Supply Chain Analysis
- Investment Feasibility Matrix
- Value Chain Analysis
- PESTLE and Porter's Analysis
- Regulatory Landscape
- Regional Parent Market Outlook
- Production and Consumption Statistics
- Import and Export Statistics
- Global Market Analysis and Forecast, 2021 to 2036
- Historical Market Size Value (USD Million) Analysis, 2021 to 2025
- Current and Future Market Size Value (USD Million) Projections, 2026 to 2036
- Y-o-Y Growth Trend Analysis
- Absolute $ Opportunity Analysis
- Global Market Pricing Analysis, 2021 to 2036
- Global Market Analysis and Forecast, By Raw Material Source, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Raw Material Source, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Raw Material Source, 2026 to 2036
- Crustacean Shells
- Insect Exoskeletons
- Fungal Mycelium
- Y-o-Y Growth Trend Analysis By Raw Material Source, 2021 to 2025
- Absolute $ Opportunity Analysis By Raw Material Source, 2026 to 2036
- Global Market Analysis and Forecast, By Grade / Purity, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Grade / Purity, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Grade / Purity, 2026 to 2036
- Industrial Grade
- Food & Agriculture Grade
- Pharmaceutical & Biomedical Grade
- Y-o-Y Growth Trend Analysis By Grade / Purity, 2021 to 2025
- Absolute $ Opportunity Analysis By Grade / Purity, 2026 to 2036
- Global Market Analysis and Forecast, By Application Sector, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Application Sector, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Application Sector, 2026 to 2036
- Water Treatment & Flocculation
- Agriculture & Biopesticides
- Biomedical & Wound Care
- Food & Beverage Preservatives
- Y-o-Y Growth Trend Analysis By Application Sector, 2021 to 2025
- Absolute $ Opportunity Analysis By Application Sector, 2026 to 2036
- Global Market Analysis and Forecast, By Distribution Channel, 2021 to 2036
- Introduction / Key Findings
- Historical Market Size Value (USD Million) Analysis By Distribution Channel, 2021 to 2025
- Current and Future Market Size Value (USD Million) Analysis and Forecast By Distribution Channel, 2026 to 2036
- Direct B2B Contracts
- Chemical Distributors & Wholesalers
- Y-o-Y Growth Trend Analysis By Distribution Channel, 2021 to 2025
- Absolute $ Opportunity Analysis By Distribution Channel, 2026 to 2036
- Global Market Analysis and Forecast, By Region, 2021 to 2036
- Introduction
- Historical Market Size Value (USD Million) Analysis By Region, 2021 to 2025
- Current Market Size Value (USD Million) Analysis and Forecast By Region, 2026 to 2036
- North America
- Latin America
- Western Europe
- Eastern Europe
- East Asia
- South Asia and Pacific
- Middle East and Africa
- Market Attractiveness Analysis By Region
- North America Market Analysis and Forecast, By Country, 2021 to 2036
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- United States
- Canada
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Key Takeaways
- Latin America Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Brazil
- Mexico
- Argentina
- Chile
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Key Takeaways
- Western Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Germany
- France
- United Kingdom
- Italy
- Spain
- Switzerland
- Nordics
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Key Takeaways
- Eastern Europe Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- Poland
- Czech Republic
- Romania
- Hungary
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Key Takeaways
- East Asia Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- China
- Japan
- South Korea
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Key Takeaways
- South Asia and Pacific Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- India
- ASEAN
- Australia and New Zealand
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Key Takeaways
- Middle East and Africa Market Analysis and Forecast, By Country
- Historical Market Size Value (USD Million) Trend Analysis By Market Taxonomy, 2021 to 2025
- Market Size Value (USD Million) Forecast By Market Taxonomy, 2026 to 2036
- By Country
- GCC Countries
- South Africa
- Israel
- Turkiye
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- By Country
- Market Attractiveness Analysis
- By Country
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Key Takeaways
- Key Countries Market Analysis
- United States
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Canada
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Mexico
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Brazil
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Chile
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Germany
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- United Kingdom
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Italy
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Spain
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- France
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- India
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- ASEAN
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Australia and New Zealand
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- China
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Japan
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- South Korea
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Poland
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Hungary
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- South Africa
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Switzerland
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Australia
- Pricing Analysis
- Market Share Analysis, 2025
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- United States
- Market Structure Analysis
- Competition Dashboard
- Competition Benchmarking
- Market Share Analysis of Top Players
- By Regional
- By Raw Material Source
- By Grade / Purity
- By Application Sector
- By Distribution Channel
- Emerging Startups
- Innovation Benchmarking
- Competition Analysis
- Competition Deep Dive
- Primex ehf
- Overview
- Product Portfolio
- Profitability by Market Segments
- Sales Footprint
- Strategy Overview
- Marketing Strategy
- Product Strategy
- Channel Strategy
- Heppe Medical Chitosan GmbH
- KitoZyme S.A.
- Meron Group
- Advanced Biopolymers AS
- Golden-Shell Biochemical Co., Ltd.
- Marine Chemicals
- G.T.C. Bio Corporation
- Primex ehf
- Case Studies
- Success Stories
- Recent Developments
- Competition Deep Dive
- Assumptions & Acronyms Used


